Haver Analytics
Haver Analytics

Economy in Brief: 2026

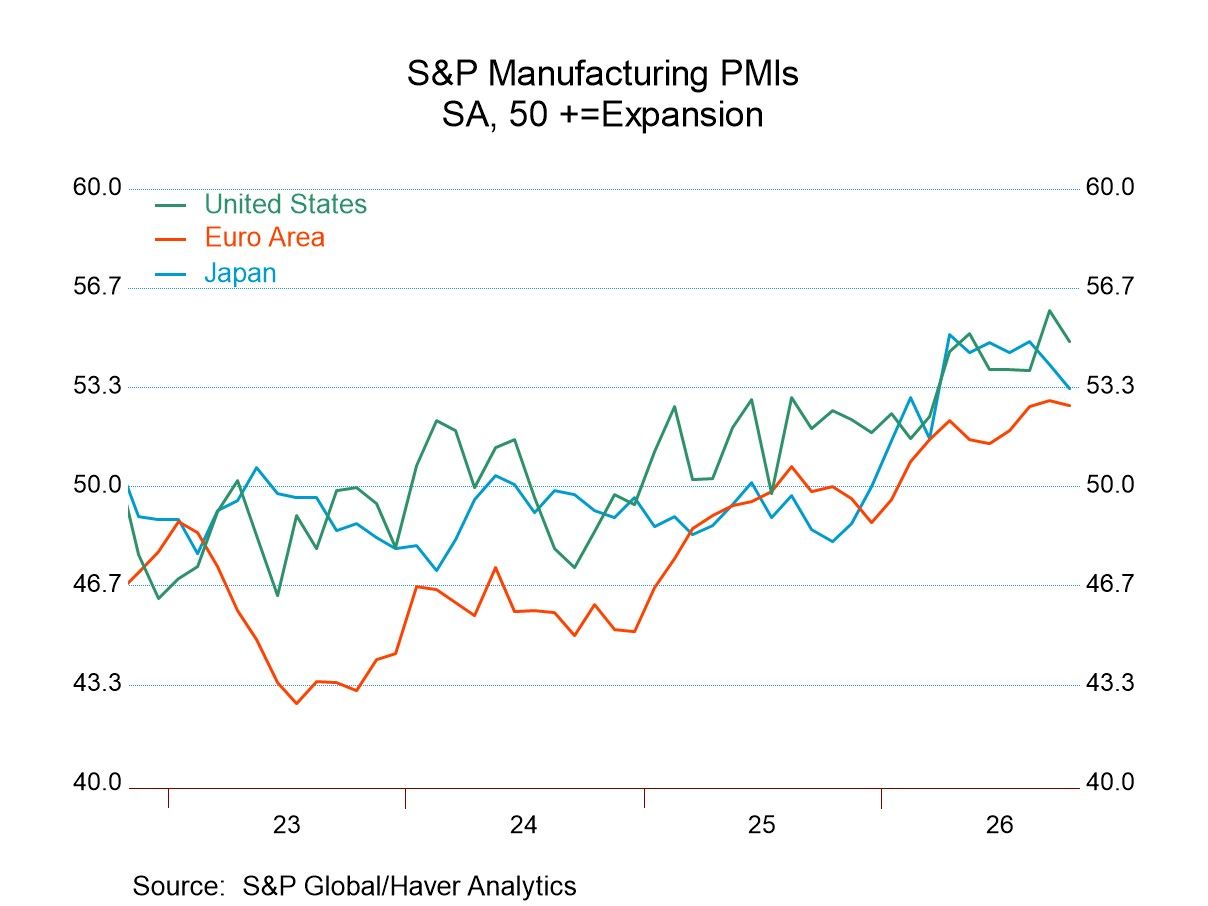
  • The PMI story for October shows PMIs weakening in 11 of the 18 countries that report manufacturing data. The manufacturing PMIs ticked down only slightly month-to-month, falling in 11 of eighteen reporters in October. The median reading over 12 months, six months, and three months progresses from 51.2 over 12 months to 52.2 over six months to 52.1 over three months. There's really not much change there to base a lot of analysis on; conditions have been substantially the same across this broad group of countries.

    Sequentially the PMI data show that over three months 13 of the 18 early reporting countries have lower PMI values with only 5 showing better values. Over six months, six countries show worsening results with 12 showing improvement. Over 12 months, only four countries show worsening results with 14 showing improvement. As we look at the breadth of improvement versus deterioration from 12 months to six months to three months, there's a narrowing, a clear narrowing, in terms of the breadth of countries showing conditions getting better compared to those showing conditions getting worse. However, that statement also exists in the same world where the median for the group hasn't changed very much over any of those horizons.

    Understanding this period – is it representative? To get a broader perspective, we can look at the rank or queue percentile standings that give us a percentile standing for each of the reporting countries or areas on data back to January 2021, a relatively broad period. However, it's not a time span in which activity was particularly strong. Still, using the EMU Commission readings on the EMU as a benchmark, the average back to 1990 shows the ranking of the current period average assessment has nearly normal average for the shorter period that makes the short period average seem representative in terms of the longer timeline as well. The reading for October is only 3% below the EMU mean on data back to 1990. So, the rankings over this period may also be a reasonable proxy for longer term rankings in the broadest sense.

    There was some strength in the recovery and in the immediate post-COVID. And then there was the invasion of Ukraine that really knocked things back down. Subsequently there were U.S. tariffs imposed that created another international kerfuffle, and then the attack by Hamas on Israel, and the subsequent attempt to rein in Iran by the U.S. and Israel with significant knock-on effects that are largely still in place involving the difficulty for oil and other commodities to pass safely through the Strait of Hormuz. So, rankings on this timeline are not for a period of robust growth, but then that is not unusual, statistically. Part of that is that our period begins on a post-COVID high with activity having rebounded. The median percentile standing for this group on data back to January 2021 is a 67.2 percentile standing, which places it just barely into the top third of all observations on this timeline. Only three countries log percentile standings in the top 20% of all their observations during this span. They are Japan, Indonesia, and Malaysia, all Asian economies. The weakest readings on the period, at readings of around 25% and lower, include India at a 20.9 percentile standing, Turkey at a 22.4 percentile standing, and Brazil at a very weak 6th percentile standing. The grouping of these weakest economies includes two BRIC economies plus Turkey.

    The large economies are doing well compared to their performance over this timeline, with the euro area economies having a 76.1 percentile standing, Germany, in particular, having a 76.1 percentile standing, the U.S. having a 79.1 percentile standing, the U.K. having a 73.1 percentile standing, and Japan having an 80.6 percentile standing. However, in contrast, France, with all of its fiscal trouble, has only a 53.7 percentile standing over the same period. Oil prices are shooting up again as the U.S. midterm elections draw near. There is a creeping rumor mill of commentary that suggests that the U.S. will be increasing hostilities against Iran after the midterm elections. That buzz has markets on edge and oil prices are moving higher again.
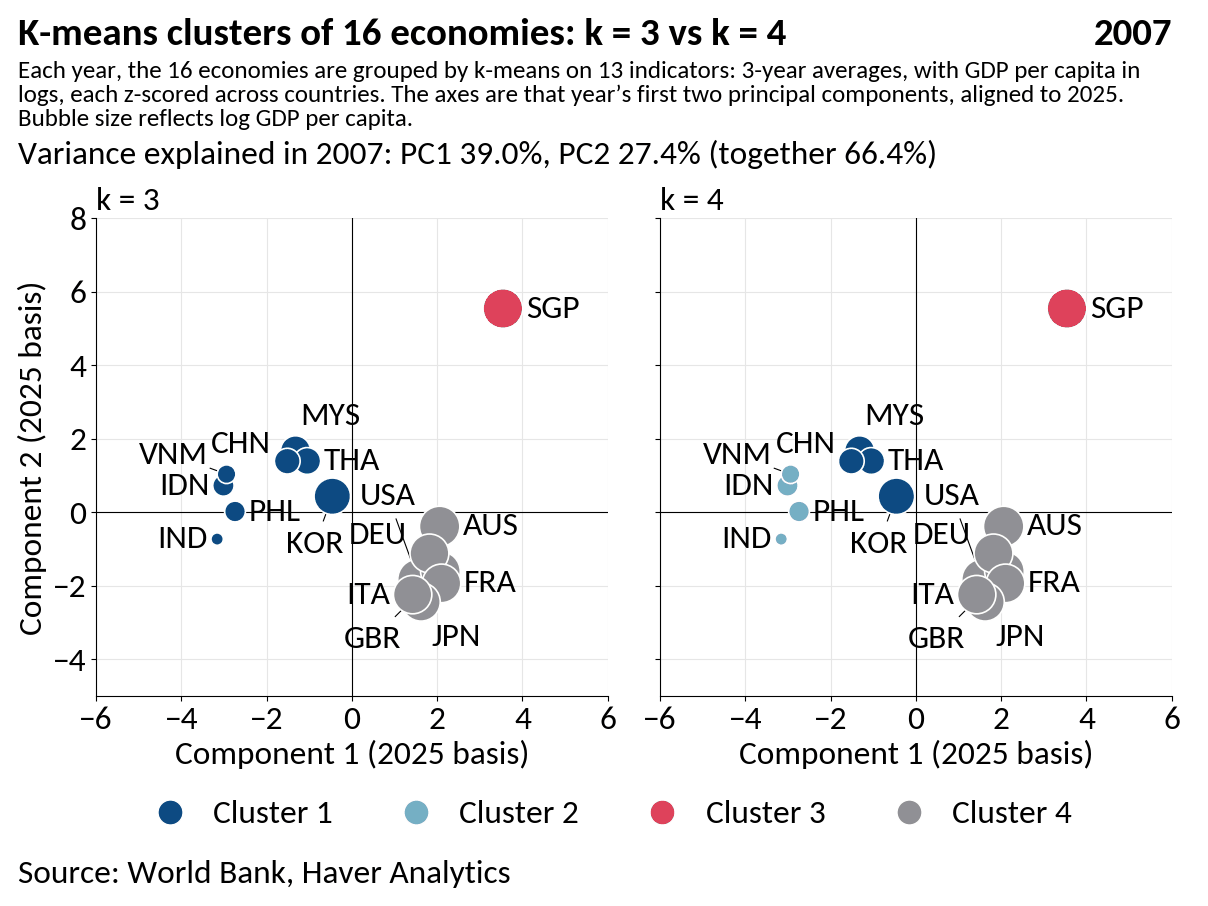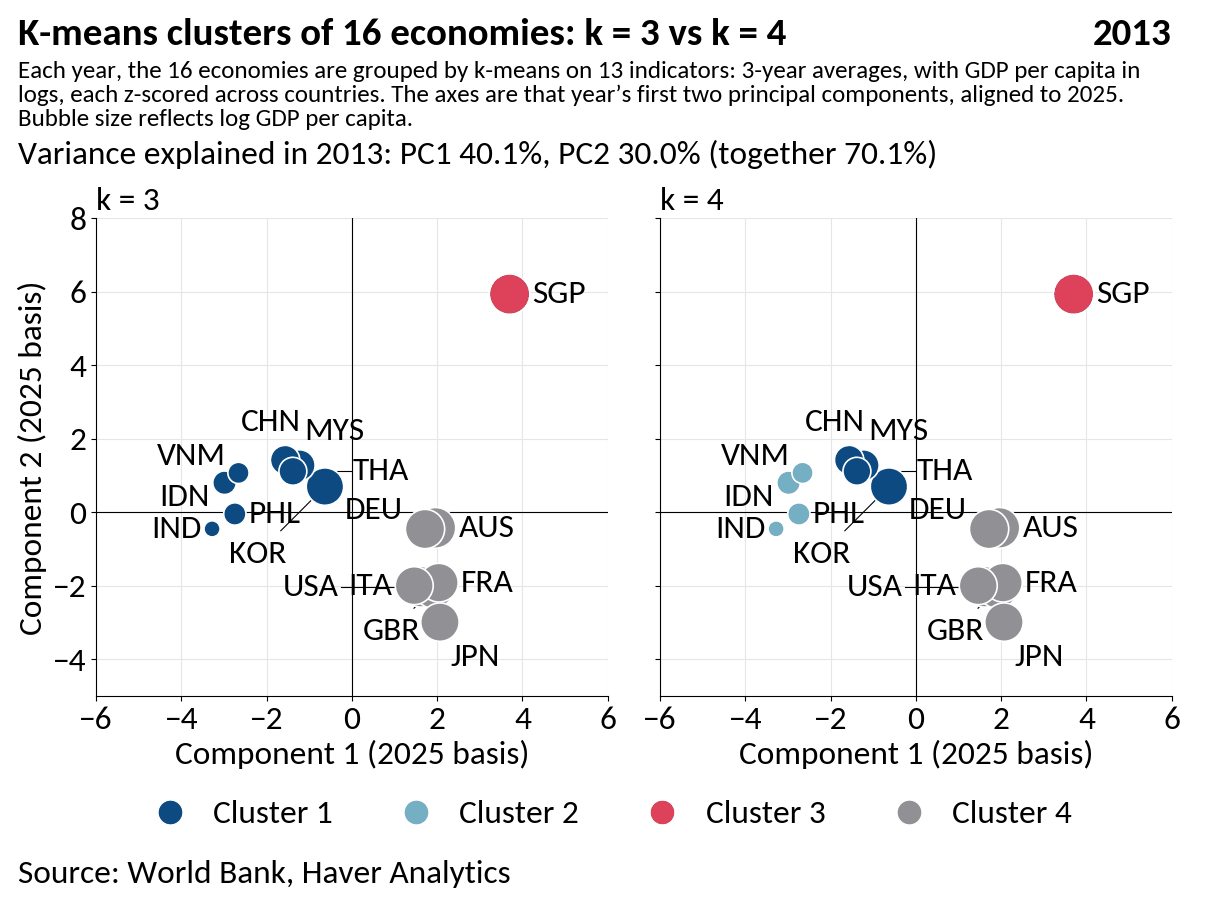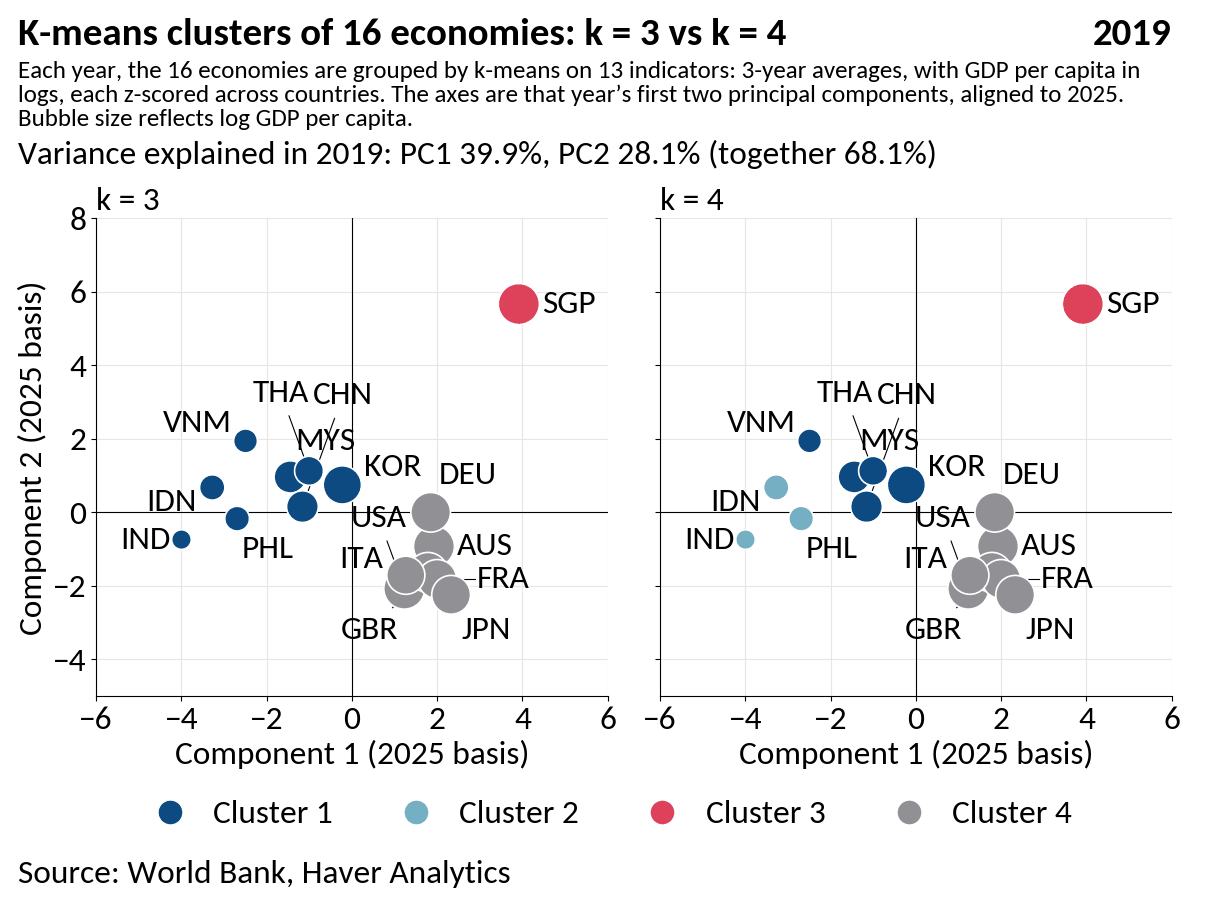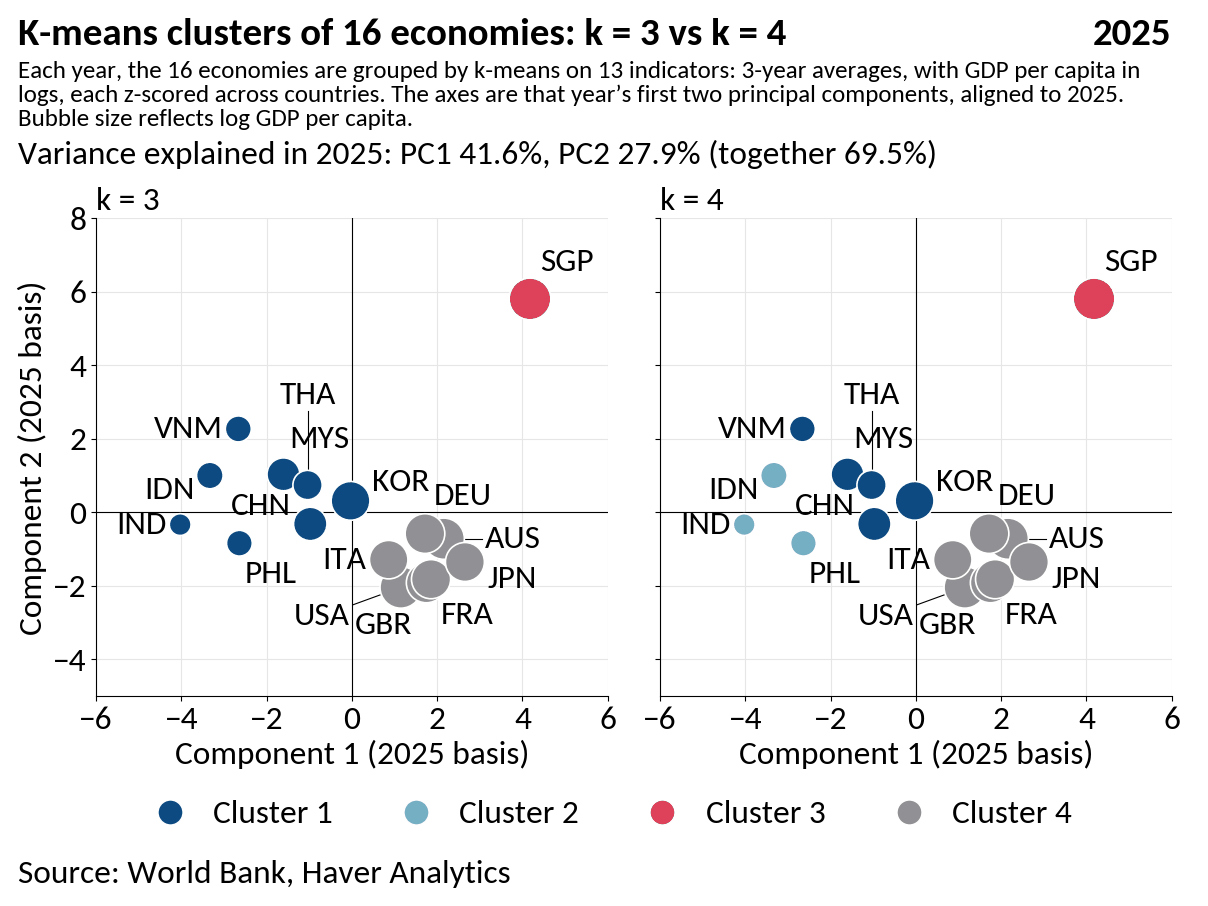
  • In this week’s Letter, we examine what distinguishes Asia’s economies, how those differences have evolved, and whether the AI boom is reinforcing them. Using 13 indicators covering income, economic structure, trade, demographics and public finances, we group 16 Asian and other major economies according to their similarities (chart 1). Principal component analysis then helps identify the main patterns behind these groupings (chart 2). The results distinguish the developed economies and Singapore from the rest of Asia, while also separating the more industrialised Asian economies from the younger, more agricultural economies of India, Indonesia and the Philippines (charts 3 and 4). These structural divisions have proved persistent: every economy finished 2025 in the same cluster as in 2019, despite some movement in between (chart 5). The AI boom is now providing a stronger lift to semiconductor exporters and economies attracting data centre investment (chart 6). Without substantial structural change elsewhere, the gaps between these groups could widen even as their membership remains stable.

    Asia in clusters K-means clustering offers a simple way to sort economies by how alike they are. The algorithm assigns each economy to one of k groups, placing it with the group whose average profile it most closely resembles. The number of groups, k, is a hyperparameter: the analyst chooses it, rather than the algorithm learning it from the data. We apply the method to 16 Asian and other major economies, using 13 indicators covering wealth, sectoral structure, the external sector, demographics and public finances. With k set at three, distinct groups emerge (chart 1). The developed economies form one cluster, the rest of Asia, including China and Korea, forms a second, and Singapore stands alone as a third. Raising k to four leaves the developed group and Singapore unchanged. Instead, it draws finer distinctions within emerging Asia, with India, Indonesia and the Philippines breaking away to form a cluster of their own. We explore why Singapore stands apart, and which indicators drive these splits, in the sections that follow.

    • Compensation costs ease in Q3.
    • Wage pressures at a five-year low.
    • Benefit costs at a three-year high.
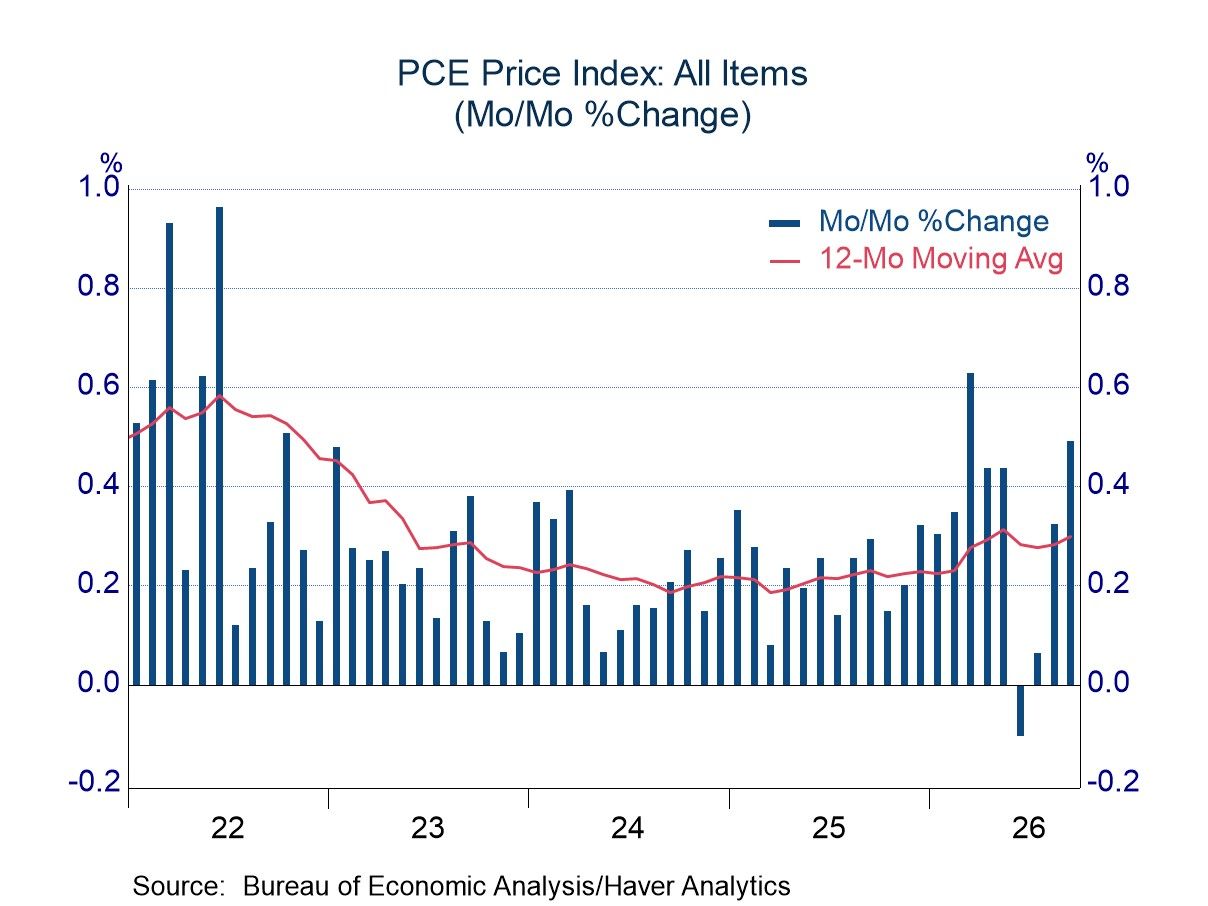
    • Inflation was as expected in September, but still unsettling.
    • Inflation eroded increases in nominal income and consumption.
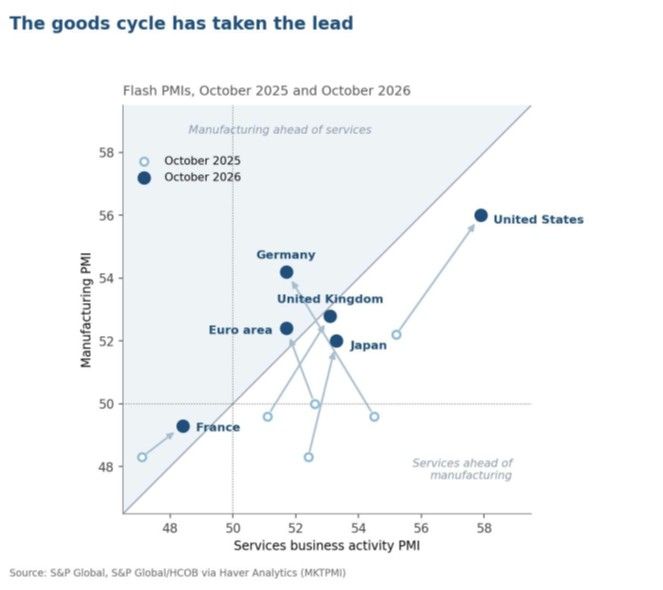
  • Four central banks are deciding policy this week, and the first two have set the tone. The Federal Reserve left its policy rate unchanged while the Bank of Canada delivered a further quarter-point increase. The European Central Bank reports today and the Bank of Japan at the end of the week. Markets have given them an awkward backdrop. Ten-year Treasury yields have climbed by roughly a third of a percentage point since the summer, touching 5.3 per cent at the start of this month before easing back towards 5 per cent, while equities have gone almost nowhere, the S&P 500 having traded in a narrow range since early August. The October flash surveys, meanwhile, left little doubt that the global expansion is still intact, though factories are now doing more of the work than at any point in the past two years (chart 1). Activity data have been beating expectations by more than prices have, and world equities have broadly moved with that gap (chart 2), yet bond markets have drawn a different inference from the same run of numbers, pushing yields and financing costs higher as the surprises accumulated (chart 3). The composition of the demand behind those numbers is where the discomfort lies. Real household incomes are barely growing in the United States and the euro area and are falling outright in Britain and Japan (chart 4), while American consumption leans to an unusual degree on a stock of household wealth that sits far above its historical relationship with income (chart 5). Forecasters have marked up next year's growth almost exclusively where semiconductors are made (chart 6). The expansion is real. The question for policymakers is how much weight it can bear.

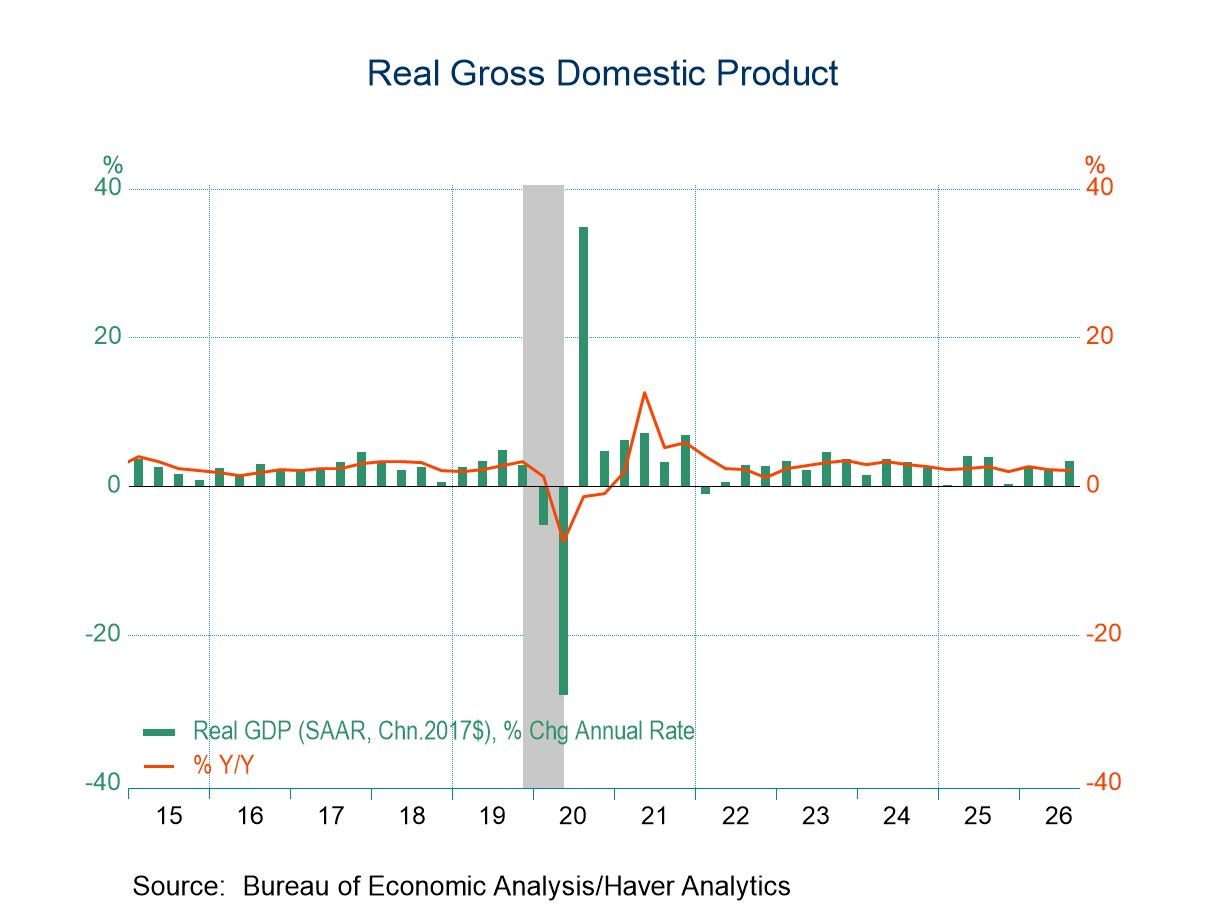
    • The quarterly gain was led by personal consumption, business spending on equipment, and inventory rebuilding.
    • Net exports subtracted 3.3%-points from overall growth, the third largest quarterly drag in the history of the series.
    • Domestic demand growth accelerated to well above trend.
    • Reflecting the retreat in energy prices in Q3, GDP inflation decelerated markedly.
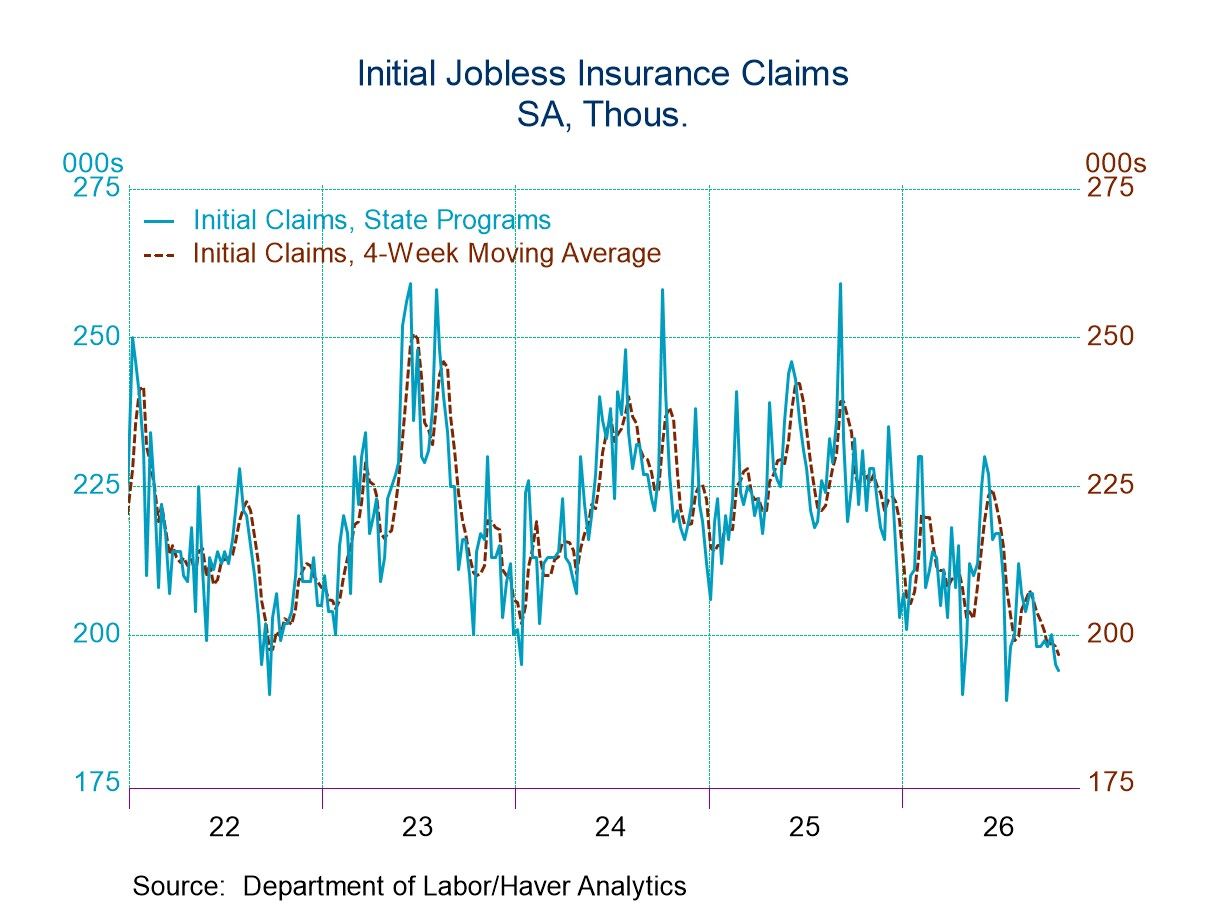
    • New claims declined by 1,000 to 194,000 in the week of October 24.
    • Continuing claims fell by 21,000 to 1.701 million in the week ending October 17.
    • The insured unemployment rate was unchanged at 1.1% in the week of October 17.
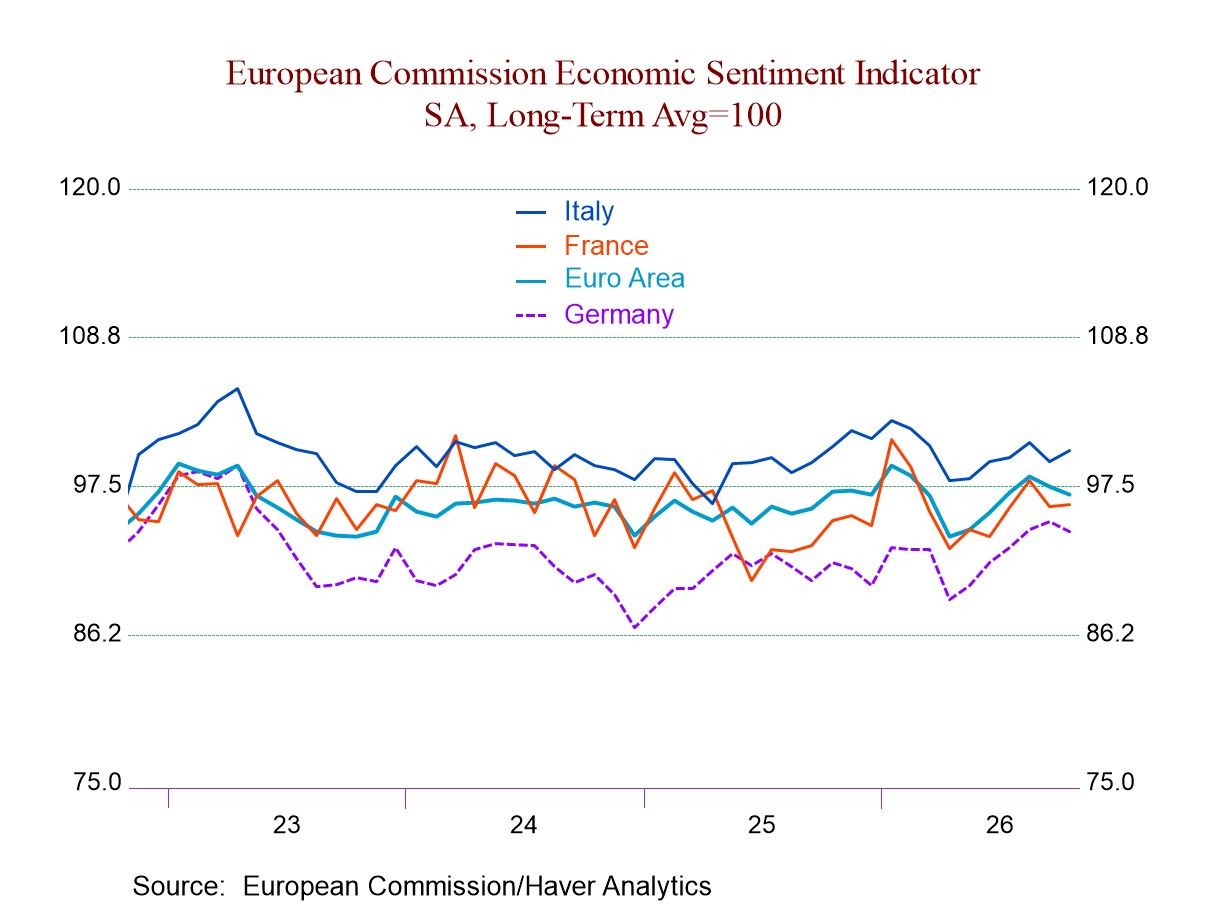
  • The EU index for the European Monetary Union (EMU) fell to 96.9 in October from 97.5 in September. The index was last lower in June of this year, so this is a multi-month low.

    The main sector indexes showed a monthly improvement in only one, the industrial sector, with a rise of one point. Weakening on the month were the construction sector, retail sector, consumer confidence, and the services sector. Each of them slipped by about one point.

    Across reporters, eleven of the 16 countries that are early reporting show month-to-month declines. There were monthly increases in France and Italy as well as among the smaller economies Austria, Belgium, and Slovakia. Nine countries had shown monthly declines in September and only seven had logged weakening in August; still, that’s seven out of sixteen.

    EMU-wide sectors By sector, only two of the five sectors have rankings in their queue standings of historic data above their respective medians. Those two are the industrial sector (58.0%) and construction (57.7%). Below-median rankings were turned in by retailing (43.9%), services (38.5%), and consumer confidence (13.0%). Consumer confidence globally appears much weaker than the sector you might expect to see it affect, like retailing, wholesaling, or services. Consumers keep worrying but keep spending. Still, the overall ranking for the EMU index is at its 37th percentile. That overall ranking is lower than the unweighted simple average of the five-sector ranking (at 42.2%).

    Across countries, the rankings show only five of 16 reporting countries with rankings above the 50% mark, a ranking that would place them above their respective historic medians.