

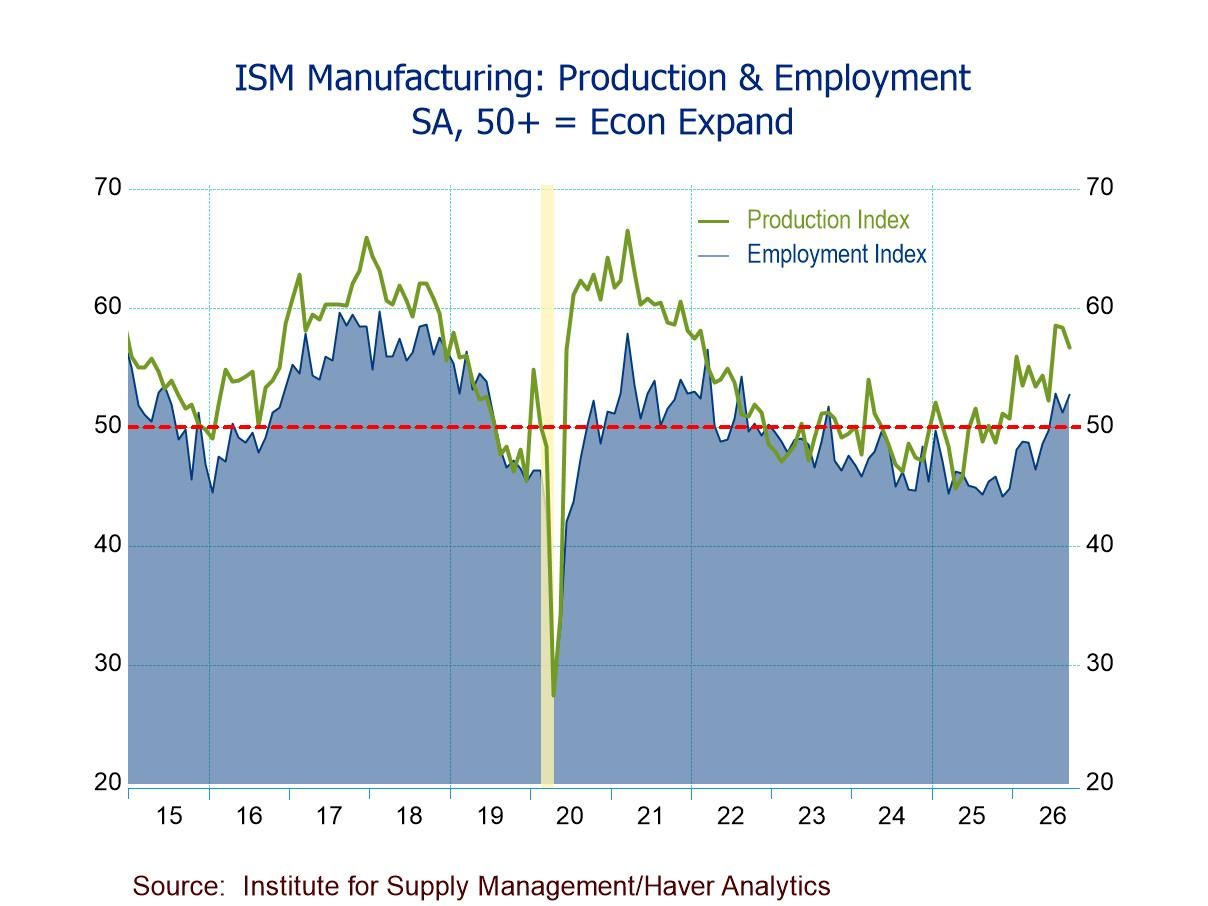
- ISM Mfg. PMI down slightly to 54.5 in Sept.; ninth straight month of expansion.
- Production (56.7) lowest since June; still expanding for the 11th consecutive mth.
- New orders (55.3) growing at a faster pace; ninth successive mth. above 50.
- Employment (52.7) expanding for the third straight mth., at a faster rate, after 33 mths. of contraction.
- Prices Index (77.9) highest since May, indicating prices rising for 24 mths. running.
- Exports (50.9) lowest since June and imports (51.0) lowest since April; both still expanding.
Introducing
Winnie Tapasanun
in:Our Authors
Winnie Tapasanun has been working for Haver Analytics since 2013. She has 20+ years of working in the financial services industry. As Vice President and Economic Analyst at Globicus International, Inc., a New York-based company specializing in macroeconomics and financial markets, Winnie oversaw the company’s business operations, managed financial and economic data, and wrote daily reports on macroeconomics and financial markets. Prior to working at Globicus, she was Investment Promotion Officer at the New York Office of the Thailand Board of Investment (BOI) where she wrote monthly reports on the U.S. economic outlook, wrote reports on the outlook of key U.S. industries, and assisted investors on doing business and investment in Thailand. Prior to joining the BOI, she was Adjunct Professor teaching International Political Economy/International Relations at the City College of New York. Prior to her teaching experience at the CCNY, Winnie successfully completed internships at the United Nations. Winnie holds an MA Degree from Long Island University, New York. She also did graduate studies at Columbia University in the City of New York and doctoral requirements at the Graduate Center of the City University of New York. Her areas of specialization are international political economy, macroeconomics, financial markets, political economy, international relations, and business development/business strategy. Her regional specialization includes, but not limited to, Southeast Asia and East Asia. Winnie is bilingual in English and Thai with competency in French. She loves to travel (~30 countries) to better understand each country’s unique economy, fascinating culture and people as well as the global economy as a whole.

Publications by Winnie Tapasanun
 USA| Oct 01 2026
U.S. ISM Manufacturing PMI Still Expansionary in September; New Orders & Employment Accelerating; Production Moderating
 USA| Sep 30 2026
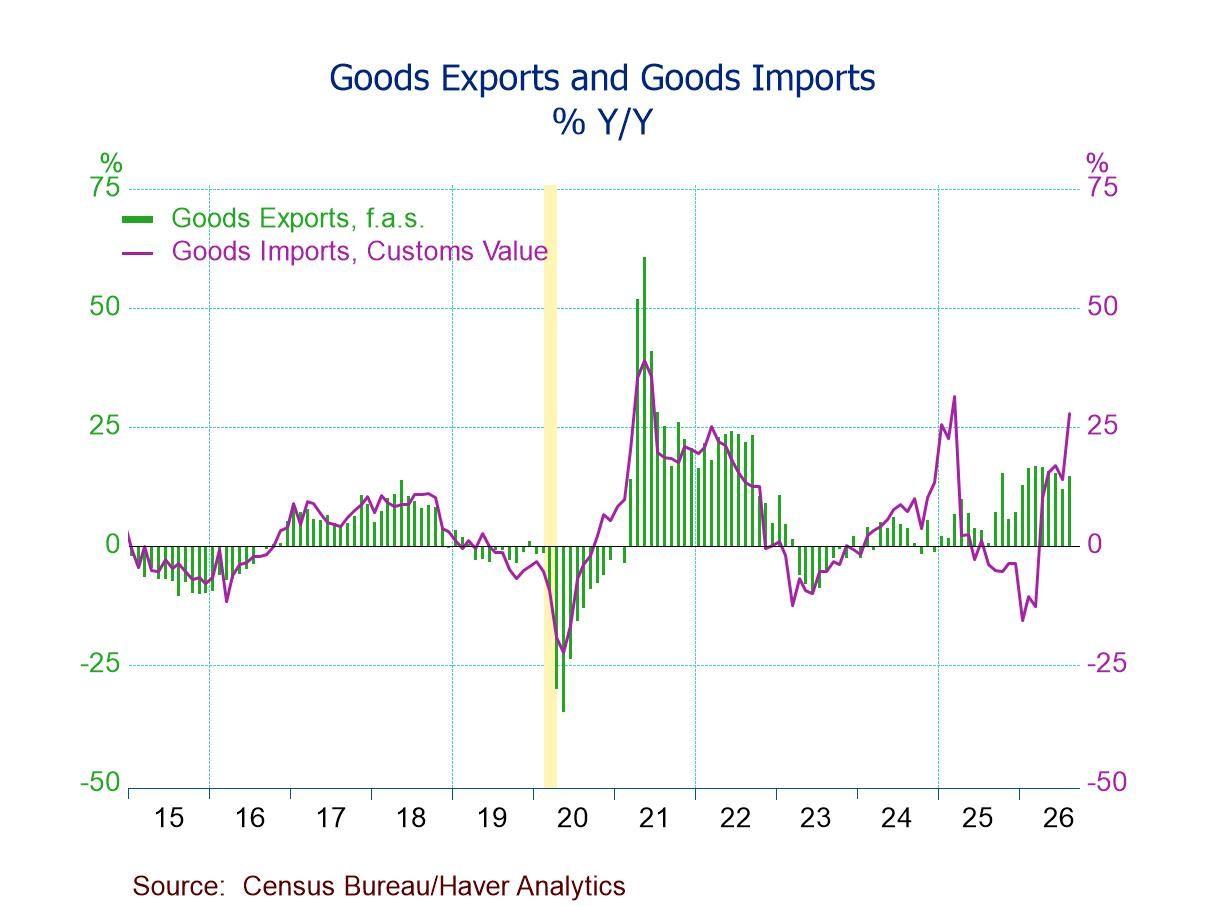
U.S. Goods Trade Deficit Balloons Further in August
- Deficit: $132.6 bil. in August, up $13.7 bil. (+11.5%) from July’s $118.9 bil., pointing to a significant drag on Q3’26 GDP growth.
- Exports +1.9%, first m/m gain since April, driven by an 8.3% rebound in industrial supplies & materials exports; nonauto consumer goods exports down 10.5%.
- Imports +5.5%, sixth rise in seven mths. to highest level since Mar. ’25, with m/m increases in all end-use categories except nonauto consumer goods imports (-1.6%).
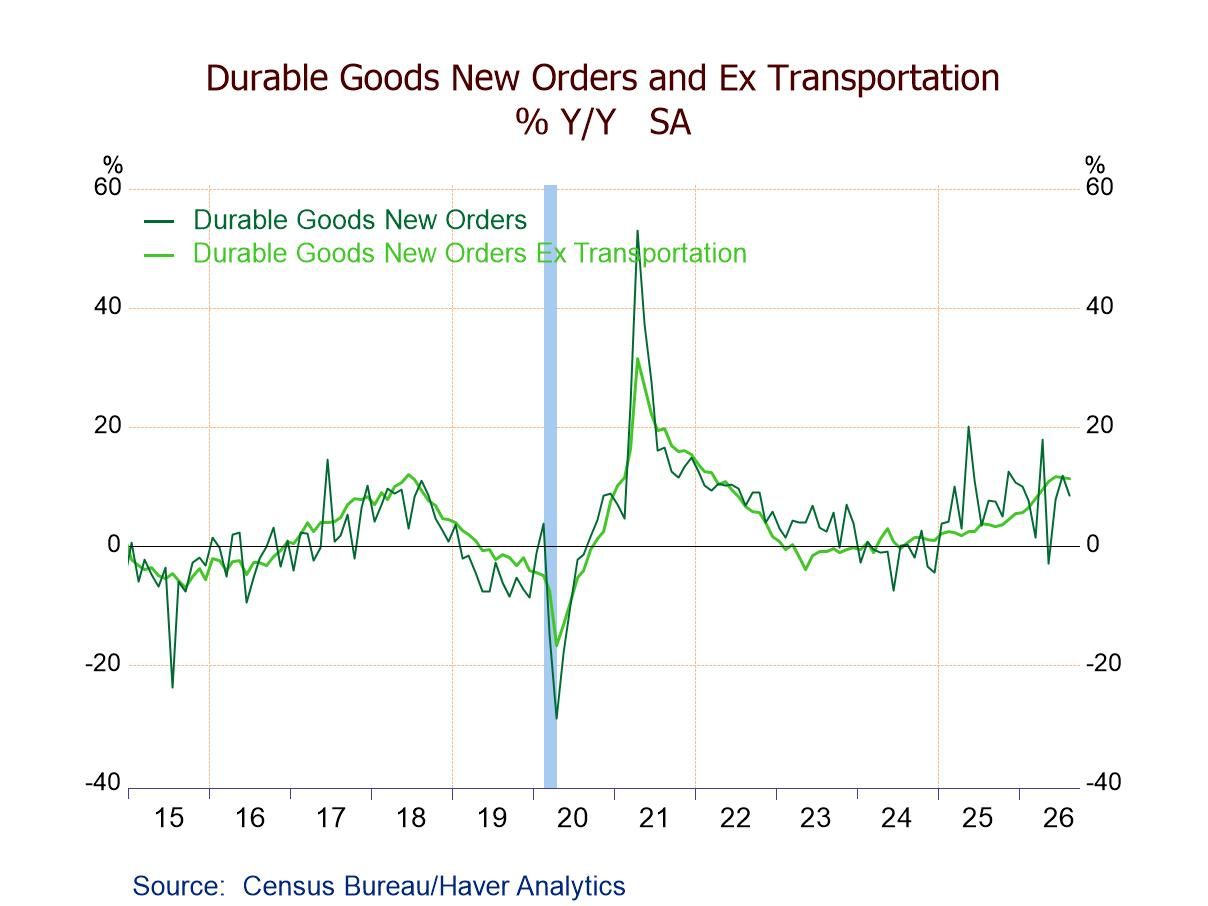
- August headline orders unchanged after two straight m/m rises; +8.5% y/y, positive since Jan. ’25 except for May; still up 21.3% from a Nov. ’22 low.
- Nondefense aircraft & parts -4.3% m/m vs. July’s +12.0%.
- Transportation orders -0.6%, third fall in four months; orders ex transp. +0.3%, 16th consecutive m/m increase.
- Core capital goods shipments +0.6%, 11th gain in 12 mths., pointing to a solid contribution to Q3’26 GDP from business equipt. spending.
- Durable goods shipments -0.2% (+8.6% y/y); unfilled orders +0.6% (+8.8% y/y); inventories +0.5% (+3.0% y/y).
 USA| Sep 24 2026
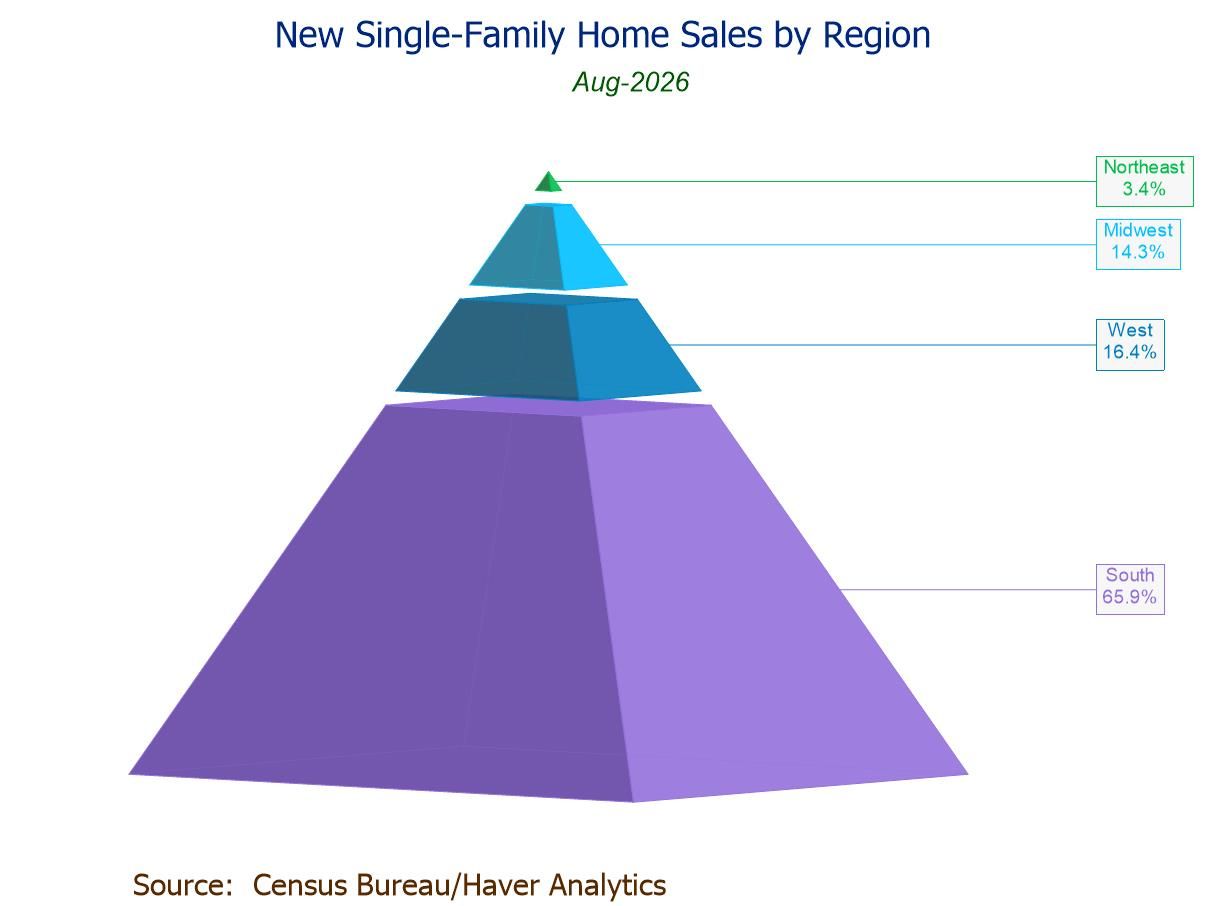
U.S. New Home Sales Rebound to an Eight-Month High in August
- Sales +6.4% m/m (-2.0% y/y) to 684,000 in Aug.; up 27.9% from a July ’22 low.
- Sales m/m up in the Midwest (+84.9%) and South (+6.9%); down in the Northeast (-36.1%) and West (-15.2%).
- Median sales price +0.4% m/m to $393,700, first rise since Apr.; avg. price -9.1% m/m to $478,700, a two-year low.
- Unsold inventory unchanged (-2.0% y/y) at 483,000; months' supply down to 8.5 mths., lowest since Dec. ’25.
 USA| Sep 21 2026
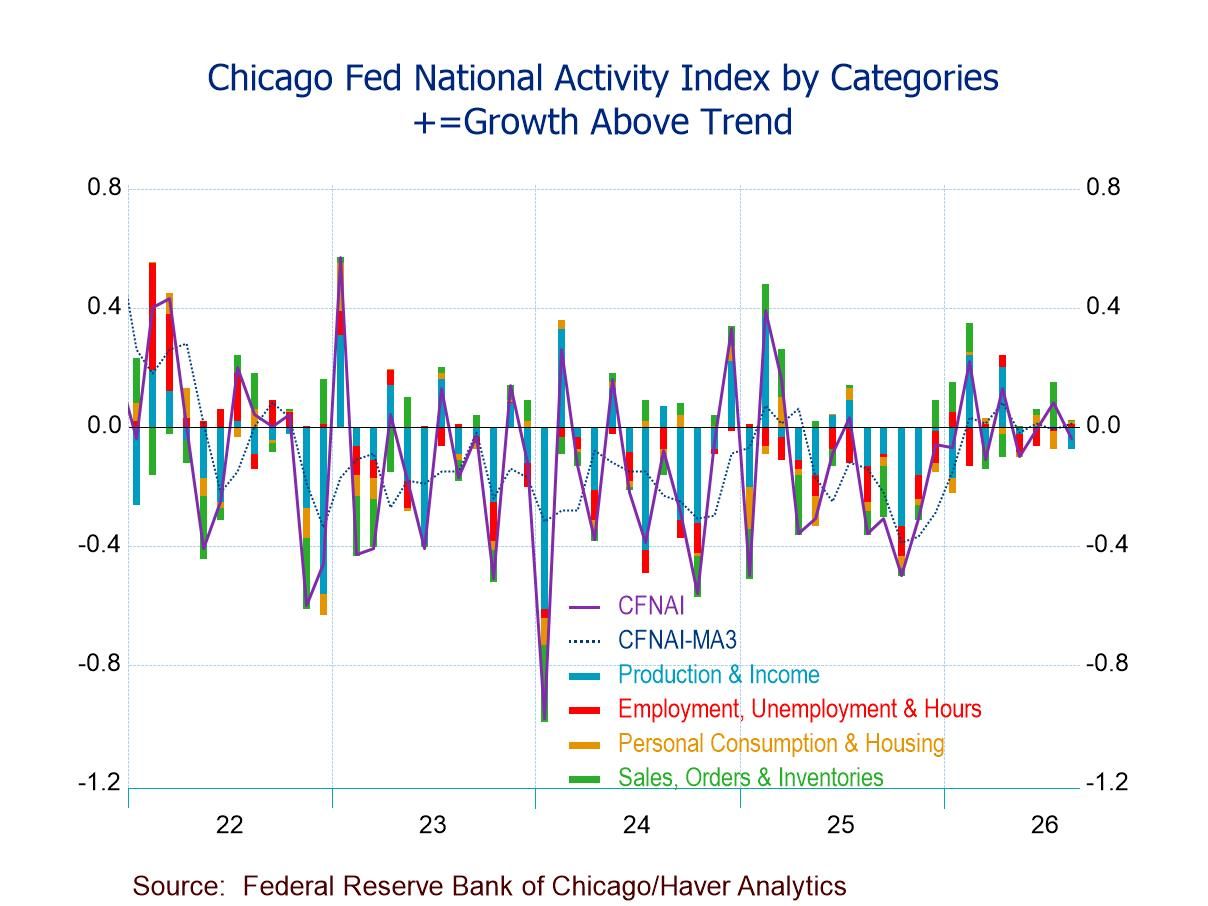
Chicago Fed National Activity Index Negative in August After July’s Upwardly Revised Positive Level
- CFNAI down to -0.04 in Aug., negative for the third time in four mths.
- Two of four CFNAI components down m/m; one makes a negative contribution.
- CFNAI-MA3 up to +0.01, second positive reading in three mths.; above -0.70 (recession signal).
- CFNAI Diffusion Index down to +0.02, still positive for the sixth straight mth.
 USA| Sep 18 2026
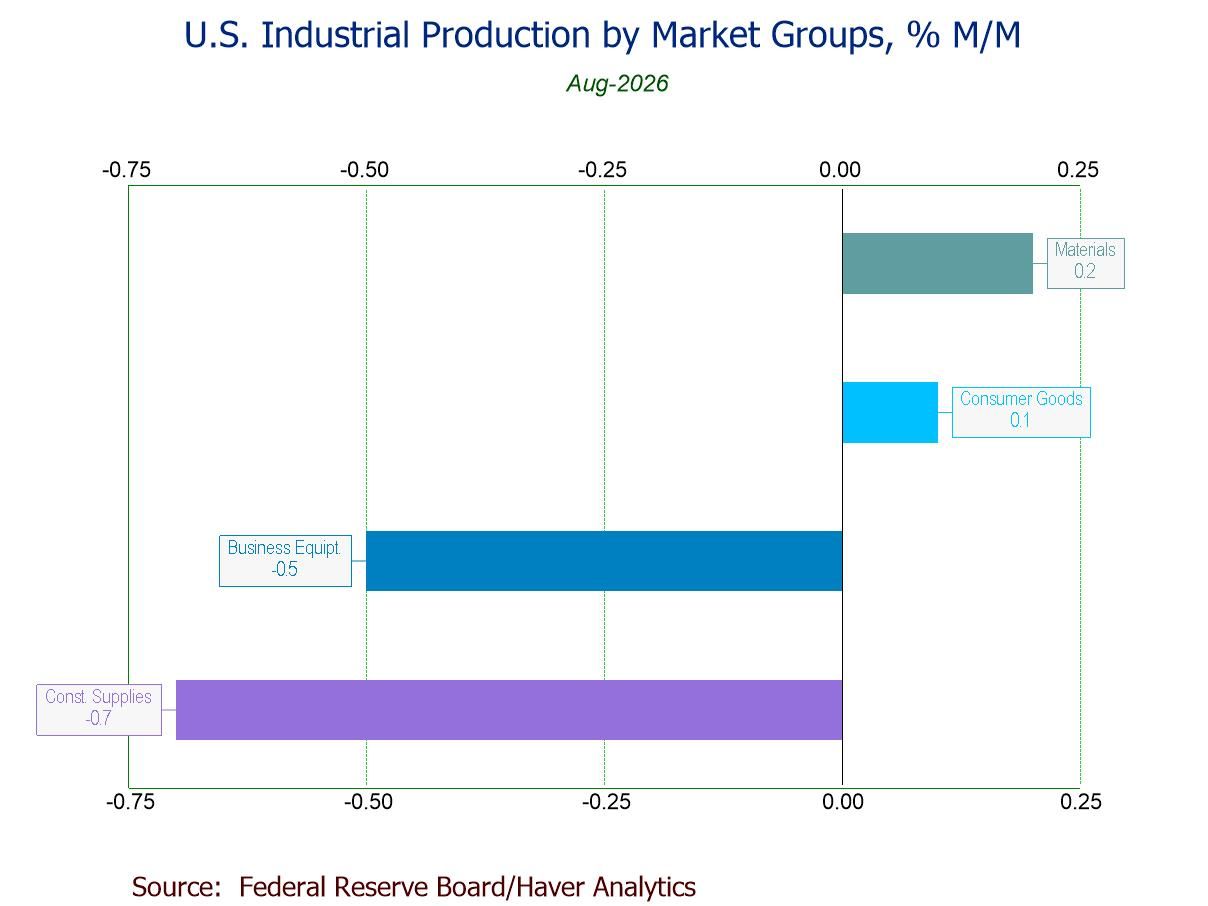
U.S. Industrial Production Flat in August; Manufacturing IP Down
- August IP 0.0% (+1.4% y/y) after four consecutive m/m increases, remaining on an upward trend.
- Manufacturing -0.3% (+0.9% y/y), first m/m decline since Dec., w/ durables -0.5% and nondurables 0.0%.
- Selected high-tech 0.0% after four straight m/m rises; motor vehicles -1.2%, second successive m/m drop.
- Utilities +1.8% (+6.2% y/y), fourth rise in five mths., led by a 2.1% gain in electric utilities output.
- Mining +0.1% (+0.3% y/y), up for the fourth time in five mths.
- Key categories in market groups post mixed results.
- Capacity utilization steady at 76.3%, highest since July ’25; mfg. capacity utilization down to 75.7%, lowest since March.
 USA| Sep 16 2026
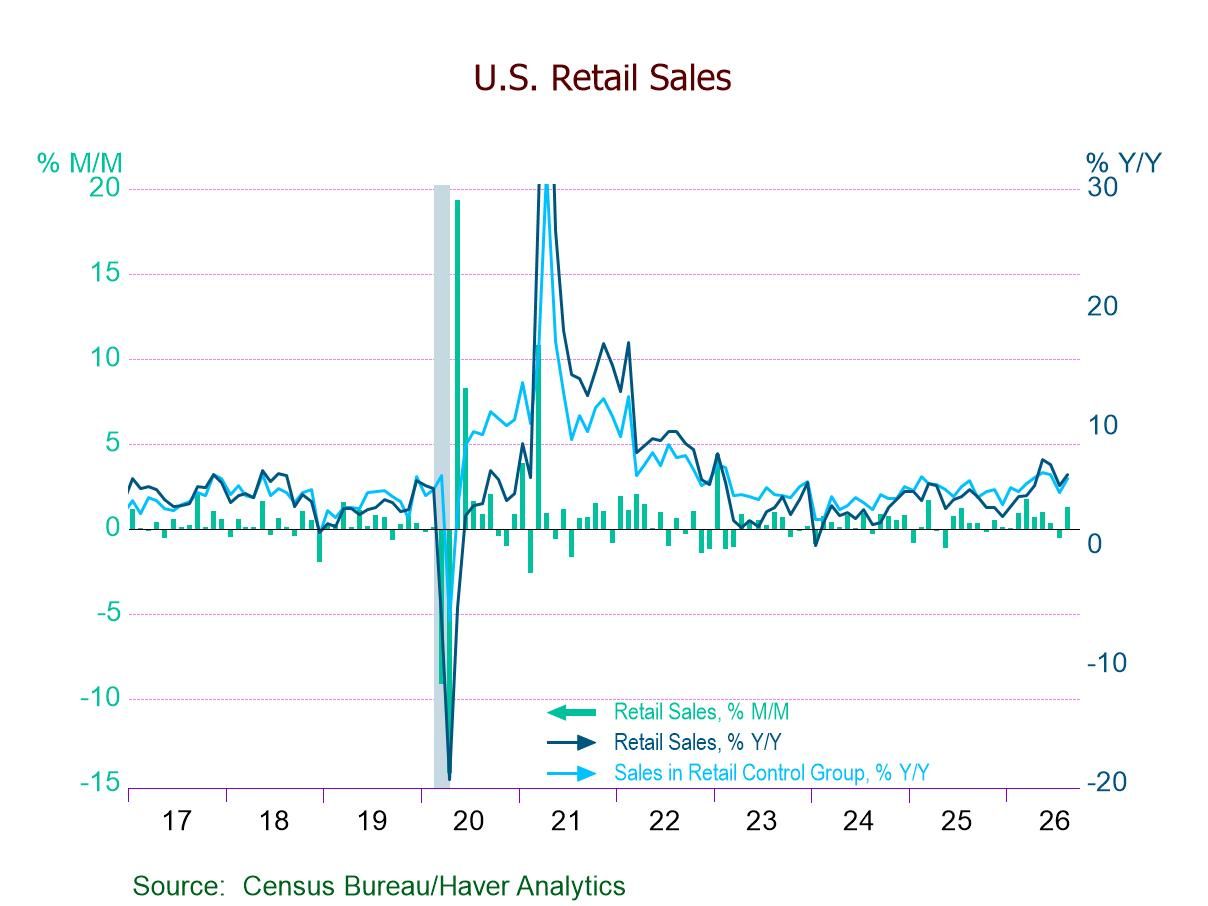
U.S. Retail Sales Rebound in August, Exceeding Forecasts
- Total retail sales +1.2% (+6.0% y/y) in August; sixth m/m increase in seven mths.
- Ex-auto sales +1.4% (+6.9% y/y), first m/m rise since May; auto sales +0.6% (+2.1% y/y), third rise in four mths.
- Ex-gas sales +1.1% (+4.9% y/y) and ex-auto & gas sales +1.2% (+5.6% y/y); both up m/m from Jan. through Aug. except July.
- Retail control group +1.4% (+5.6% y/y), seventh m/m gain in eight mths., pointing to solid underlying consumer demand in Q3 ’26.
- Gains m/m: gasoline stations (+3.1%), nonstore sales (+2.6%), misc. stores (+1.9%), electronics stores (+1.6%).
- Declines m/m: department stores (-0.8%), building materials & garden equipt. stores (-0.2%).
 USA| Sep 15 2026
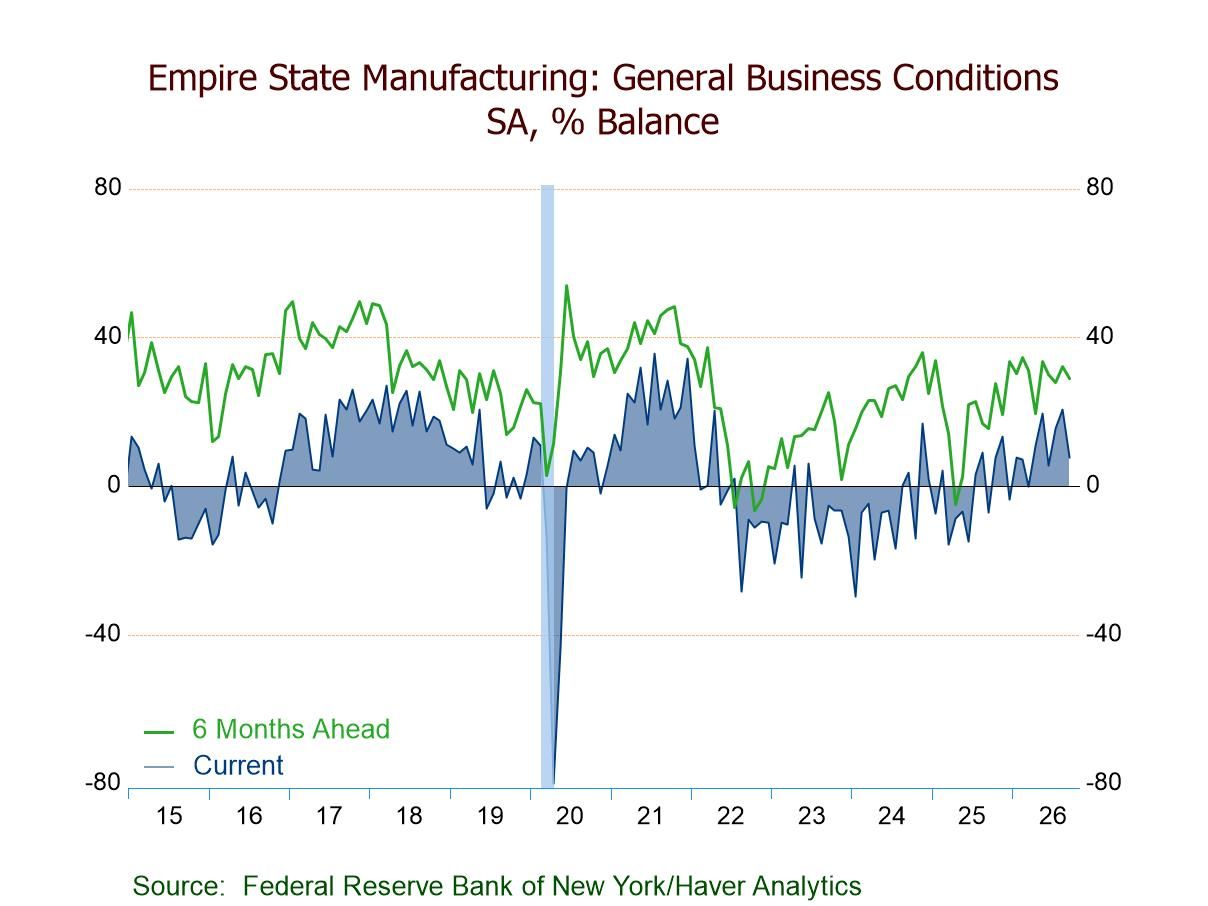
U.S. Empire State Manufacturing Index Cools Sharply in September
- General Business Conditions Index down 13.0 pts. to 7.6 in Sept.; sixth straight expansion.
- New orders (2.0), down 15.3 pts.; weakest level since Dec. ’25, still indicating expansion.
- Shipments (-3.2), down 14.9 pts.; first negative reading since March.
- Unfilled orders (5.9), down 9.6 pts. but staying positive; inventories (8.9), highest since May.
- Employment (10.6), up 1.3 pts.; eighth consecutive expansion.
- Prices paid (63.1), highest since July '22; prices received (28.1), a three-month high.
- Firms still optimistic: Future Business Conditions Index down to a still-expansionary 29.0; future prices paid rising to 67.3, highest since June ’22.
 USA| Sep 11 2026
U.S. Consumer Price Inflation Steady in August at 3.4% Y/Y
- Monthly gains in headline CPI (0.4%) & core CPI (0.3%) advance.
- Year-over-year rates unchanged for headline CPI (3.4%) and slightly down for core CPI (2.4%), both remaining above the Fed’s target.
- Energy prices up 2.1% m/m, w/ the y/y rate accelerating to 16.3%, highest since May.
- Services prices up 0.3% m/m, w/ the y/y rate steady at 3.0%.
- Shelter prices up 0.3% m/m, w/ the y/y rate easing to 3.0% from 3.2%.
- Supercore CPI up 0.5%, w/ the y/y rate accelerating to 3.0% from 2.8%.
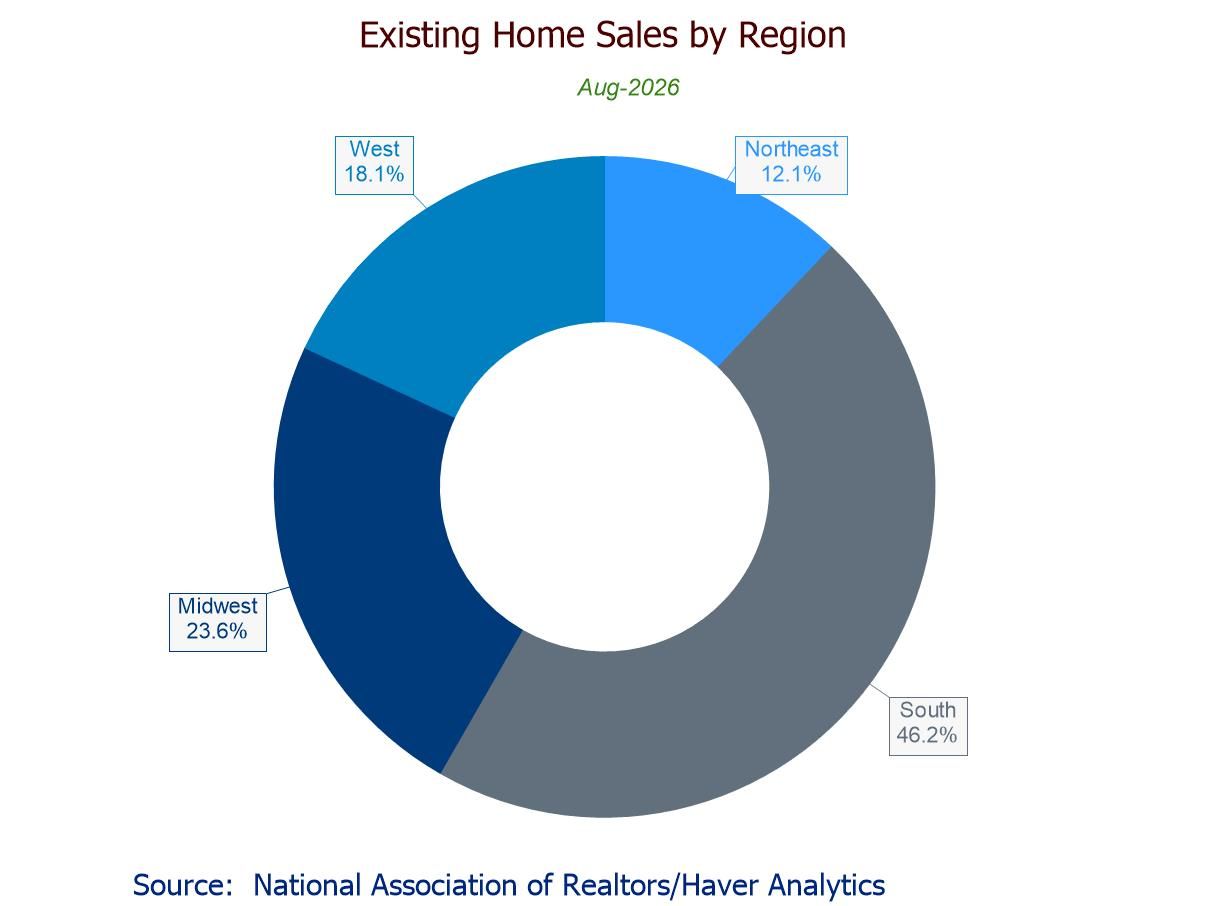
- August sales -2.0% m/m to 3.98 mil., third straight m/m fall; -1.2% y/y, first y/y drop since March.
- Sales m/m down in the Northeast (-4.0%), Midwest (-3.1%), and South (-1.6%); flat in the West.
- Sales y/y down in three regions; unchanged in the South.
- Median sales price -1.7% (+1.6% y/y) to $429,100, a four-month low.
- Unsold inventory +3.2% (+5.9% y/y) to 1.62 mil. units, highest level since Nov. ’19; 4.9 months' supply, highest since Nov. ’15.
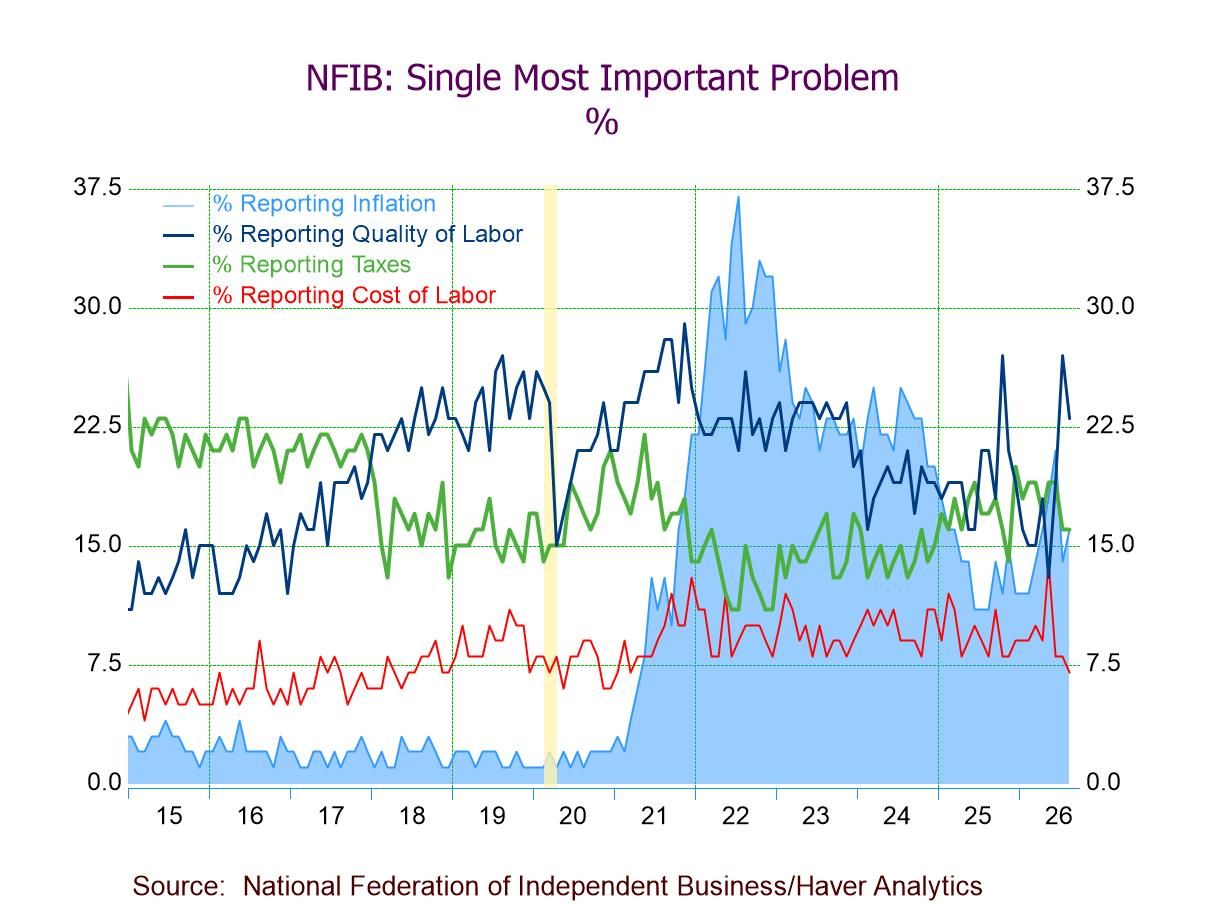
- NFIB Small Business Optimism Idx down 1.1 pts. to 98.7 in Aug., still above its 52-year avg. of 98.0.
- Uncertainty Idx down 2 pts. to 89, remaining above the historical avg. of 68.
- Expectations for economy down 5 pts. to 10%, lowest since May.
- Hiring plans down 3 pts. to 17%; earnings trends down 3 pts. to -19%.
- Expected real sales down 1 pt. to 6%, a three-month low.
- Plans to expand business unchanged at 12%, highest since Feb.
- Firms raising avg. selling prices steady at 31%, lowest since April.
- Top three business concerns: labor quality (23%), taxes (16%), and inflation (16%).
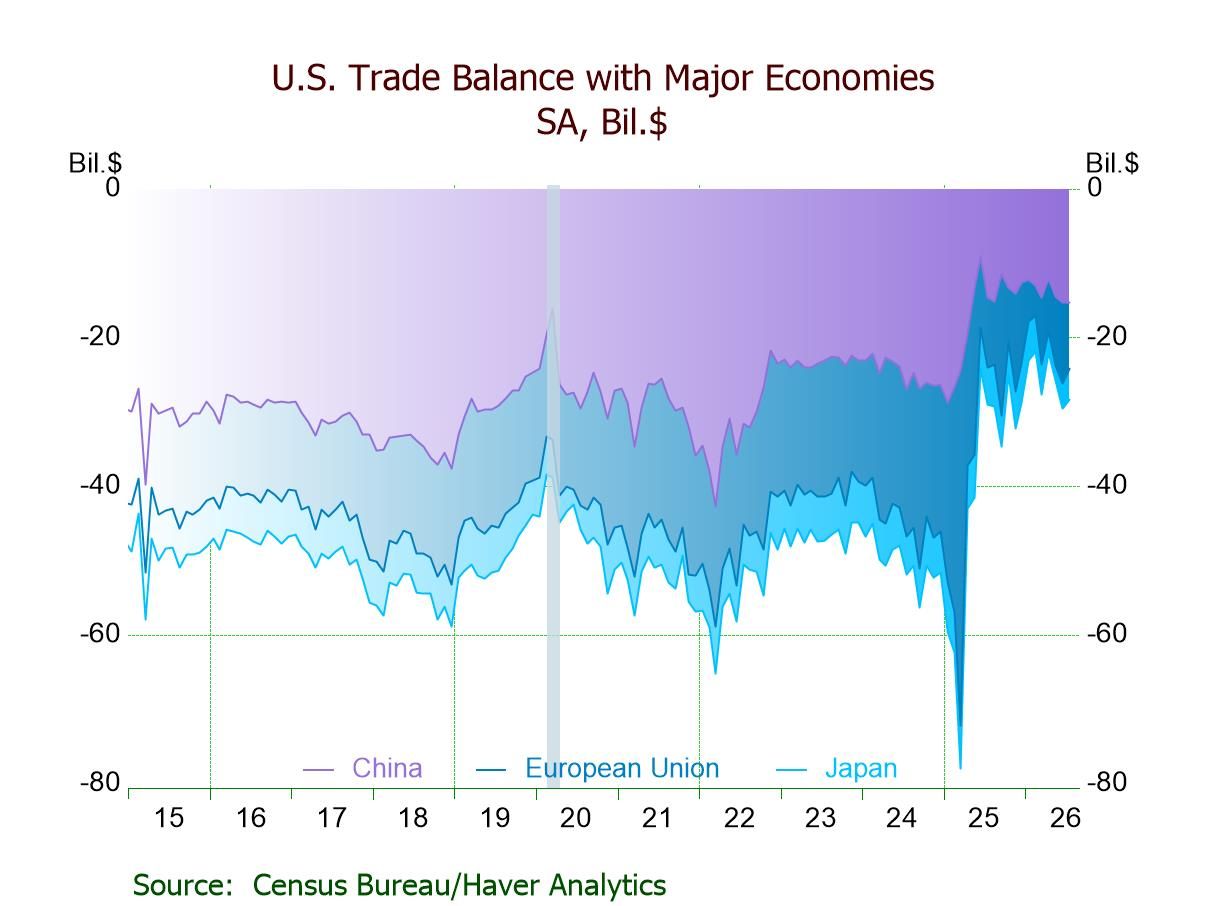
- Deficit: $88.6 bil. in July, up from $71.2 bil. in June, reflecting $119.6 bil. goods deficit & $31.0 bil. services surplus.
- Exports -2.1%, third straight m/m decline, driven by a plunge in nonmonetary gold exports.
- Imports +2.8%, fifth m/m increase in six months, boosted by a rise in capital goods imports.
- Real goods trade deficit widens to $106.4 bil., largest since Mar. ’25.
- Goods trade deficits w/ China down to a still-high $15.2 bil., w/ EU down to a 3-month low, and w/ Japan up to a 5-month high.
- of16Go to 1 page