Haver Analytics
Haver Analytics

Economy in Brief: August 2026

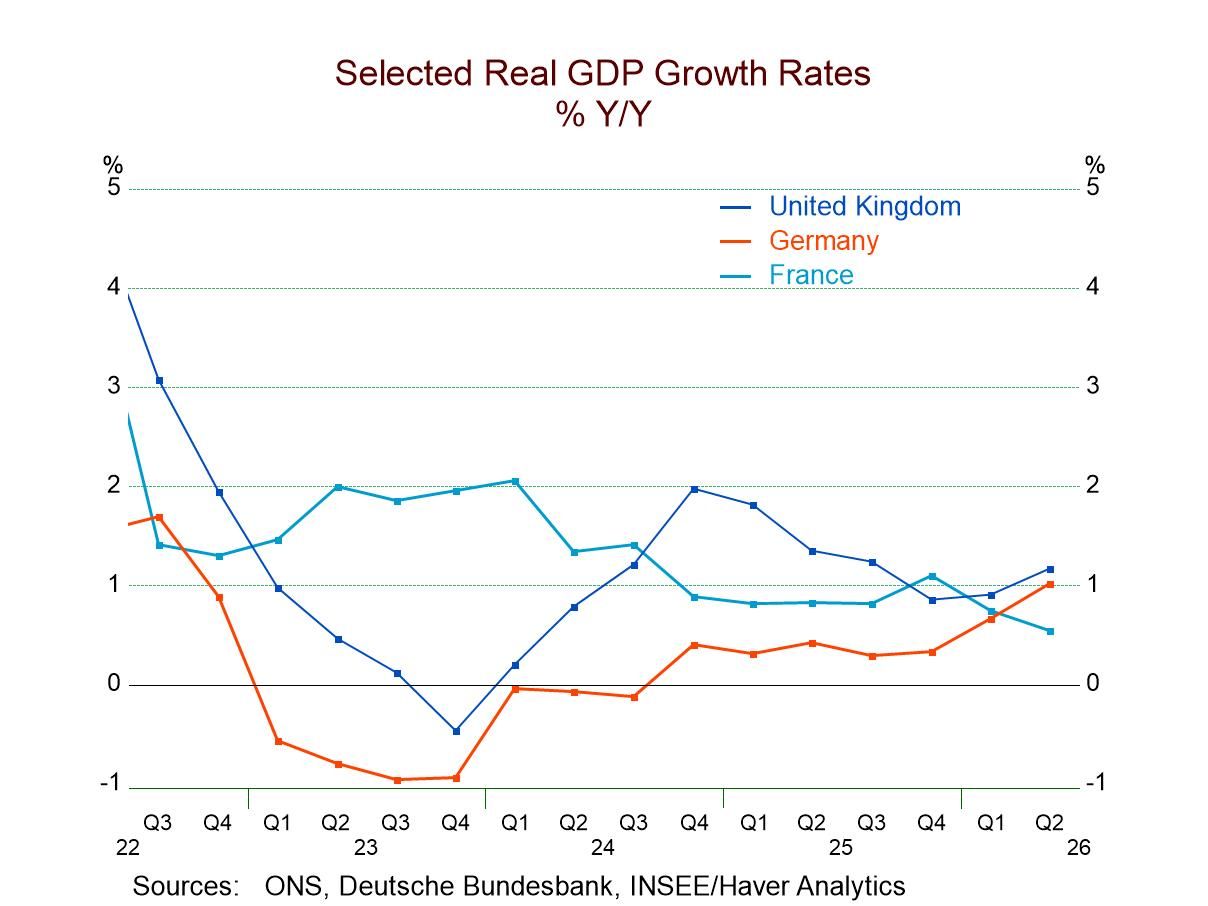
  • Growth among the eleven reporting EMU countries continues to be mixed. Growth in EMU is stable enough but modest at 0.5% to 1.2% over four quarters when assessed over the last four quarters. Quarterly results are more volatile, of course. Median annual growth is 1.3% to 2.1%.

    Mixed Result on Growth In Q2, five of these eleven countries showed lower growth based on annualized quarter changes, while three showed weaker growth quarter-to-quarter based on four-quarter rates of growth. Belgium, Denmark, and France were weaker based on four-quarter growth rates. Growth in Spain was unchanged at 2.7%. Danish growth slowed to 4.6% from 6.1%.

    Assessing Rates of Growth The change in growth rate assessment is useful but never quite definitive, as you can see from the still-strong, although slower, Danish pace of growth. 4.6% is less than 6.1%, but it is still quite strong, hardly a problem. Similarly, Ireland shows better growth, but that is an ‘improvement’ to -5.6% from -13.2%, an improvement and a sharp one, but still chillingly weak. Of course, Ireland, with a preponderance of multinational corporations headquartered there, shows some accounting fluctuations that are not that representative of a real macroeconomic impact on the Irish economy but can have a big impact on reported GDP. Ireland logs the only negative growth rate in the monetary union over four quarters, with Belgium the next weakest at 0.5%, and Germany and Italy at 1%.

    The Big Four Economies The four largest EMU countries with GDP pooled have run an annual growth that has been quite steady around the 1% mark (0.9% to 1.1%). The rest of the EMU has had a more volatile growth rate. Pooling the remaining countries’ GDP performance yields growth rates over fourth quarters ranging from -0.9% to +2.1% over the last four quarters.

    Within EMU The table chronicles growth rates for 11 EMU members plus the United Kingdom, the United States, and Japan. Among these 14 countries, year-over-year growth rates on data back to 1998 show only five countries with GDP growth rates ranking over four quarters above 50%; rankings above 50% put them above their median for that period. Those five countries are Spain, Finland, Italy, Portugal, and Denmark. While Spain and Italy have rankings above their medians for the period, German growth ranks at only 45.7%, and French growth is quite weak at a 17.4 percentile standing, marking a split in performance among the Big Four economies.
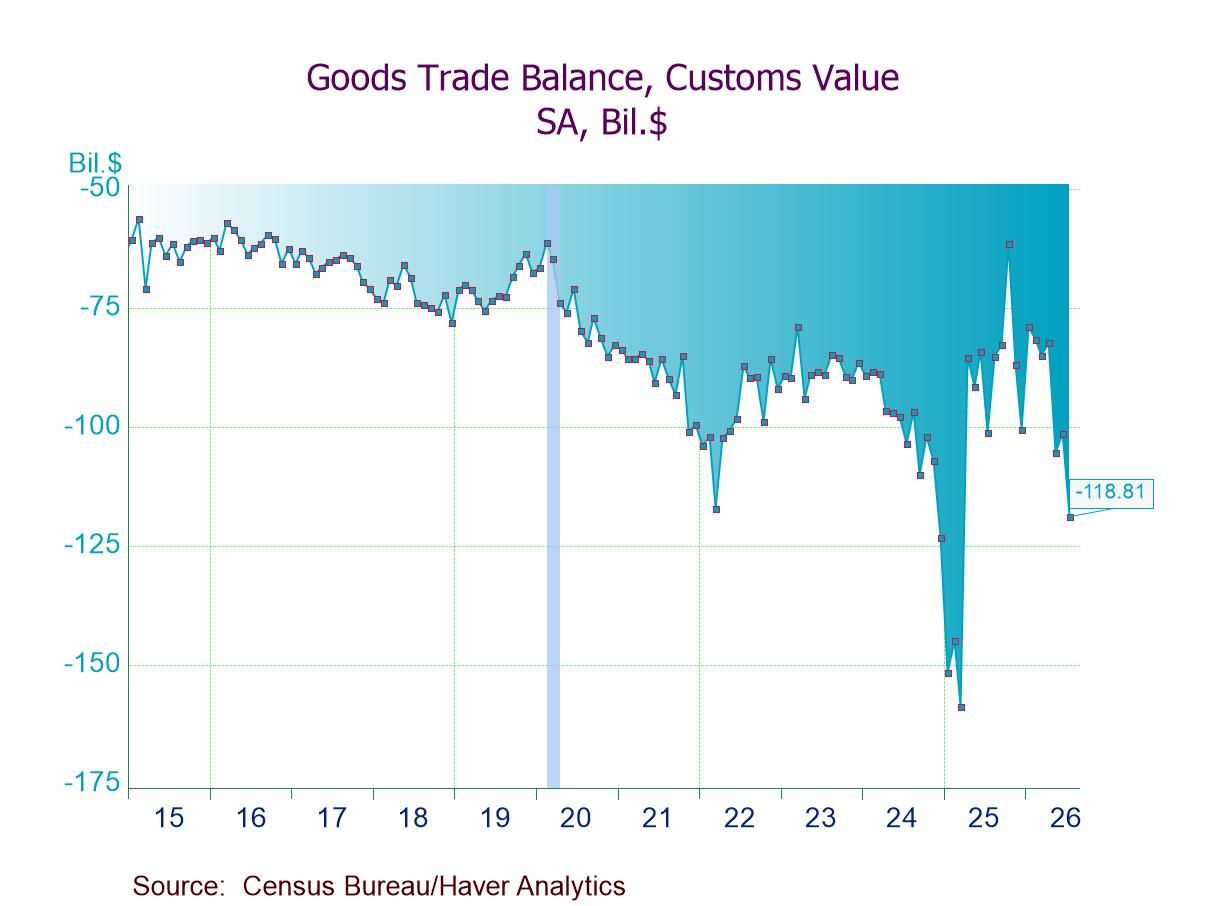
    • Deficit: $118.8 bil. in July, up $17.4 bil. (+17.2%) from June’s $101.4 bil.
    • Exports -2.9%, third straight m/m decline to a six-month low, driven by an 11.2% drop in industrial supplies & materials exports.
    • Imports +3.7%, fifth rise in six mths. to highest level since Mar. ’25, led by an 11.3% rebound in nonauto capital goods imports.
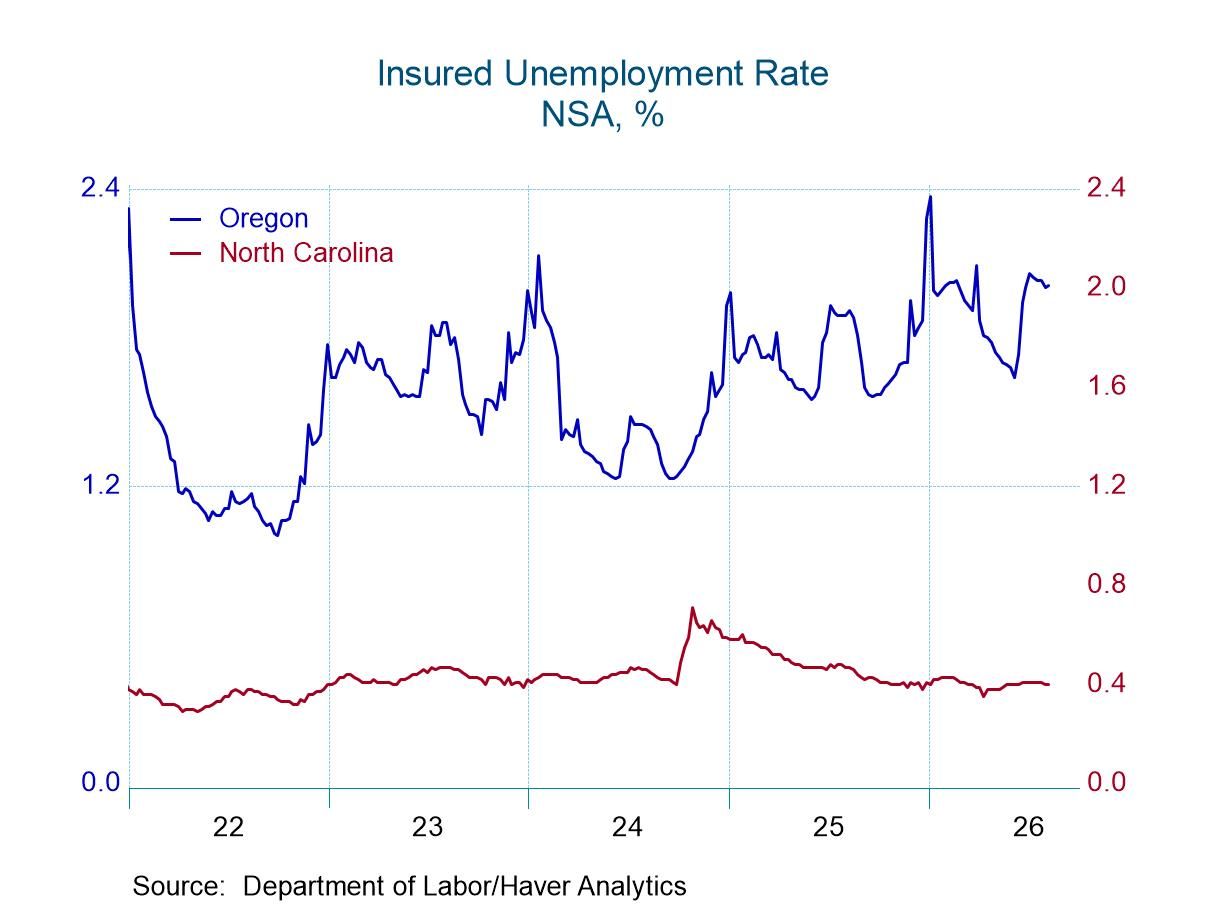
    • New claims declined by 4,000 to 203,000 in the week of August 22.
    • Continuing claims declined by 18,000 to 1.778 million in the week ending August 15.
    • The insured unemployment rate was unchanged at 1.2% in the week of August 15.
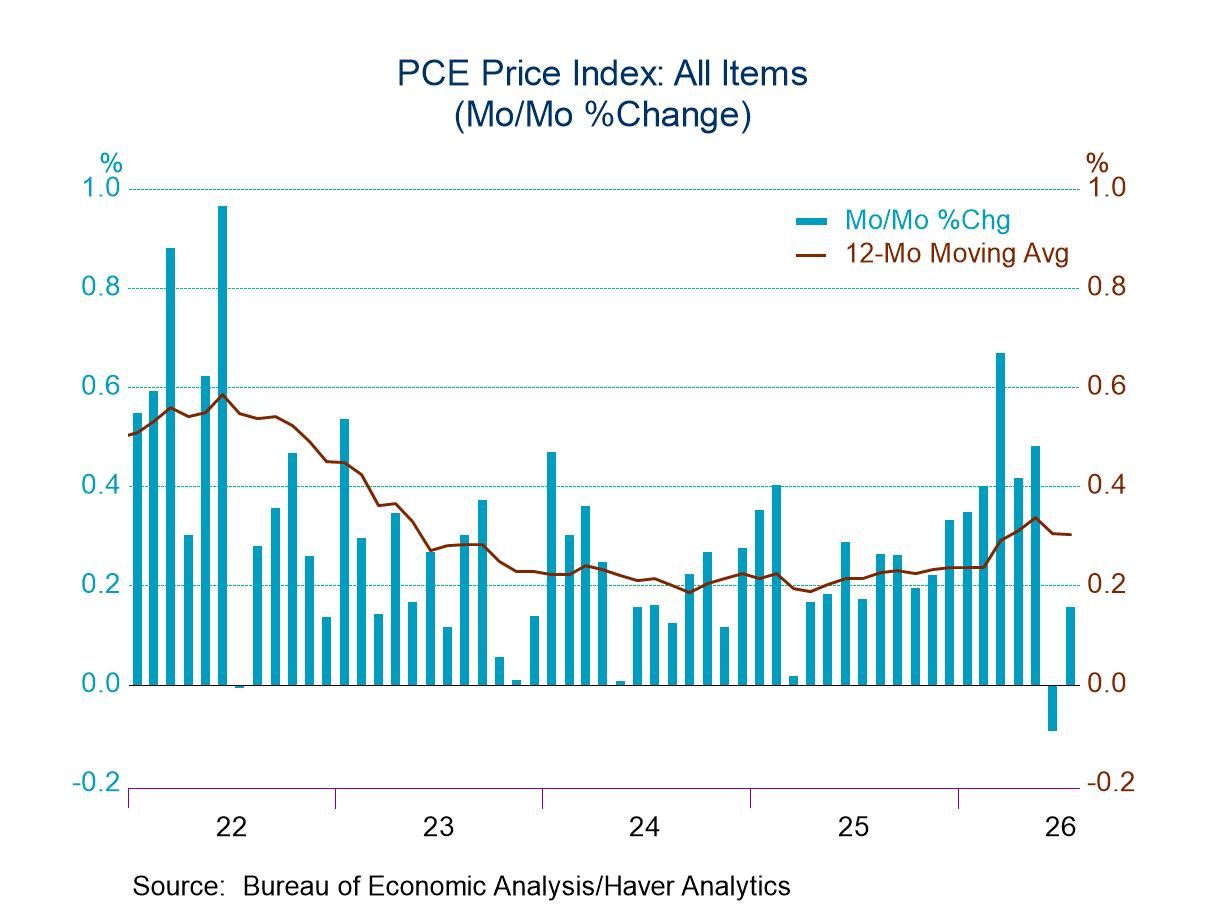
    • Headline and Core PCE price measures cooled in the last two months.
    • Real spending stalled in July.
    • Saving uptick should be viewed as a pause in the downtrend.
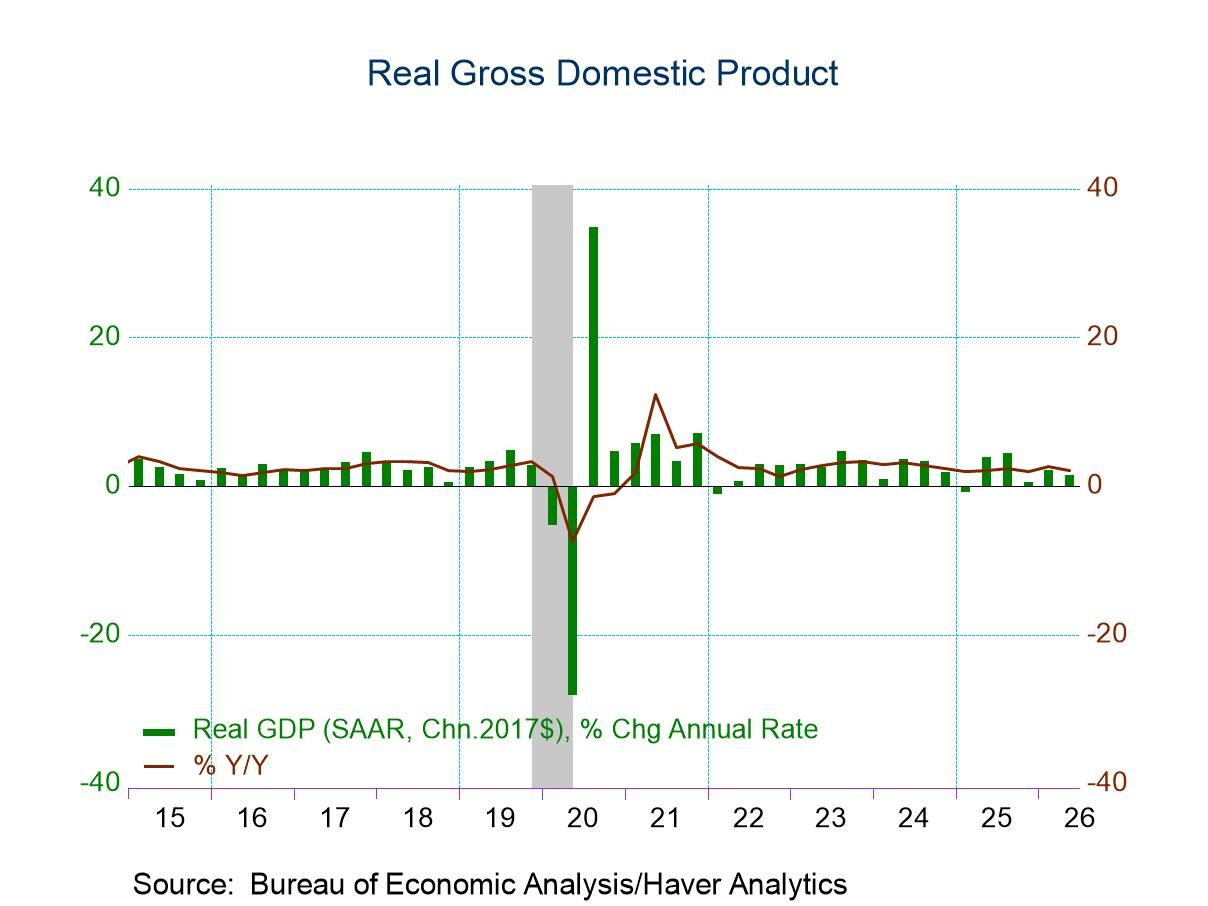
    • The 1.5% q/q saar increase in real GDP reported in the advance report was not revised in the second estimate.
    • Inventory investment and net exports continued to be meaningful drags on overall growth.
    • The strong domestic demand growth reported in the advance report was revised even stronger.
    • Corporate profits surged 9.1% q/q not annualized in Q2, the fastest quarterly advance since Q2 2021.
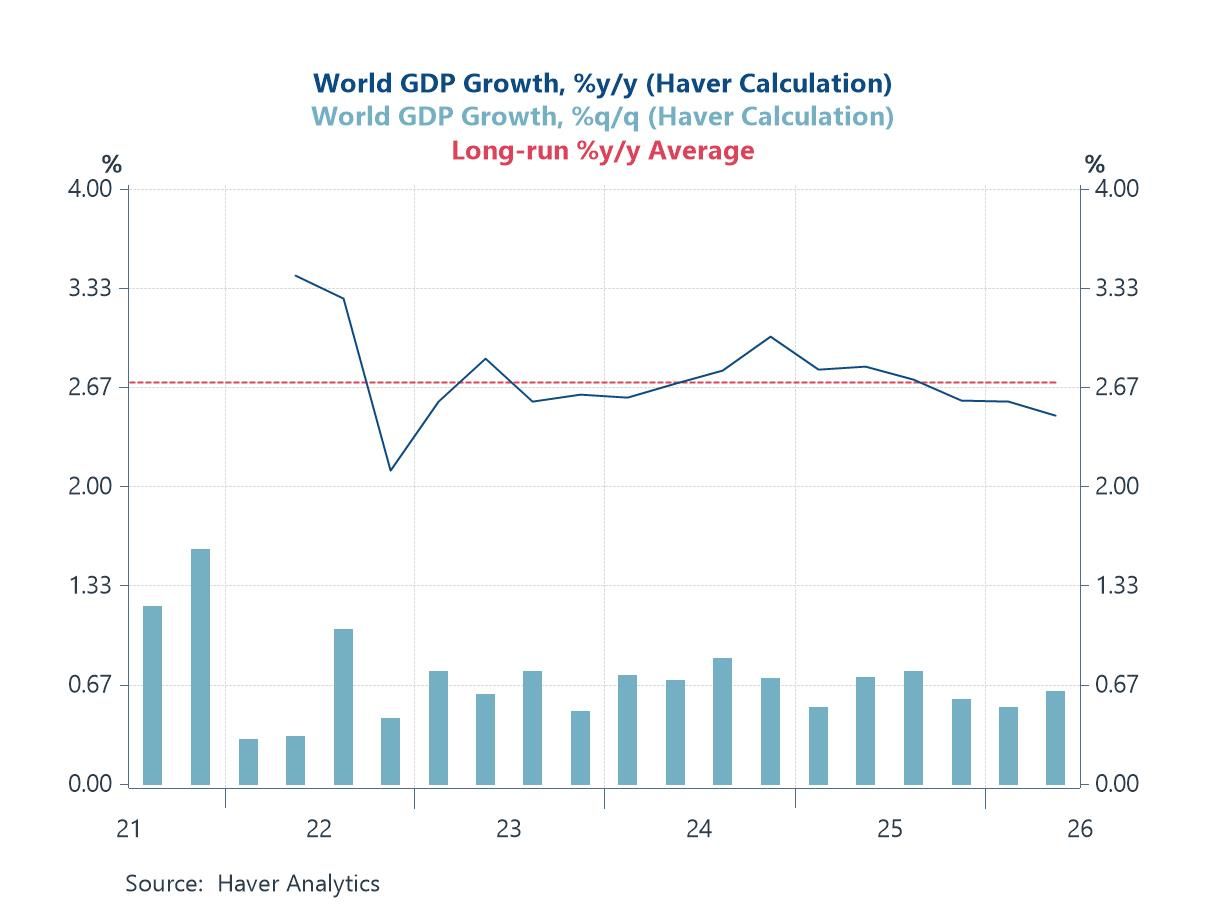
  • A dominant anxiety in financial markets remains the level of long-term interest rates. It is worth beginning, though, with the real economy, where the news of recent days has been more reassuring. Haver’s proprietary calculation of world GDP growth suggests the global economy held up well in the second quarter, expanding at close to its long-run average pace and defying the sharper slowdown many had feared (chart 1). The August flash purchasing managers’ indices tell a similar story, with most of the major economies both in expansion and still improving — though, as ever, the composite readings conceal a more uneven picture beneath (chart 2). From South Korea, whose trade figures are among the world’s most timely, comes the same message, and a pointed one about the artificial-intelligence boom: semiconductor exports have continued to surge (chart 3). Yet the market’s gaze stays fixed on US yields, and a decomposition explains why they are being watched so closely — the rise has come overwhelmingly from the real component, not from any meaningful revival of inflation expectations (chart 4). That, one might argue, is not a passing technical matter but a structural one, rooted in who is willing to fund the US government. The rest of the world now funds a steadily shrinking share of its debt (chart 5), and the surplus nations that once recycled their savings into Treasuries are turning, instead, to gold (chart 6). It is against this backdrop that Treasury Secretary Scott Bessent's recent remarks that the government may intervene in the market to support its debt have drawn attention.

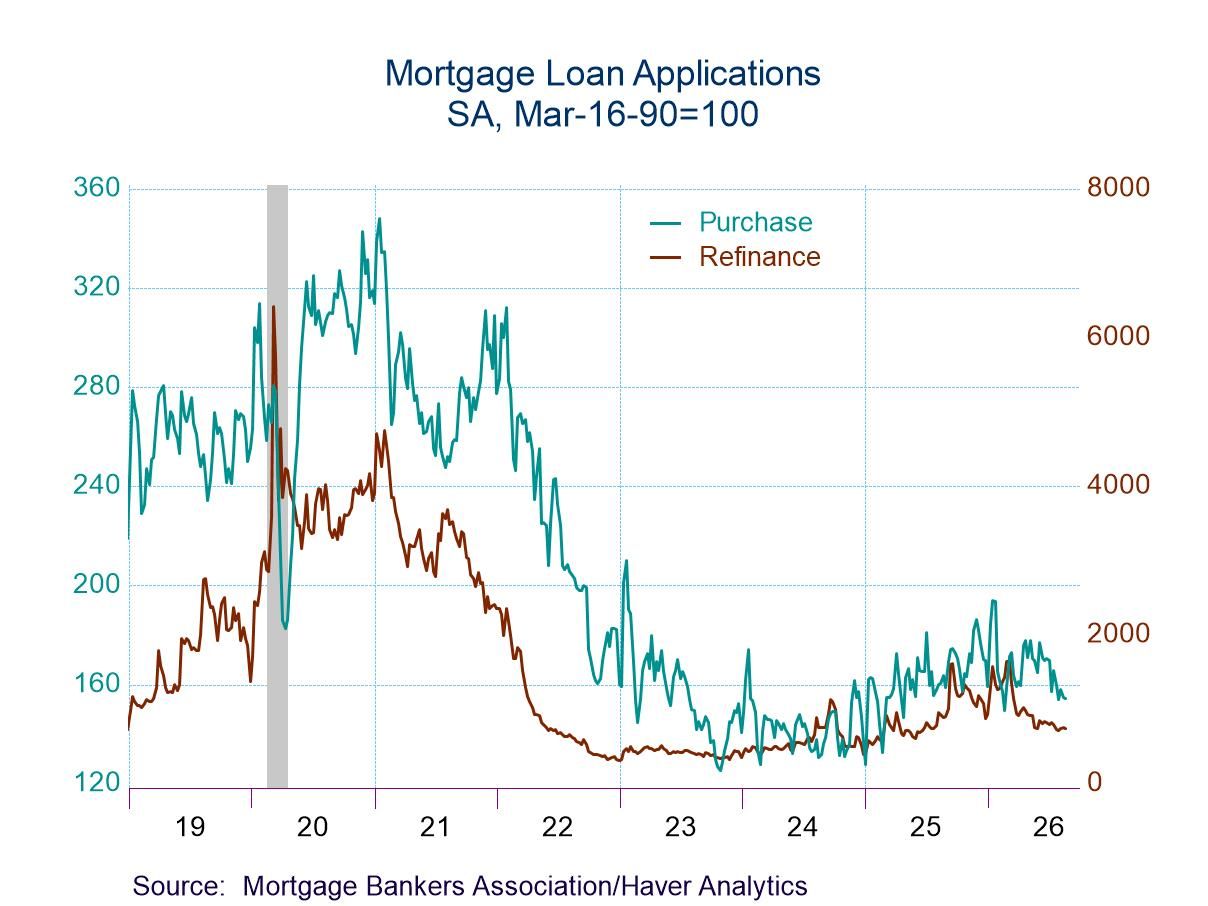
    • Both applications for loans to purchase and for loan refinancing declined in the latest week.
    • Interest rate on 30-year fixed-rate loans edged up 1bp to 6.97%.
    • Average loan size inched up in the August 21 week.
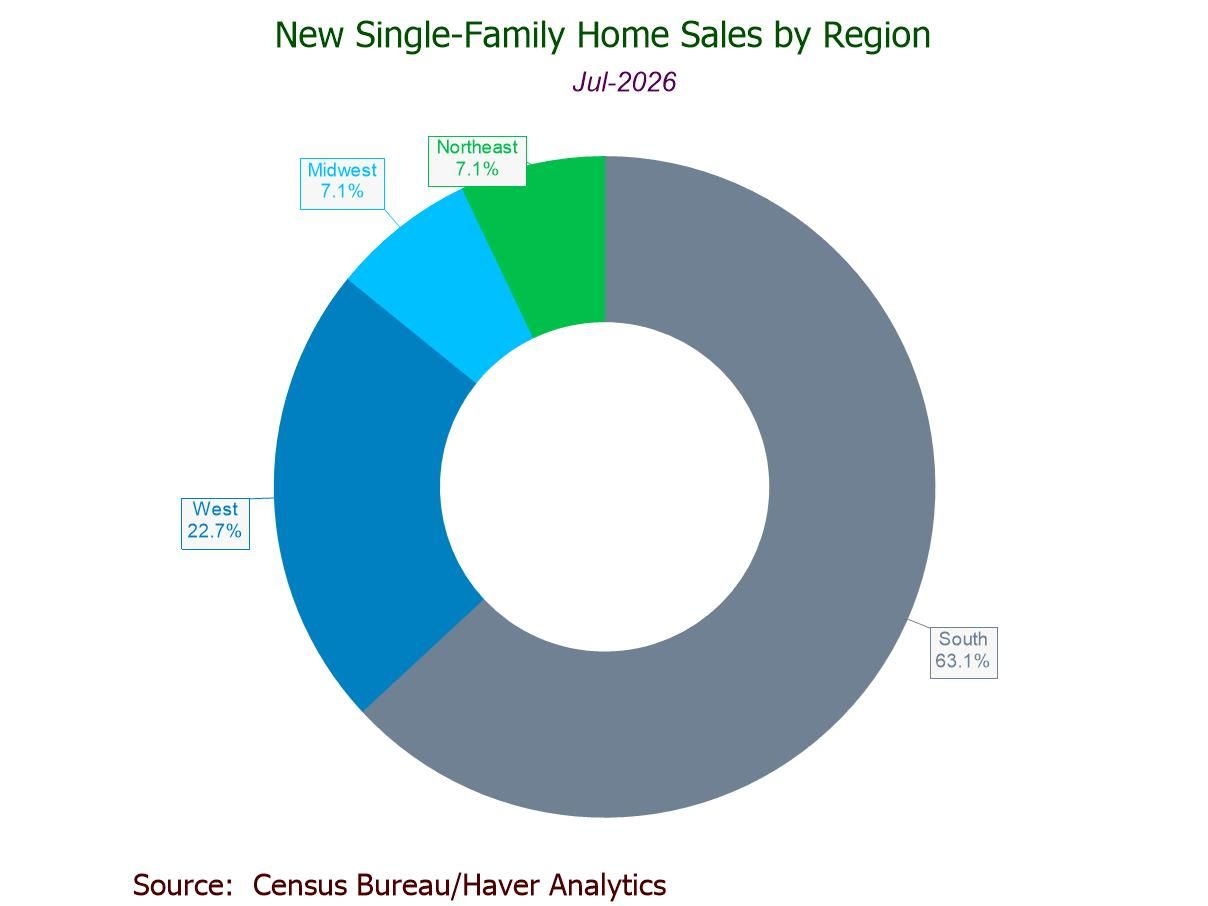
    • Sales -10.5% m/m (-6.3% y/y) to 607,000 in July; down 19.8% from a November high.
    • Sales m/m down in the Midwest (-42.7%) and South (-13.0%); up in the Northeast (+30.3%) and West (+6.2%).
    • Sales y/y plunging in the Midwest (-50.6%); surging in the Northeast (+95.5%).
    • Median sales price -2.3% m/m to $393,800, a five-year low; avg. price +4.1% m/m to $508,800.
    • Unsold inventory +1.9% m/m (-1.6% y/y) to 488,000, highest since Oct. '25.
    • Months' supply up to 9.6 mths., a six-month high.