Haver Analytics
Haver Analytics

Introducing

Tian Yong Woon

Tian Yong joined Haver Analytics as an Economist in 2023. Previously, Tian Yong worked as an Economist with Deutsche Bank, covering Emerging Asian economies while also writing on thematic issues within the broader Asia region. Prior to his work with Deutsche Bank, he worked as an Economic Analyst with the International Monetary Fund, where he contributed to Article IV consultations with Singapore and Malaysia, and to the regular surveillance of financial stability issues in the Asia Pacific region.

Tian Yong holds a Master of Science in Quantitative Finance from the Singapore Management University, a Master of Science in Analytics from the Georgia Institute of Technology, a Bachelor of Science in Mathematics from the Singapore University of Social Sciences, and a Bachelor of Science in Banking and Finance from the University of London.

Publications by Tian Yong Woon

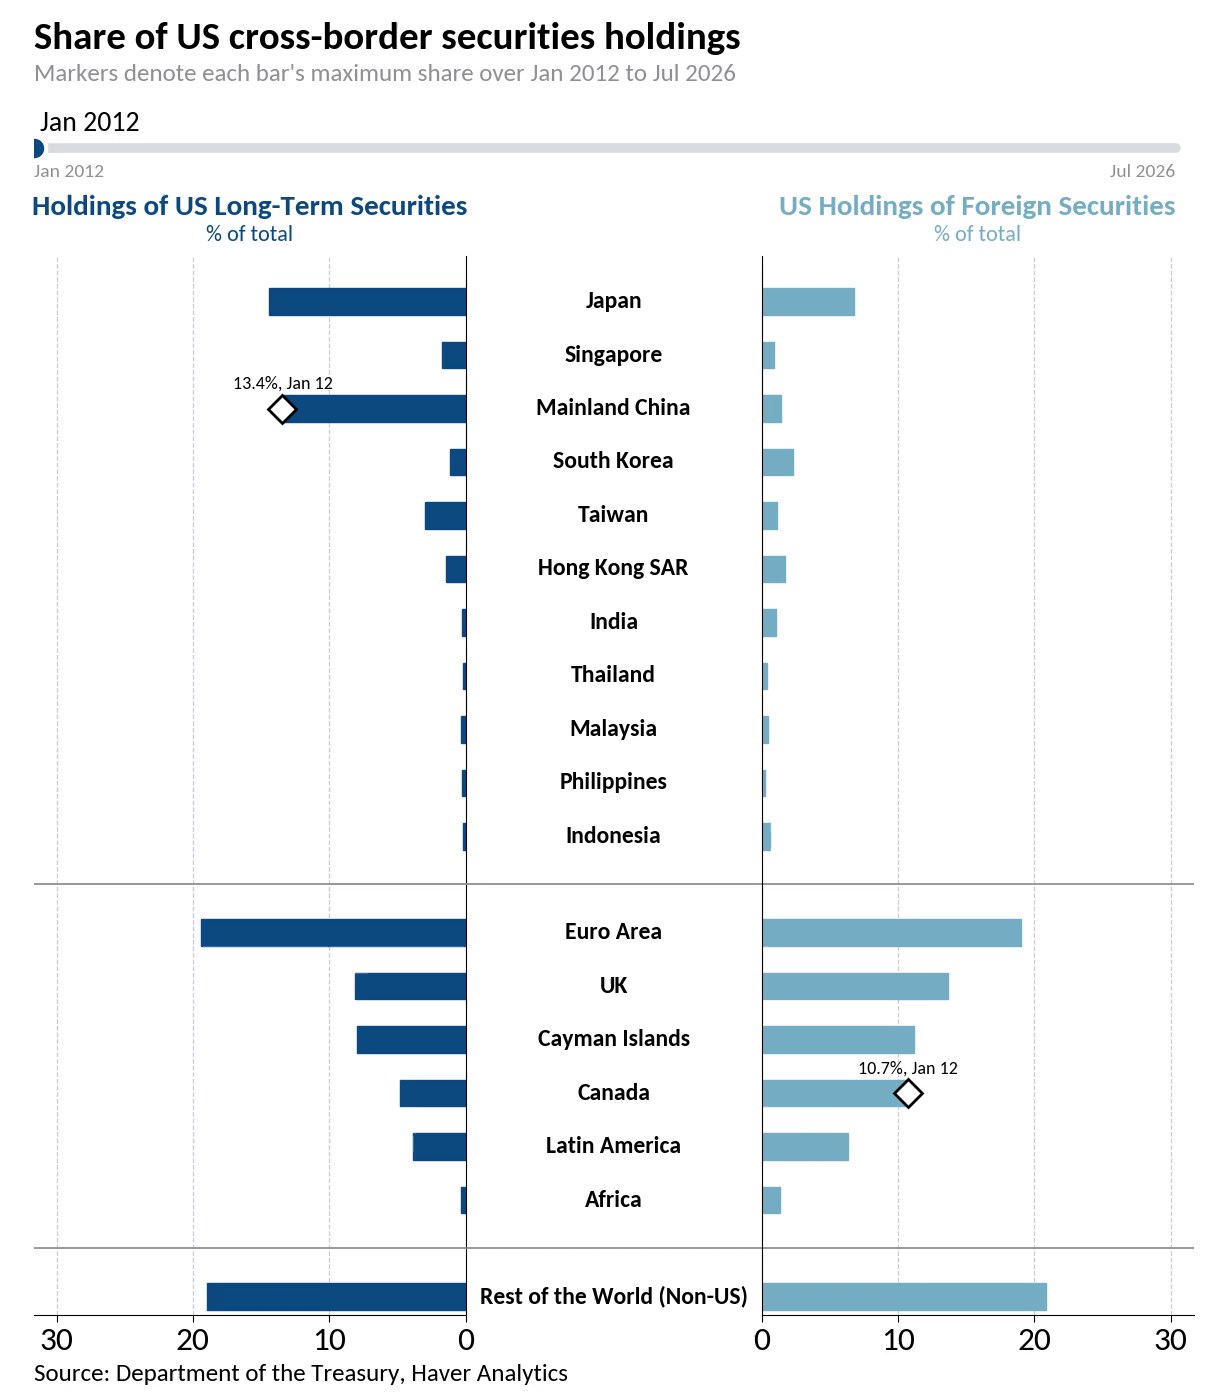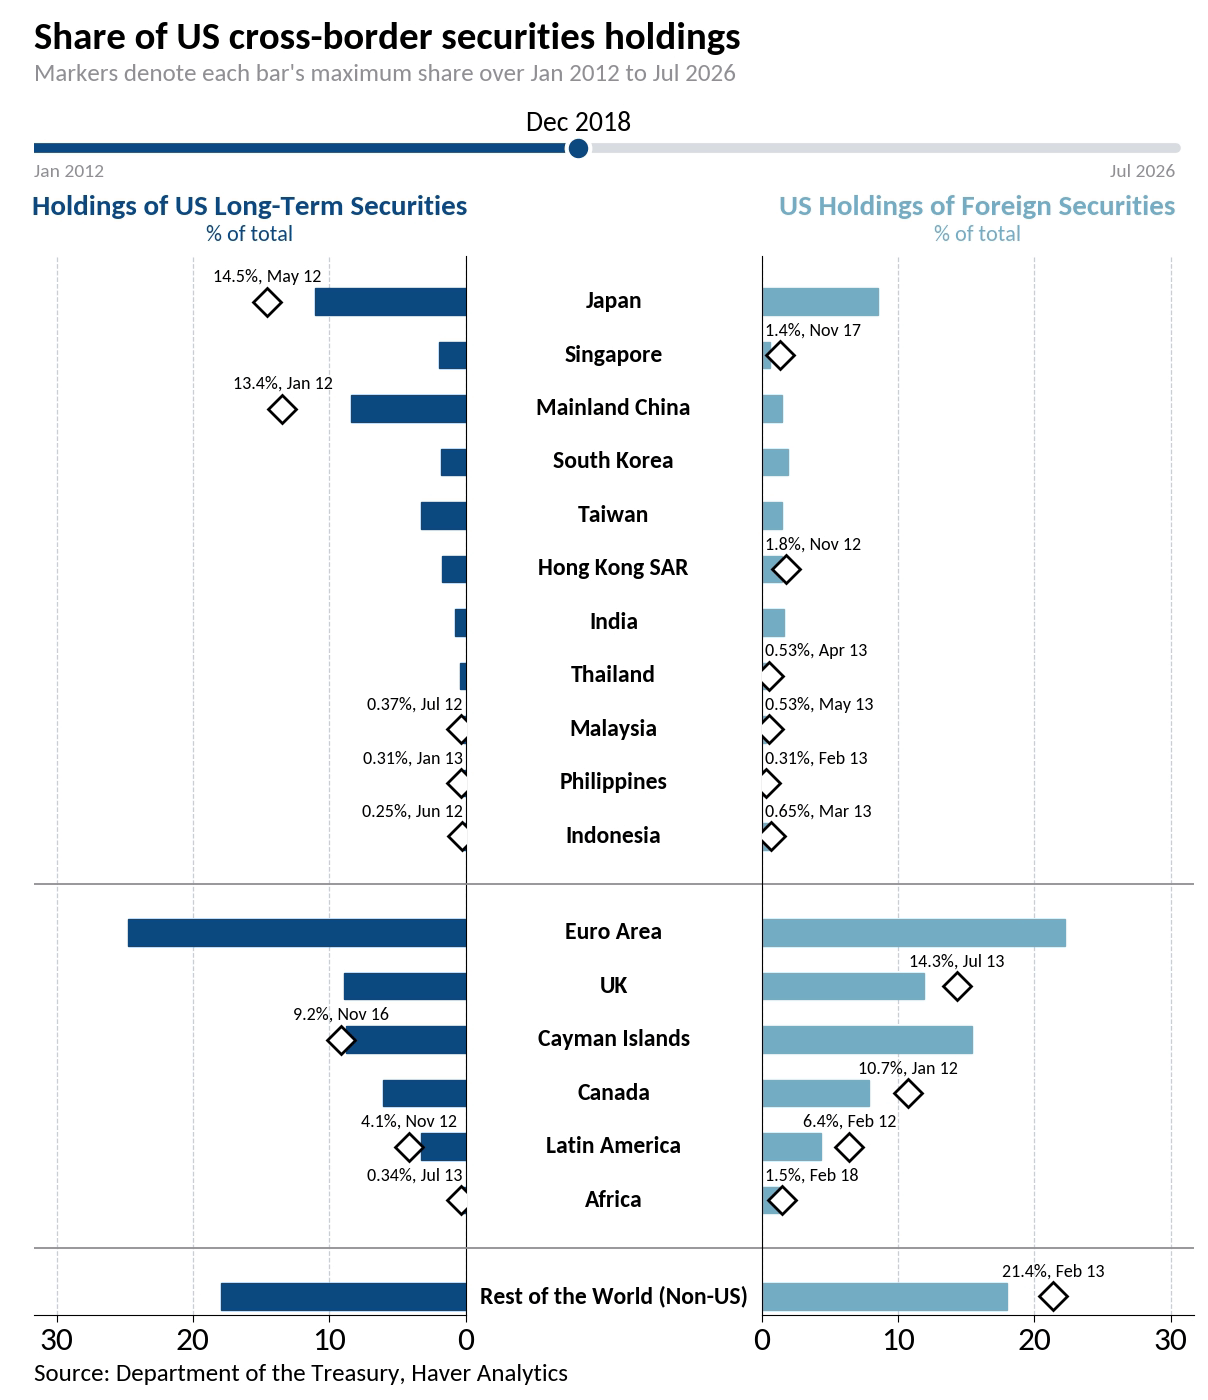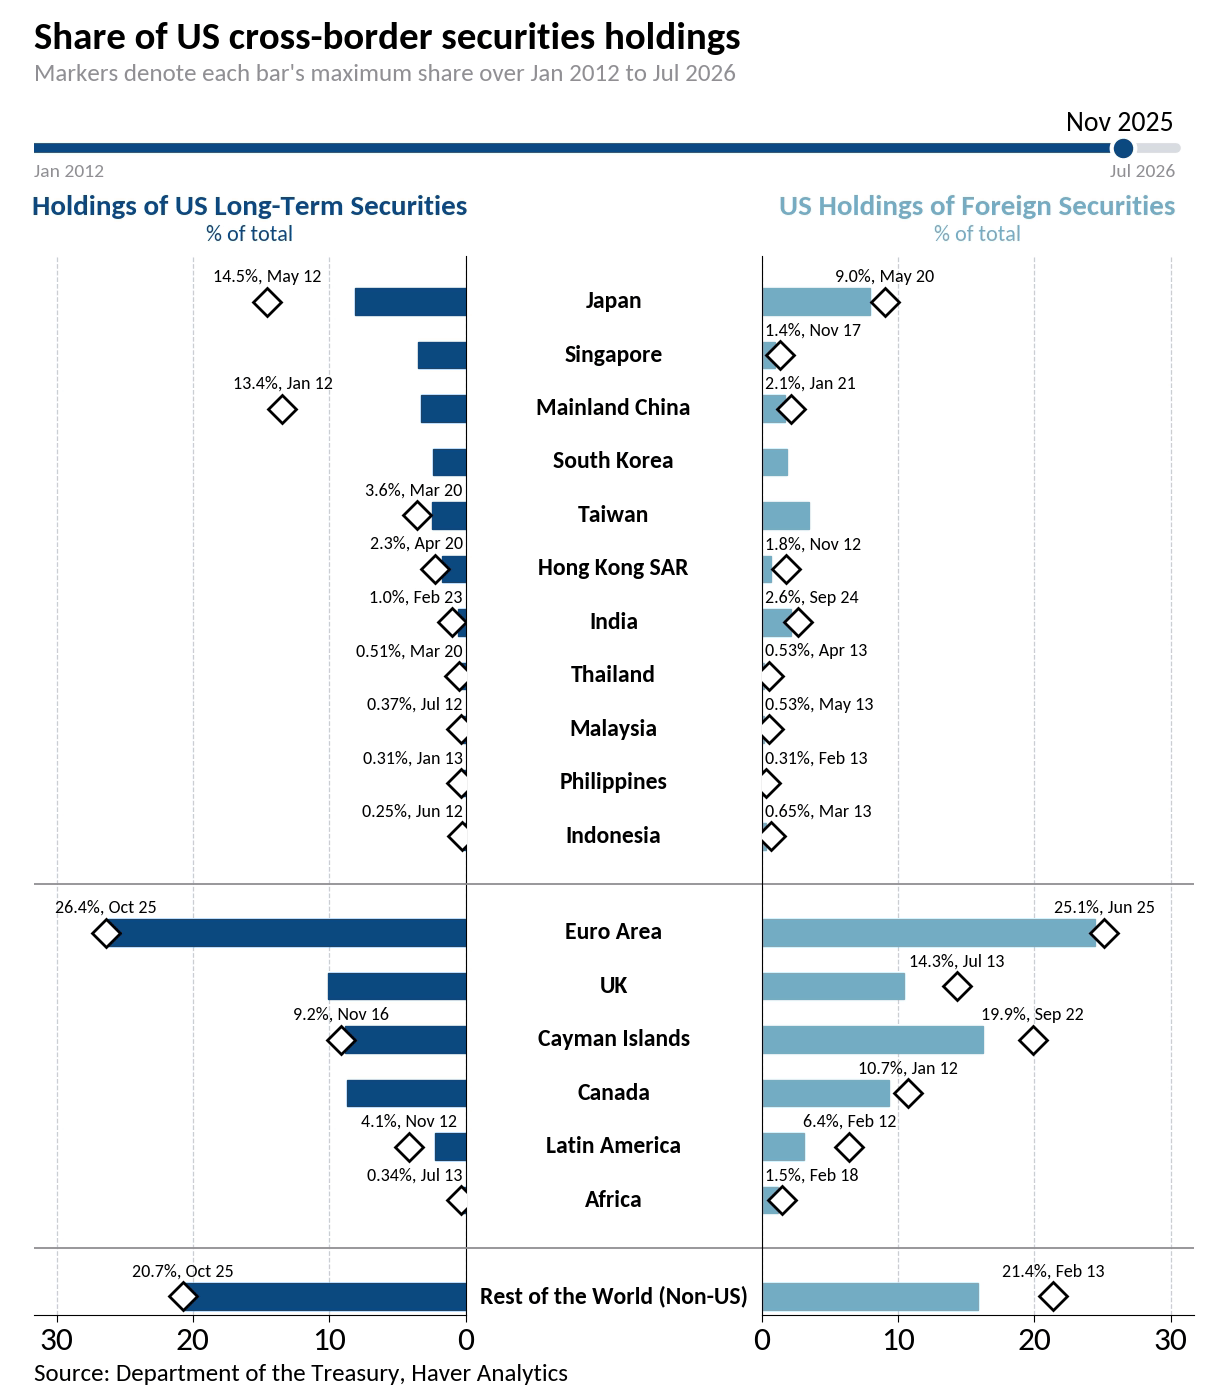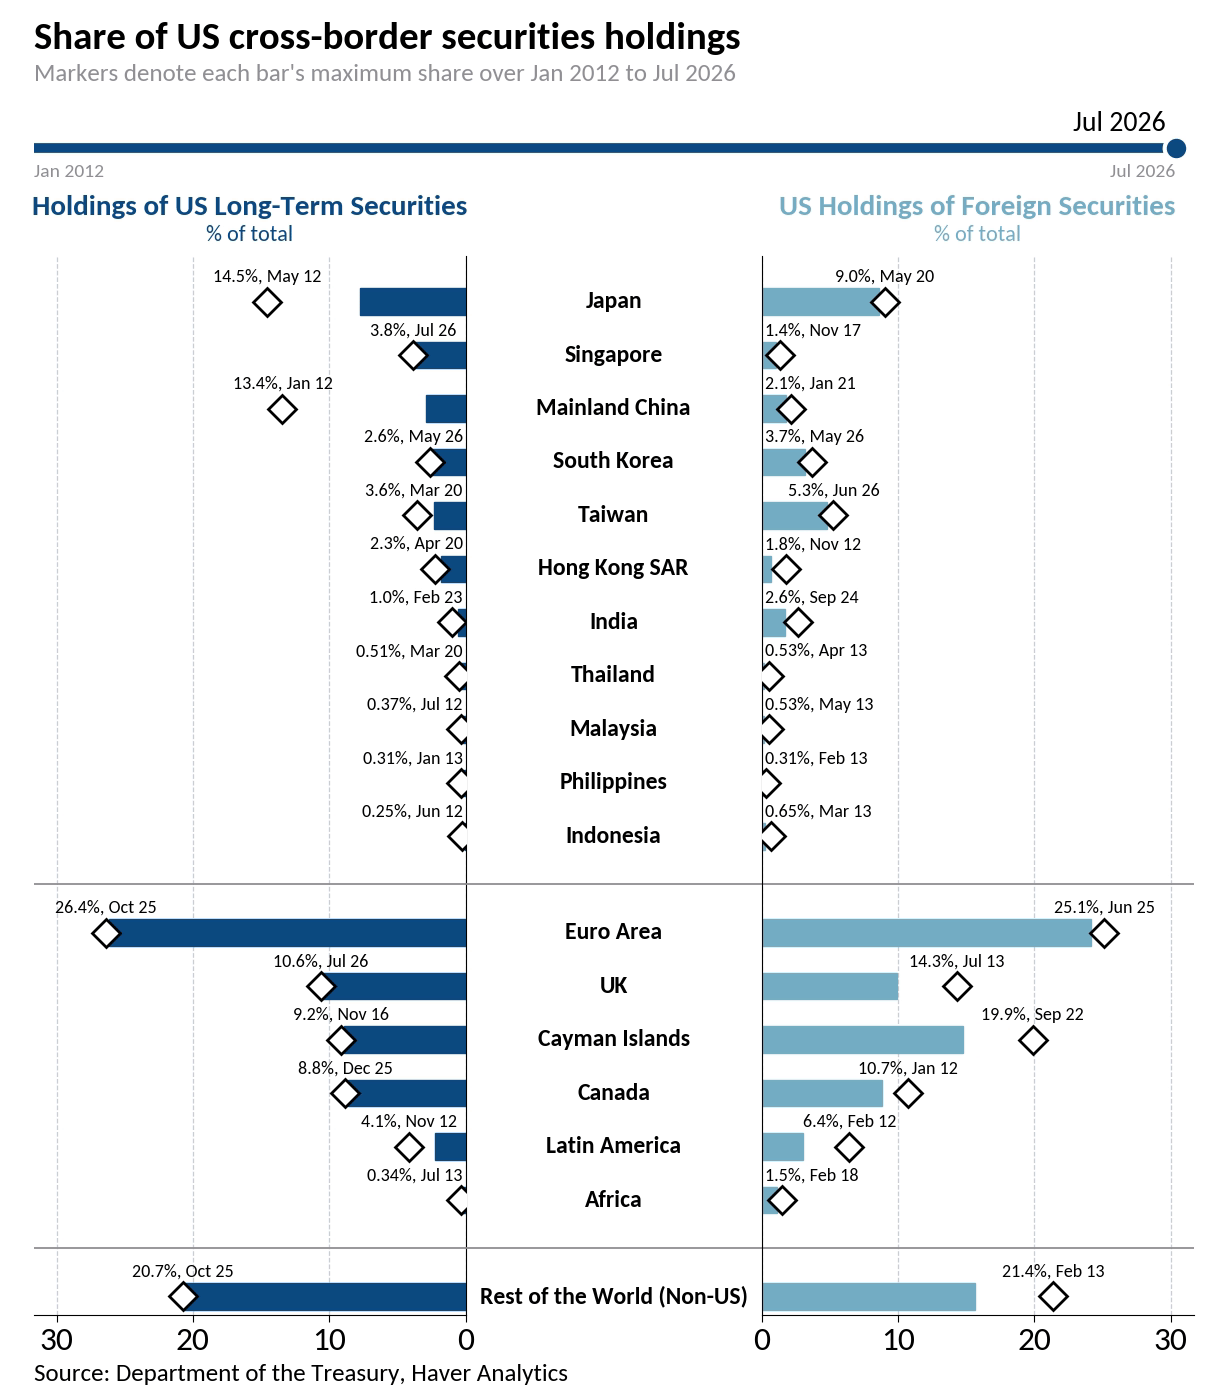
  • This week, we assess whether Asia is really moving away from the dollar by examining its US asset holdings, reserves, gold purchases and trade settlement. We then turn to Japan’s monetary normalisation. Asia’s presence in US portfolio markets has declined since the early 2010s (chart 1). Japan's share of foreign holdings of US long-term securities has halved, and mainland China's has fallen further still. The euro area and the UK have absorbed most of that ground. Even so, Japan is still the largest foreign holder of Treasuries, and a reshuffling among creditors need not mean an exit from dollar assets. Official reserves tell a similar story (chart 2). The dollar's share is down close to 6 percentage points over eight years, to 57.1%, yet no single currency has picked up all of it. The residual group of other currencies gained most, which points to diversification rather than substitution. Gold fits that reading (chart 3), with Singapore, India, Thailand and China all adding heavily in volume terms. Reserve growth alone may explain part of the rise. Trade settlement has moved least of all (chart 4). South Korea still settles about 84% of exports and 79% of imports in dollars, and broader studies point the same way. Moving to Japan, the central bank raised its policy rate to 1.25% last week, with Governor Ueda striking a hawkish note (chart 5). The spread to Fed, ECB and Bank of England policy rates has narrowed to about 2 percentage points. The yen, meanwhile, has rebounded from a record low after coordinated intervention, while the 10-year JGB yield has touched 3% (chart 6).

    Gold, the US, and the US dollar Asia's footprint in US portfolio markets has thinned considerably since the early 2010s (chart 1). Japan's share of overall foreign holdings of US long-term securities has roughly halved, from a peak near 14.5% in 2012 to about 8% in July 2026. Mainland China's slide is starker, from 13.4% at the start of 2012 to roughly 3%. The euro area has absorbed most of that ground, rising from about 19% to around 26%, while the UK sits at a record 10.6%. Japan nonetheless remains the largest foreign holder of Treasuries at USD 1.1tn, while China's holdings have slipped to USD 618bn, the lowest since September 2008. A reshuffling among creditors is not always the same as an exit from dollar assets. Japan also remains Asia's largest holder on both sides of the ledger, accounting for about 8.6% of US holdings of foreign securities.
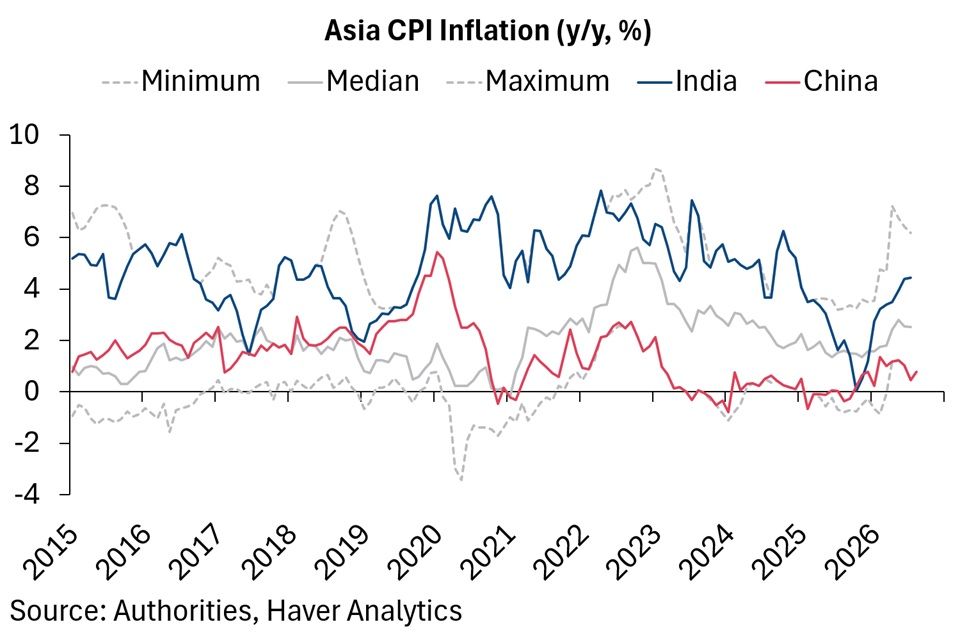
  • In this week's Letter, we examine the divergences running through Asia's inflation, monetary policy and currency performance. Headline CPI inflation has risen across much of the region, driven in large part by the closure of the Strait of Hormuz. Underlying dynamics nonetheless remain disparate, with China recording the region's lowest inflation rates and India facing renewed food and oil pressures (chart 1). China warrants closer attention still, since its producer price inflation now runs far ahead of consumer inflation (chart 2). Weak passthrough to domestic prices, soft demand and Beijing's campaign against destructive price competition all help explain that gap. Disparate inflation outcomes, in turn, are feeding divergent monetary policy stances, though that divergence has narrowed somewhat (chart 3). India has paused its rate cuts, while the Bank of Japan continues its gradual normalisation. Japan also sits at the centre of a protracted rise in yields, shared with its major-economy peers. A decomposition suggests real yields, rather than breakevens, have been the greater driver, amid concerns about fiscal policy and capex (chart 4). Divergence runs through currency performance too, with relative standings shifting repeatedly on a trade-weighted basis (chart 5). The Indian rupee has been the worst performer year-to-date, only recently ceding that position to the Philippine peso. At the other end of the table, the Chinese yuan has been dethroned by a resurgent South Korean won. Strong AI-driven export inflows had long been offset there by persistent portfolio outflows.

    Inflation divergence Headline CPI inflation has risen across much of Asia this year, on many measures. Surging energy prices, driven by the continued closure of the Strait of Hormuz, account for a large part of that rise. Underlying inflation dynamics within the region, however, remain quite disparate from one economy to the next. External forces such as oil prices and supply shocks are only part of the story. Domestic conditions matter too, notably the strength of domestic demand and each economy's dependence on imported goods, which is another way of describing its degree of self-sufficiency. China illustrates the point, with inflation still short of breaking conclusively above the low to no inflation region. That owes arguably in part to domestic demand conditions, which remain comparatively weak. It has once again logged the region's lowest inflation rates in recent months, reclaiming that spot from Thailand (chart 1). India sits at the other end, having ceded the top spot for headline CPI inflation to the likes of Vietnam and the Philippines since early 2025. Its recent resurgence in consumer inflation nonetheless points to a dependence on imported oil. Fresh risks have also emerged more recently from food and agricultural shocks, tied to ongoing and possibly worsening El Niño effects.

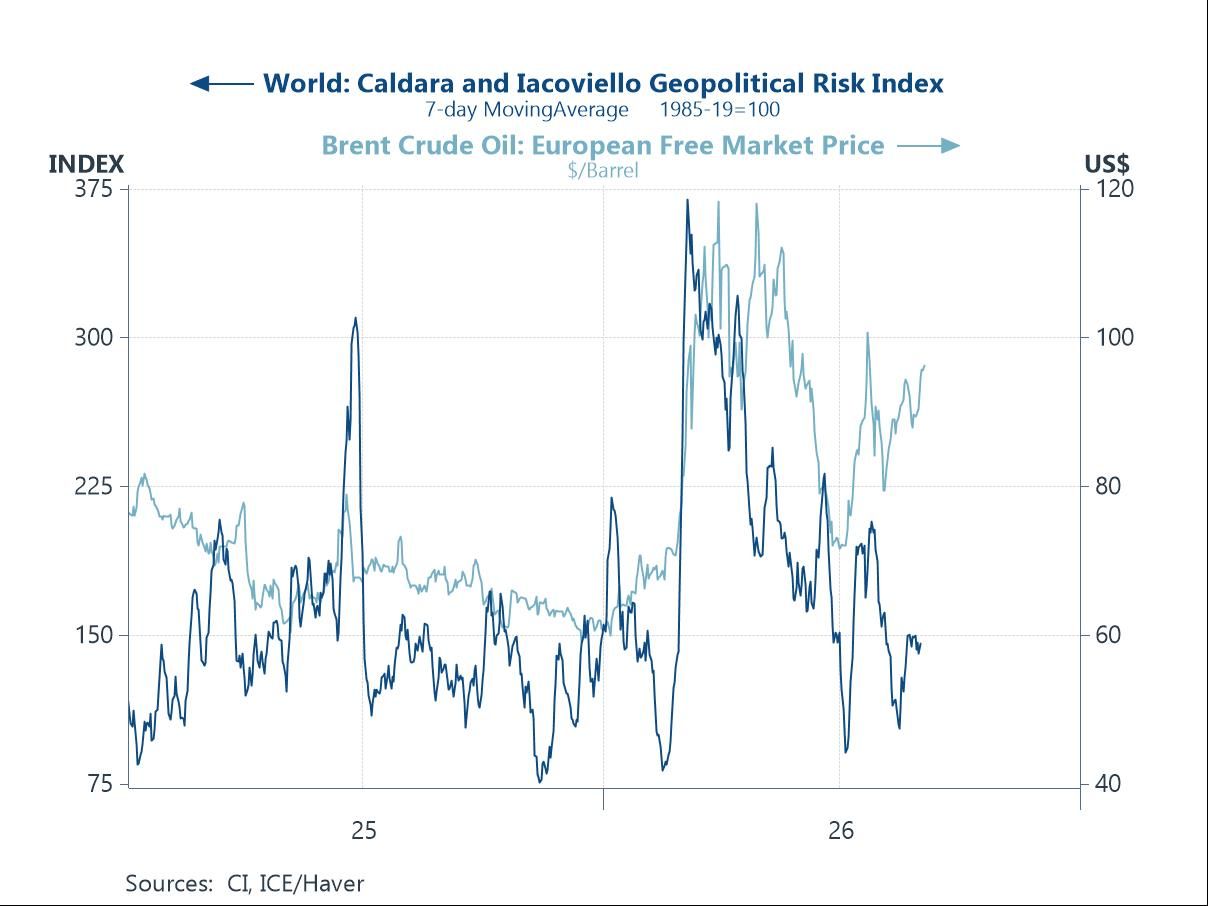
  • In this week's Letter, we weigh Asia's building supply-side inflation risks against the AI export boom still powering regional growth. The US-Iran conflict has escalated once again, lifting crude prices and keeping geopolitical risk elevated (chart 1). Should oil hold at current levels without advancing further, base effects should eventually pull that impulse out of inflation. A second price risk is now building, and it is El Niño, an event already under way (chart 2). Drier conditions in parts of Southeast Asia and redistributed rainfall elsewhere stand to disrupt crops and lift food prices. Markets have started to price these risks in through higher yields. Japanese government bond yields have surged alongside global peers, also pushed by fiscal concerns as the budget is drawn up. Domestic buyers have reduced their net sales of JGBs, with the 10-year yield now flirting with 3% (chart 3). Set against these pressures, advanced Asia's AI buildout continues to run apace. Producers of critical AI chips in Japan, Taiwan and South Korea are posting double and triple-digit export growth (chart 4). The focus is also broadening from AI infrastructure towards physical applications such as humanoid robots. China has benefited too, with integrated circuits and computer equipment contributing about half of its export growth (chart 5). The remainder has come from other goods, including EVs, amid a still-robust overall export trend. By region, ASEAN-6 and India have driven that growth, offsetting the steep fall in shipments to the US (chart 6). That success, however, has again deferred China's longer-term rebalancing towards consumption.

    US-Iran tensions: No let up The US-Iran situation has escalated once again with a familiar headline, as both sides traded strikes over the weekend, with no clear resolution in sight. The latest strikes have brought the conflict well into its sixth month, pushing crude oil prices higher and keeping measures of geopolitical risk elevated (chart 1). All of this continues to give policymakers reasons to worry. With that said, while elevated oil prices have been pushing inflation upwards, that impulse should eventually fade. If prices stay at current high levels for at least another six months without advancing substantially further, base effects will pull them out of inflation calculations.

  • In this week’s Letter, we examine why the continuing oil shock is placing renewed pressure on several Asian currencies—and why the mechanisms differ significantly across economies. The US–Iran conflict shows no meaningful sign of abating, with further strikes exchanged earlier this week. Meanwhile, shipping through the Strait of Hormuz remains severely disrupted (chart 1), effectively putting a floor beneath crude prices. The resulting increase in energy costs is sustaining inflation risks and worsening the terms of trade for oil-importing economies. This has contributed to the weakness of both the yen and the rupee this year, although energy dependence is only part of the explanation (chart 2). Unfavourable interest-rate differentials remain the principal constraint on the yen, while portfolio flows have amplified the rupee’s decline. Pressure on the Indonesian rupiah, by contrast, owes more to concerns about domestic politics and fiscal credibility. Although broad dollar strength is often blamed for the region’s currency weakness, our trade-weighted nominal dollar index has moved largely sideways.

    India’s vulnerability to the oil shock is particularly pronounced. Domestic crude production covers only a small share of consumption, leaving the economy highly exposed to movements in global prices (chart 3). South Korea, Japan and Taiwan face similarly heavy import dependence, while the headline figures for China probably understate its underlying exposure. For India, however, a deteriorating energy bill has coincided with financial-account pressure. Portfolio investors withdrew capital for an extended period after conflict erupted in late February (chart 4). These outflows subsequently reversed after the RBI introduced incentives in June to attract dollar deposits—measures that proved effective enough to be withdrawn ahead of schedule. Nevertheless, the rupee has recovered little of its earlier decline. Indonesia presents a different risk profile. Investor unease centres less on oil-import dependence than on the direction of fiscal policy and the broader political environment. Foreign ownership of rupiah-denominated government bonds has fallen below 13%, even as the outstanding stock of debt has continued to expand (chart 5). President Prabowo’s USD 230bn budget for 2027 targets a smaller deficit (chart 6), but it remains unclear whether this will be sufficient to restore investor confidence.

    The oil situation There is little sign of a substantive let-up in the US-Iran situation. Both sides exchanged strikes earlier this week, the first such exchange in about a month. Absent the strikes, the underlying economic reality remains broadly unchanged. Shipping traffic through the Strait of Hormuz has remained weak (chart 1), leaving an implicit floor under crude oil prices. Upside inflation risks stemming from energy therefore remain alive, and with them the implications for monetary policy. Beyond inflation, this protracted bout of elevated oil prices continues to add to the hefty bills faced by net energy importers, in the region and well beyond it.

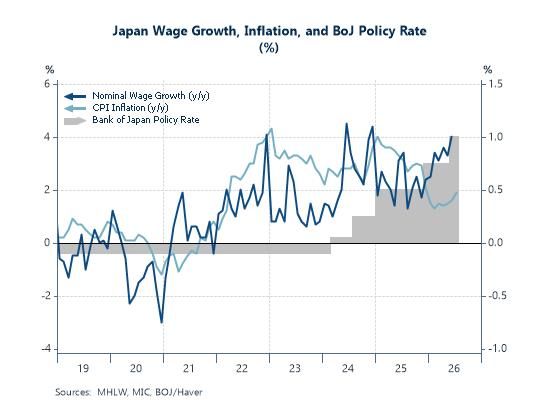
  • In this week's Letter, we examine how Japan's hard-won reflation is being tested by an energy shock and a fiscal turn. Japan has come a long way in achieving substantive inflation and, more recently, real wage growth, substantiating its tightening cycle (chart 1). Q2 real GDP growth nonetheless underwhelmed, dragged partly by a slump in public inventories that may prove one-off (chart 2). More discouraging was private consumption, whose contribution to growth was flat over the quarter. Delving into the household picture, real spending has continued to shrink despite real wage gains in recent months (chart 3). Elevated energy prices appear to be affecting household behaviour, stalling the translation of higher wages into domestic demand-led growth.

    Recent market moves have reflected other drivers, including renewed yen weakness after a short-lived appreciation prompted by intervention. Government bond yields have surged, reflecting both tightening expectations and concerns over Japan's fiscal health, in a climb extending well beyond Japan (chart 4). One potential offset to elevated global oil prices is domestic, and it lies in rice. Last year's constrained supply has evolved into a glut this year, with prices diving (chart 5). Given rice's weight in the consumption basket, the deflationary effects may be significant. Lastly, we turn to fiscal prospects, with talk of the 2027 budget already underway. Investors are watchful of the cabinet's expansionary bias, and how increased spending and food tax cuts may lift bond issuance, with details still scant at this juncture (chart 6).

    Japan’s state of play Japan has already managed to get many things going in its favour. After decades of low to negative inflation, consumer inflation rose above 2%, though it has since eased to just above 1% (chart 1). Accompanying the pickup in price pressures is wage growth, which has risen in nominal terms over recent years. Only more recently has it grown in excess of consumer inflation, indicating an interim period of real wage growth that generally benefits households. Sustained inflation alongside wage growth is what the Bank of Japan has long sought. With such conditions among others fulfilled, the central bank had some justification to begin normalising monetary policy, with its latest rate hike in June this year. Complications nonetheless remain. Persisting tensions between the US and Iran are keeping oil prices elevated, threatening to upend Japan's recovery in its domestic sector. They have also prompted government measures to support growth and help households tide through price increases. Those measures have drawn their own concerns, especially over Japan's fiscal health, which we discuss in more detail later.

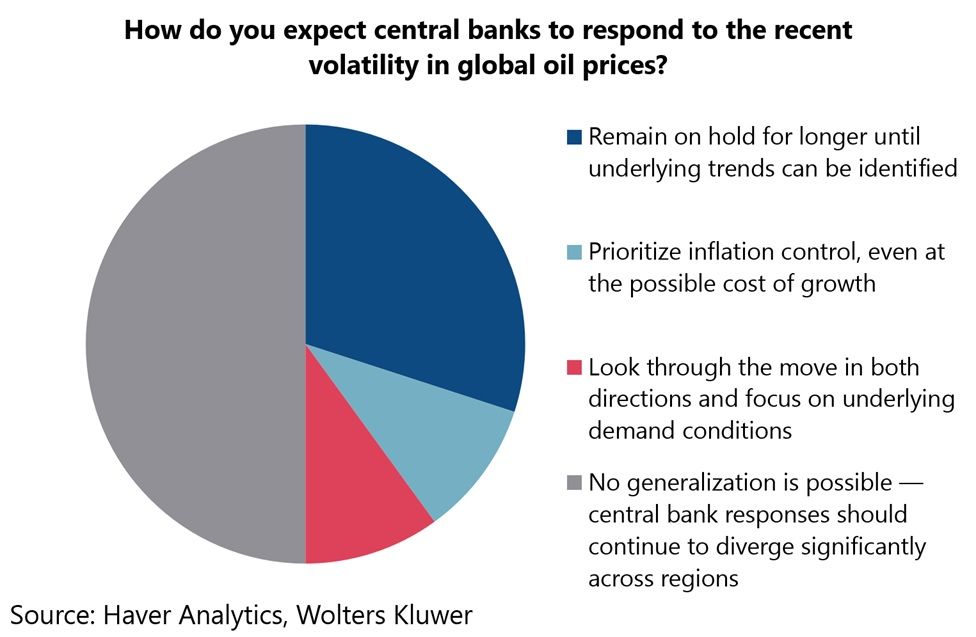
  • In this week's Letter, we dive into the latest Blue Chip Financial Forecast (BCFF) survey results in light of key developments around Asia and the broader world economy. We find that, despite the recent flare-up in US-Iran tensions, panellist expectations for policy rates remain little changed, bar the US (chart 1). Central banks are still seen as likely to continue diverging significantly across regions in response to the volatility in global oil prices (chart 2). The latest on the US-Iran conflict brings hopes of another deal on the horizon, as part of a broad on-again, off-again pattern. Those hopes have sent crude oil prices lower, albeit with flows through the Strait of Hormuz remaining at a trickle (chart 3). As global oil supply remains constrained, one key area to watch is Chinese crude oil imports (chart 4), which have slumped since the conflict broke out. There is no telling when Chinese buying will recover, if ever, and if so, by how much. Moving to Japan, and taking these developments into account, the Bank of Japan held its policy rate steady at its recent meeting. Inflation risk is still flagged as being tied to the upside (chart 5). That may threaten to upend real wage gains this year, should a price flare-up materialise extensively enough. Yen intervention talk has also returned to the fore, with the US and Japan confirming recent intervention moves. Both have signalled that more may come if needed, although the yen remains squarely within its longer-term weakening trend (chart 6).

    Blue Chip Financial Forecasts Last week, we published the August 2026 Blue Chip Financial Forecast survey results. Despite the flurry of recent headline developments around the world, we found panellist expectations only modestly changed from last month. In particular, views of 12-month ahead policy rates were little changed or unchanged for every economy bar the US (chart 1). US expectations now point to slightly higher policy rates than a month ago. Among the economies covered by the survey, the highest expected 12-month ahead policy rates still relate to Australia, followed by the US and the UK. At the other end, the lowest expected rates relate to Japan and Switzerland. The slightly higher expected US policy rate may well incorporate, among other factors, the recent re-escalation in US-Iran tensions and the inclinations of new Fed Chair Warsh. We return to those tensions in a later section below.

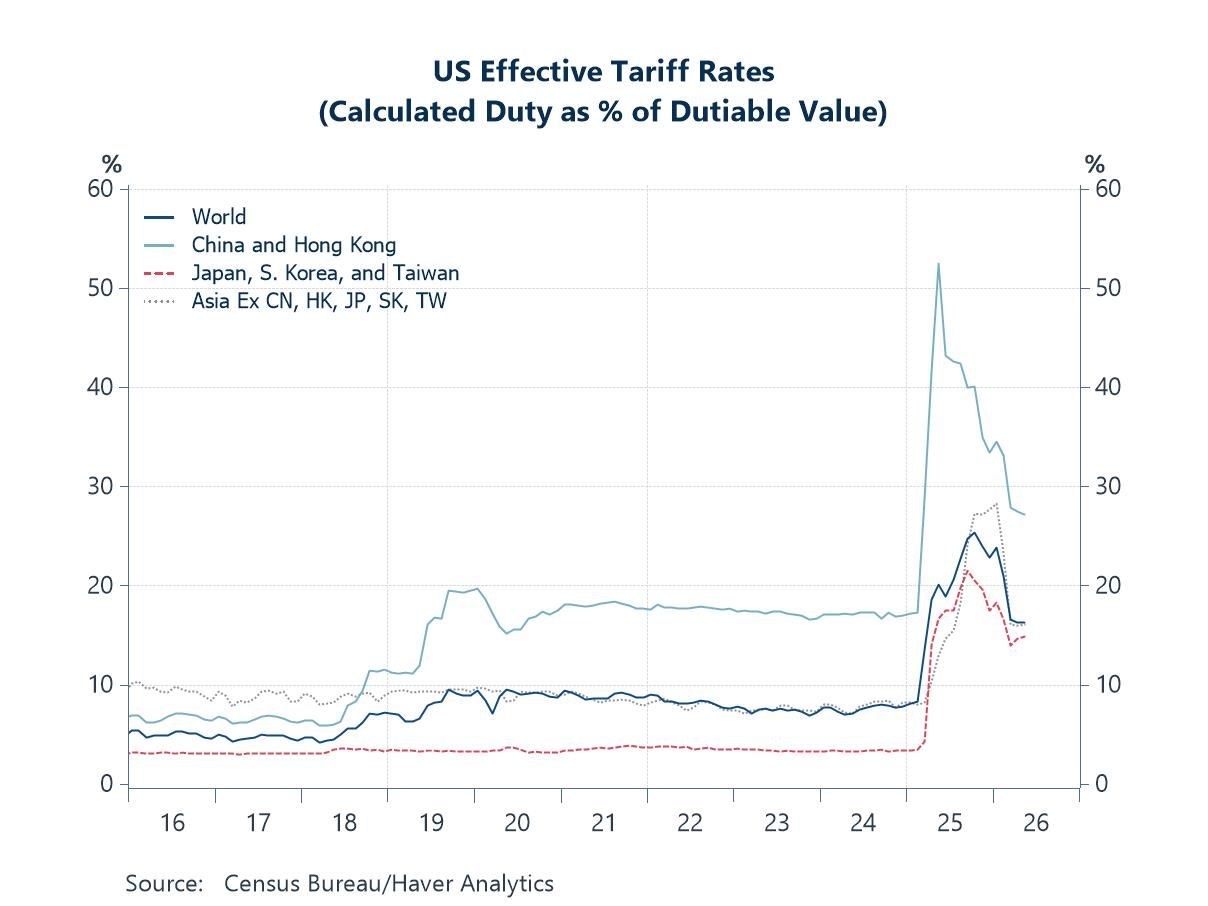
  • In this week's Letter, we trace three threats converging on Asia's inflation outlook. The first is renewed US tariffs, with the latest salvo of duties imposed over alleged forced labour issues. That move is widely seen as a replacement for the now-expired Section 122 tariffs, with only mild incremental effects from the new Section 301 duties. Set against that, the US effective tariff rate has pulled back from its 2025 highs in recent months (chart 1). The second is the Strait of Hormuz, where the re-escalation of US-Iran tensions has once again reduced shipping volumes to a trickle. Crude oil prices have been driven up as a result (chart 2). It could have been worse, were it not for China's sharply reduced crude imports over the period (chart 3). Arguably, though, at least part of that reduced intake simply reflected the absence of supply from the Strait. The third is the ongoing El Niño event, which several authorities have warned will likely be the largest on record (chart 4). It risks disrupting food crop yields, among other effects, channelling a price shock through food supply. Together these pressures threaten to upend the pullback in commodity inflation seen in recent months (chart 5), once again complicating policymaking. As an aside, we also explore economy-specific political developments that are brewing or could become an issue further down the road. One is the recent resignation of Indonesia's central bank governor, which came amid protracted rupiah weakness (chart 6) and concerns about fiscal health.

    Tariff trouble Recent US forced labour tariffs have revived concerns, pushing the tariff theme back to the fore. The US imposed additional Section 301 duties of 10% or 12.5% on imports from 60 investigated economies, effective 24 July 2026. These followed USTR investigations into those economies' failure to impose and enforce prohibitions on goods produced with forced labour. They took effect the same day the temporary 10% Section 122 global surcharge expired by statute, and are seen as its replacement. Yet overall US effective tariff rates, calculated as duty as a percentage of the respective dutiable value, have pulled back significantly from their 2025 highs (chart 1). That retreat began with the numerous bilateral trade deals the US eventually struck with many of its trading partners. It went further in February, when the Supreme Court struck down President Trump's tariffs imposed under the International Emergency Economic Powers Act (IEEPA). That ruling dented the overall impact of US tariffs on its trading partners, with possible tariff refunds still in the works. Cutting the other way, the Section 122 surcharge had partially raised overall rates while it ran. Even so, some estimates suggest the new duties will only marginally increase US effective tariff rates on its trading partners.

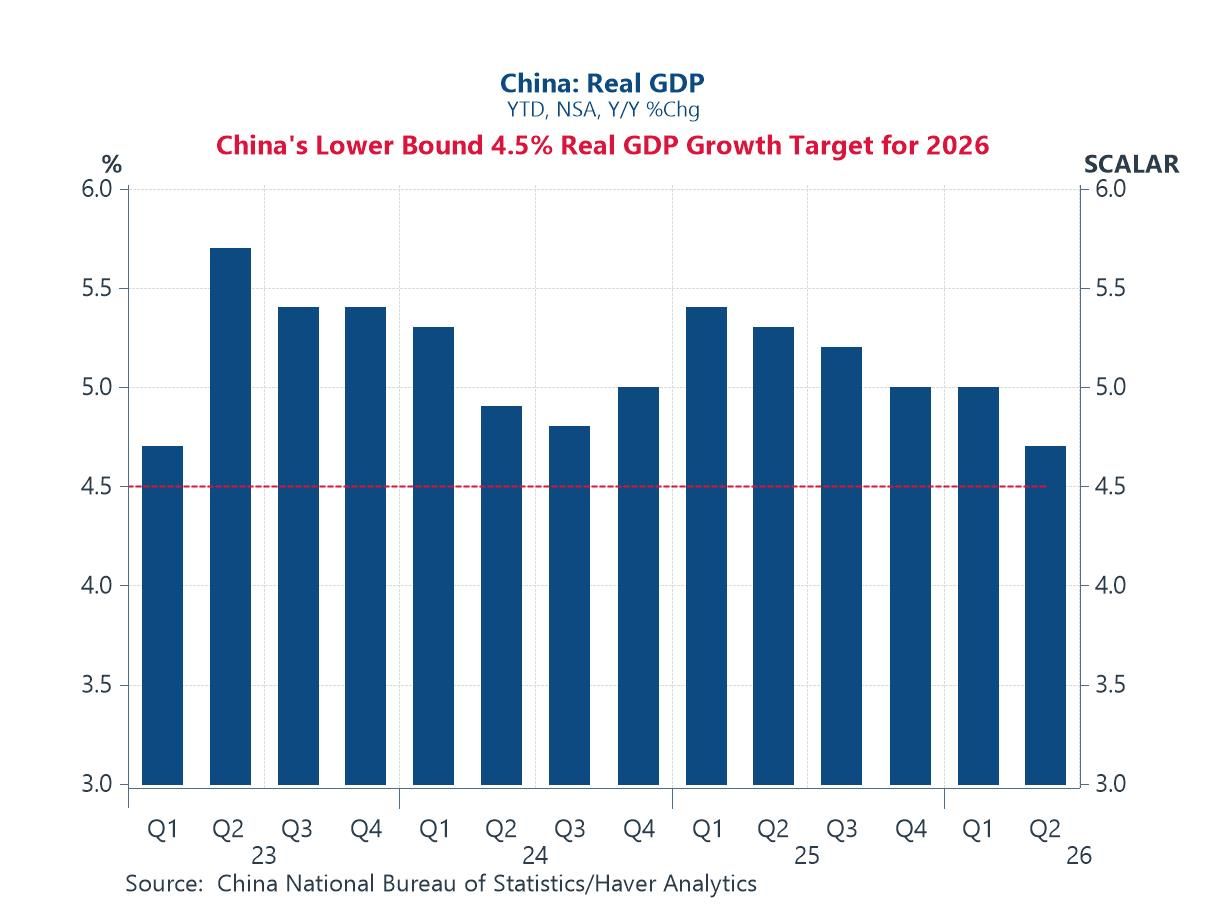
  • In this week's Letter, we examine China's increasingly two-speed economy, where robust AI-driven exports mask faltering domestic demand and a stalled rebalancing. Q2 GDP growth slowed to 4.3% y/y from 4.8%, dragging the year-to-date (ytd) rate towards the lower bound of its 4.5% to 5% target (chart 1). Beneath the headline, a two-speed split has widened, with external-oriented sectors holding up while more inward-focused prints such as retail sales and fixed asset investment weaken (chart 2).

    Exports have kept climbing even as rebalancing stalls, with the export share of GDP rising to about 21% and consumption stuck near 40% (chart 3). With consumption hard to lift, tilting away from exports would sacrifice China's main growth driver, making rebalancing a difficult path. That export strength owes much to the AI boom, as integrated circuits added nearly 6.5 ppts to June's 27% y/y growth (chart 4). Part of the surge, though, likely reflects importer front-loading ahead of expected tariff hikes and the coming holiday seasons. Domestically, however, growth in retail sales had floundered, dragged down by autos, furniture and appliances, while trade-in subsidies likely delivered only one-off, front-loaded gains (chart 5). All while a fragile consumer climate, unsettled by the ongoing property crisis, continues to hold spending back. That crisis runs deep, with property price declines now into a fifth year and no clear bottom in sight (chart 6).

    China’s Q2 GDP China's Q2 GDP results disappointed when posted last week, with growth slowing to 4.3% y/y from Q1's 4.8%. That drop dragged the y/y ytd growth rate towards the lower bound of the 4.5% to 5% target for the year (chart 1). The reading followed a run of soft monthly data, leaving investors increasingly concerned about domestic growth. Even so, China continues to benefit from more robust growth in its externally oriented sectors. This increasingly two-speed dynamic, alongside a persistent lack of economic rebalancing, remains a concern for investors. It has left them looking to Chinese authorities for signs of fresh stimulus to keep the economy on track for its full-year target. We return to these themes in later sections.

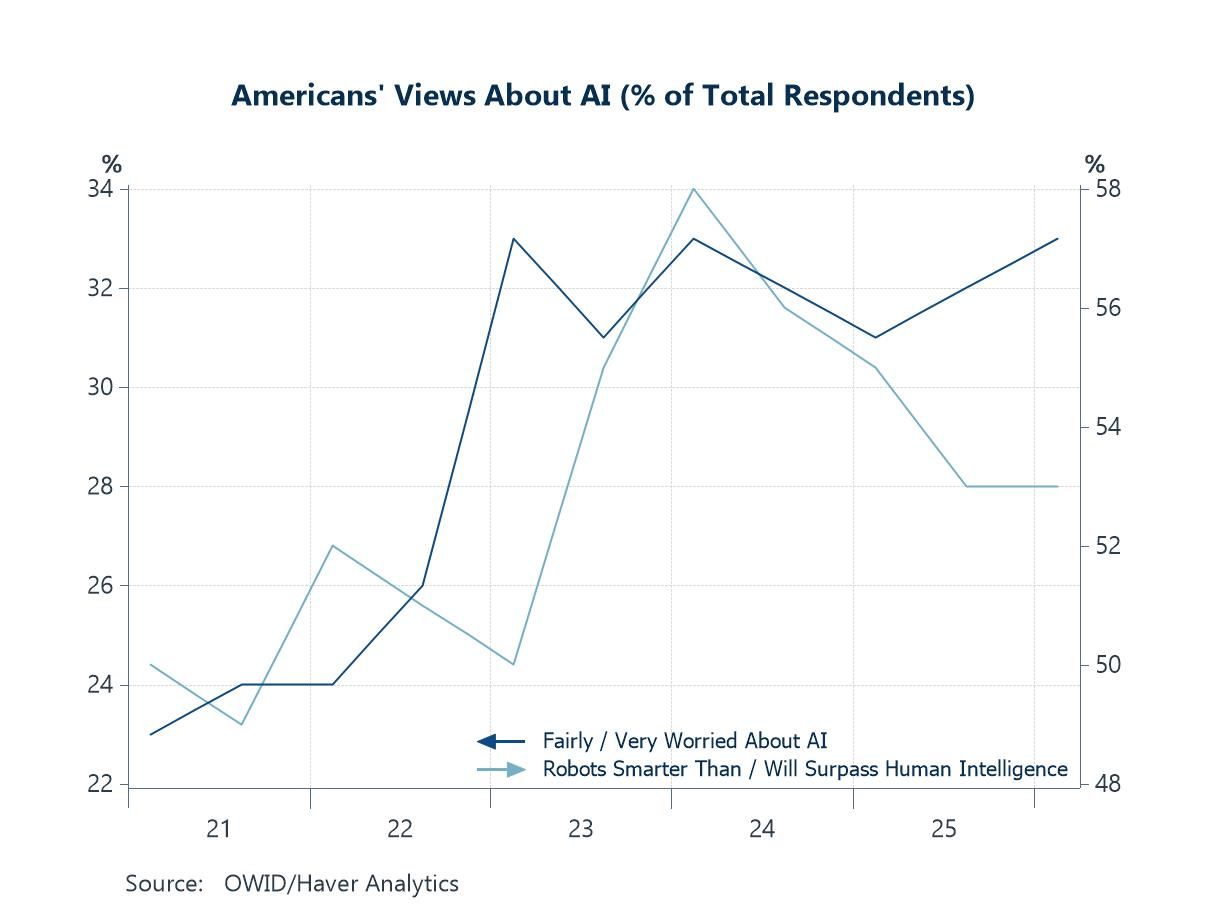
  • In this week's Letter, we examine the underbelly of the AI boom, the risks that sit beneath its optimism. Start with the public mood: American concern about AI has grown alongside adoption over the past three to four years (chart 1). Those worries span mass job displacement, misuse of top-end models by bad actors, and fears of being left behind. The first of these is already surfacing: in June, AI was again the most cited reason for announced US layoffs, with year-to-date AI-linked cuts above 100,000 (chart 2). Technology led all sectors in overall cuts, though the data do not isolate how many were AI-driven. Among those hit, the young are arguably the most exposed to these labour effects. They enter a labour pool swollen by displaced professionals, just as AI masters the entry-level tasks where they would start. India and Indonesia illustrate the stakes on youth NEET, the share not in education, employment, or training, both above 20% and among Asia's highest (chart 3). Beyond the labour market, the same optimism reshapes asset prices. The rally has lifted AI-related valuations to historic highs and concentrated a few names in cap-weighted indexes (chart 4). That raises correlation and the risk of a sharper index fall should the rally unravel. The same concentration runs through economies via exports, from Taiwan's advanced chips to South Korea's memory (chart 5). Its footprint is physical too, and cuts both ways: data-centre investment has lifted growth in Johor, Malaysia (chart 6) while straining local power and water. None of this argues against riding the AI wave, which still promises real productivity and welfare gains. Rather, these are caveats that investors and policymakers must keep in view, since the story is not all upside.

    AI-related concerns AI adoption has exploded over the past three to four years, and Americans' concerns have risen alongside it (chart 1). That is understandable, given how advanced and broad AI's proven applications have become. They now span everyday tasks and subject-specific work across fields such as finance and production, as well as tech and development, the sector AI was born in. Major concerns run from mass AI-induced job displacement to a more recent fear, that top-end models fall into the wrong hands and are used by bad actors. A further worry is distributional: AI advances are powerful and could deliver leaps in productivity, yet they may also leave many people behind. Those most exposed include workers already displaced from their jobs and people facing scarcer basic resources as AI demand competes for them. Others simply lack equitable access to AI tools or their benefits.

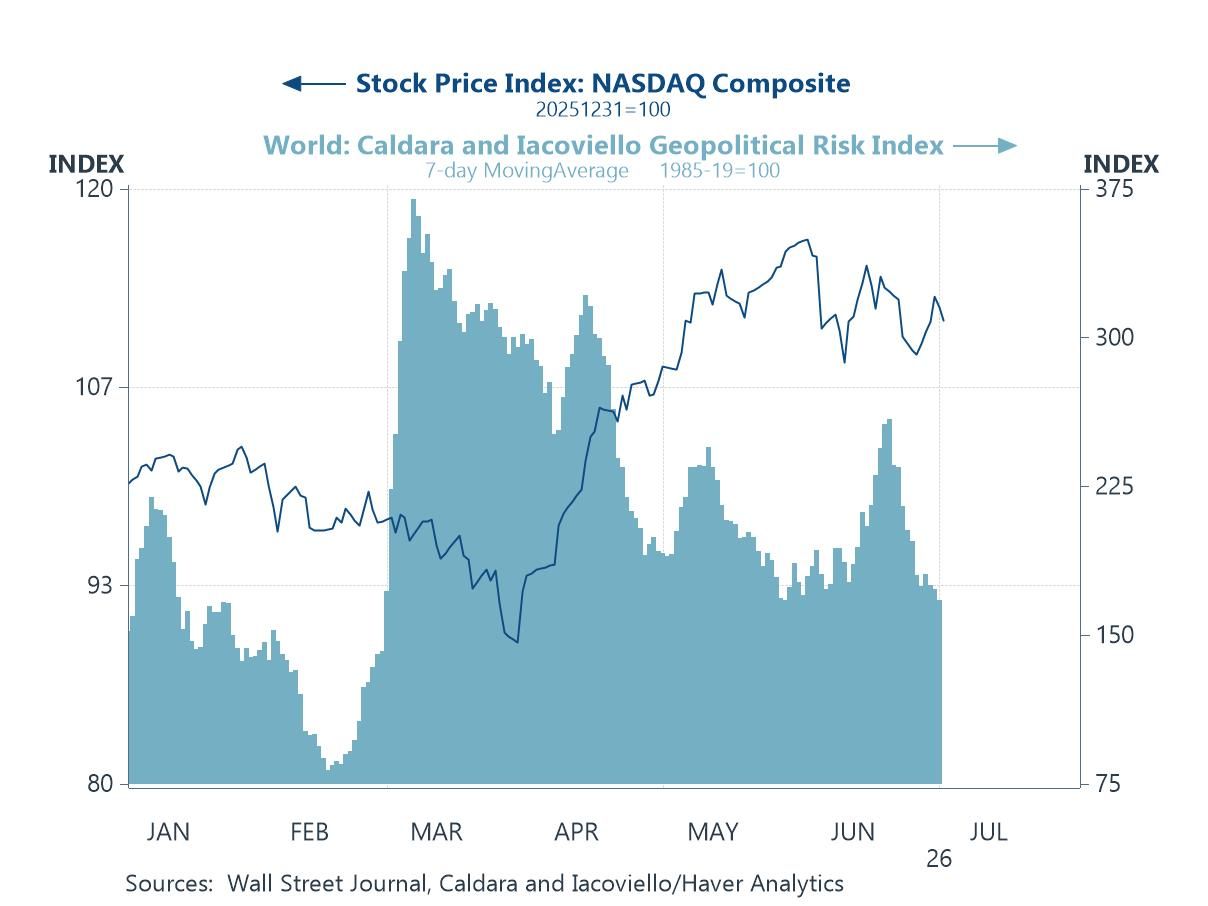
  • In this week's Letter, we trace how an energy shock and a resilient AI upcycle shaped Asia through the first half of 2026 and weigh the risks that may define the second. The year opened hopeful on AI, though some feared stretched valuations, before the US-Iran conflict and a closed Strait of Hormuz shook the mood (chart 1). A later MoU eased energy prices and inflation fears, yet valuations largely held on AI optimism, despite bouts of reassessment. The oil surge hit import-reliant emerging Asia hardest, leaving India, Thailand and the Philippines doubly exposed through their Middle East sourcing (chart 2). Pass-through inflation, subsidies that some governments later pared back, and currency pressure followed, though resuming Strait traffic should ease these strains. Rising inflation then boxed in policymakers, straining already-stretched fiscal positions and limiting more pro-growth monetary policy stances in some economies (chart 3). Our latest Blue Chip survey found a slim majority reassessed the risk balance after oil fell, though the shifts stayed mild versus the June survey (chart 4). Most still rank upside inflation risk above downside employment risk, even as a slightly larger share now see the balance as more even. AI remains the region's key offset, with Taiwan and South Korea riding a sharp rise in memory and chip exports (chart 5). Malaysia and Thailand instead draw data centre FDI, so Asia gains from the buildout phase rather than the West's hoped-for productivity gains. We close on an uncertain second half, where a possible Super El Niño could revive food-driven inflation even as energy pressures fade (chart 6). Beyond that, an AI reassessment, fresh geopolitical flashpoints, trade tensions and the US midterms could each reshape the outlook.

    The year thus far We began the year on a relatively hopeful note, buoyed by AI optimism and market valuations that reflected it, although some investors worried that valuations had become overstretched. The geopolitical mood shifted quickly in early January, however, when US military forces captured former Venezuelan leader Maduro, though the event did little to move markets (chart 1). A far greater shock came when the US-Iran conflict erupted in late February, closing the Strait of Hormuz and dealing a negative blow to global energy supplies. More recently, the US and Iran have reached a Memorandum of Understanding (MoU) aimed at ceasing hostilities and resuming trade flows through the Strait. This has allowed energy prices to ease, softening policymakers' concerns about energy-driven inflation. Even so, equity valuations have largely remained underpinned by AI optimism, albeit with interim bouts of reassessment and price retracement. This drew on repeated reports of strong growth along the AI supply chain, and on signs that supply could not keep pace with demand. This continued even as AI models with leapfrogging capabilities reached the public. At several points, the US government stepped in to rein in public access to some models, given security concerns about such immense capabilities falling into the wrong hands.

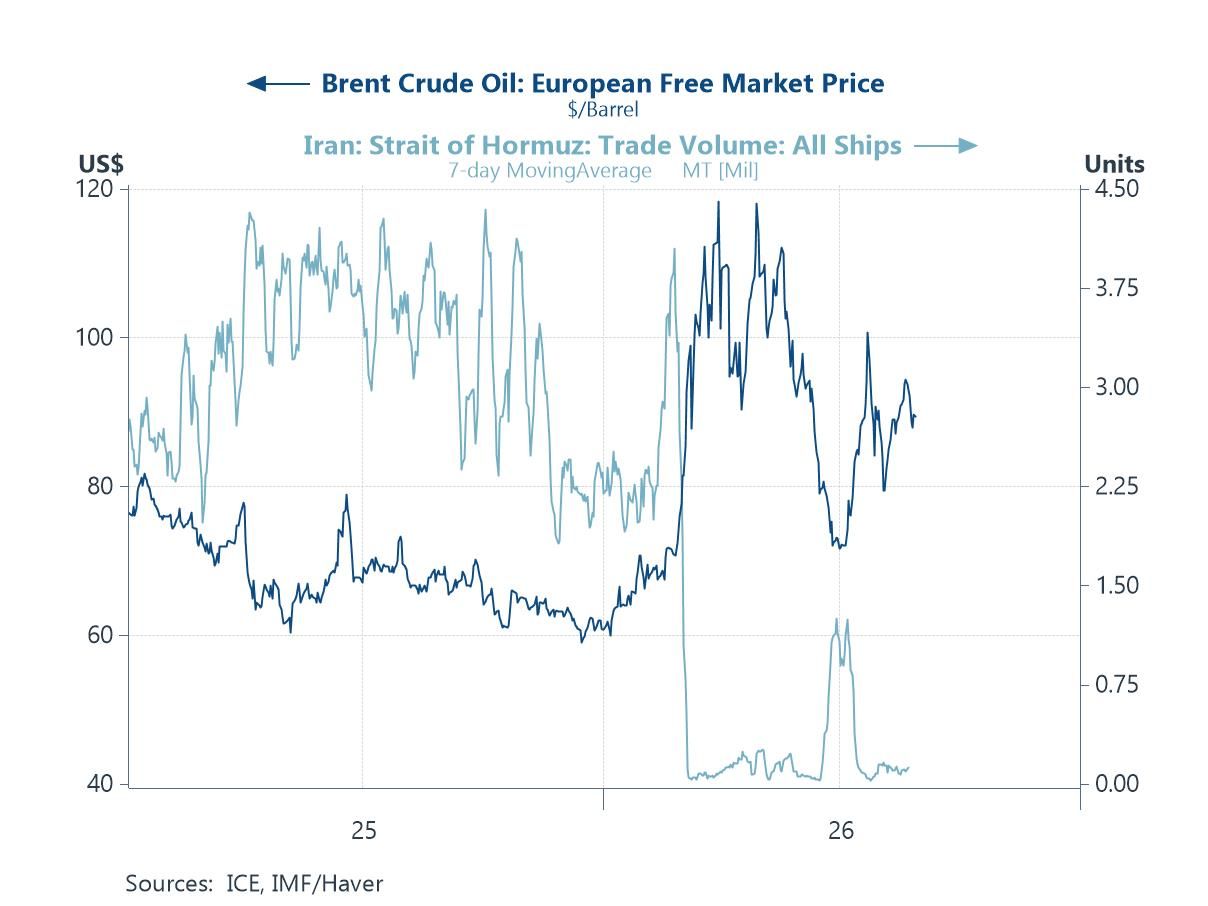
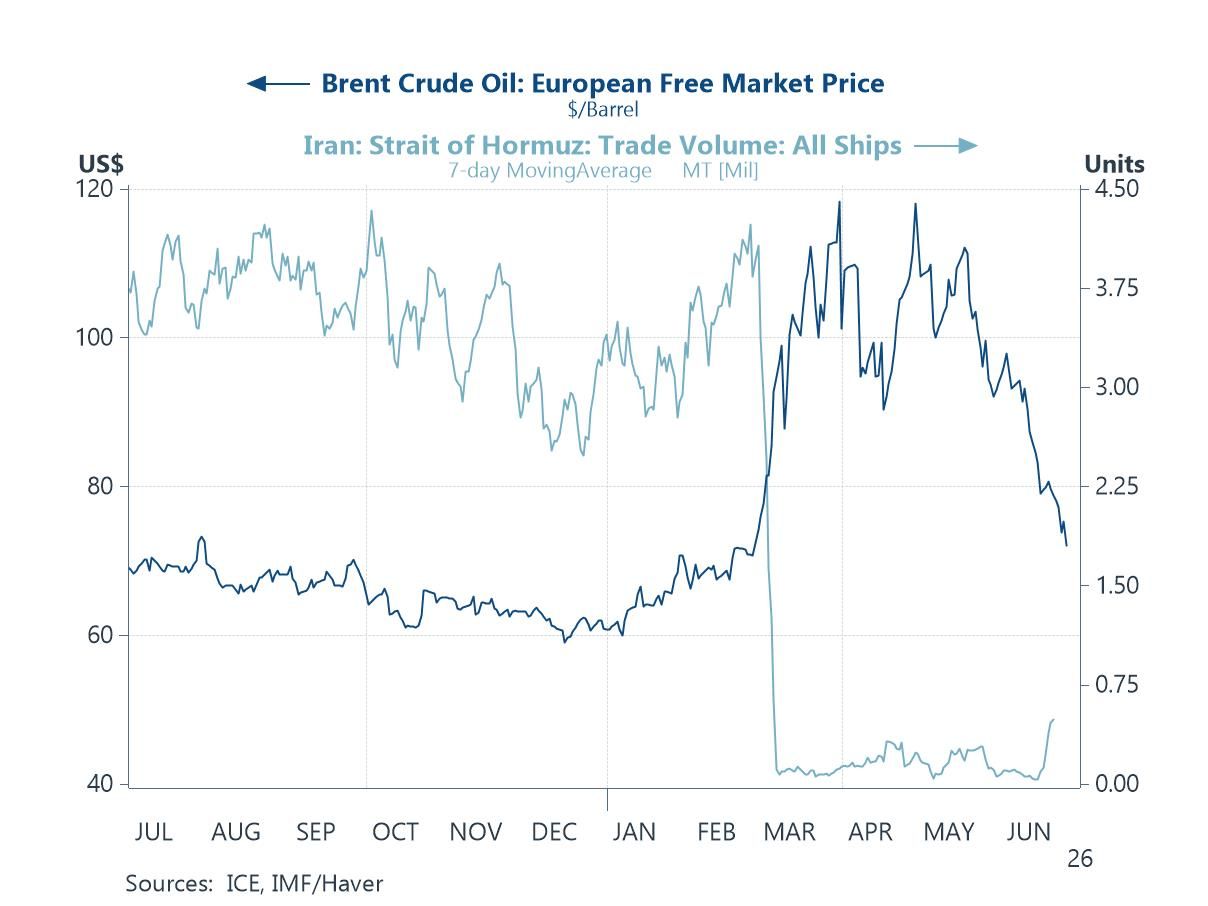
  • In this week's Letter, we explore the significant pullback in oil prices that followed the US-Iran memorandum of understanding and consider its broader economic implications. The agreement saw a fragile ceasefire ensue and a gradual resumption of shipping flows through the Strait of Hormuz (chart 1). We acknowledge that this major pullback will certainly be welcome to policymakers across the region and beyond. Previously elevated energy prices had added to the fiscal burdens of governments and sharpened the dilemma facing central banks (chart 2). That dilemma pits the need to rein in inflation against the risk of choking off economic growth. That said, while one source of inflationary pressure seems to be ebbing, another looks to be emerging on the horizon. It stems from a potential "Super El Niño" event, which meteorologists have been warning about for some time now. Asia sits at the centre of such risks, as past strong El Niño events have directly and adversely affected crop production (chart 3). The impact is not limited to potential surges in headline inflation via food supply shocks, especially in Asia. It extends directly to growth as well (chart 4), given the nontrivial share of GDP that agriculture still commands in many Asian economies (chart 5). Should price pressures simply rotate from energy to food, government subsidies may follow suit (chart 6). Central bankers, for their part, may find themselves unable to ease off the tightening pedal just yet. Some Asian economies, however, would still manage to offset such a growth shock through other engines. Electronics and semiconductors, buoyed by the current AI upcycle, offer one such cushion for the more fortunate. For others, lacking such offsets, the agricultural hit may simply have to be borne in full.

    The US-Iran conflict and oil prices The recent memorandum of understanding between the US and Iran, aimed at working towards a final deal, has already brought visible relief to crude oil markets (chart 1). This relief has held despite the renewed tensions that have followed the agreement, which markets seem to have largely looked past. The easing in prices should go a long way towards unwinding the inflation concerns that elevated oil prices had previously stoked. Much of the pullback reflects anticipation of the substantial supply now expected to return to global markets. Yet some shipping trackers, such as the IMF's, already point to a marked pickup in traffic through the Strait of Hormuz. Even so, those volumes still remain well below the levels seen before the conflict began in the region.

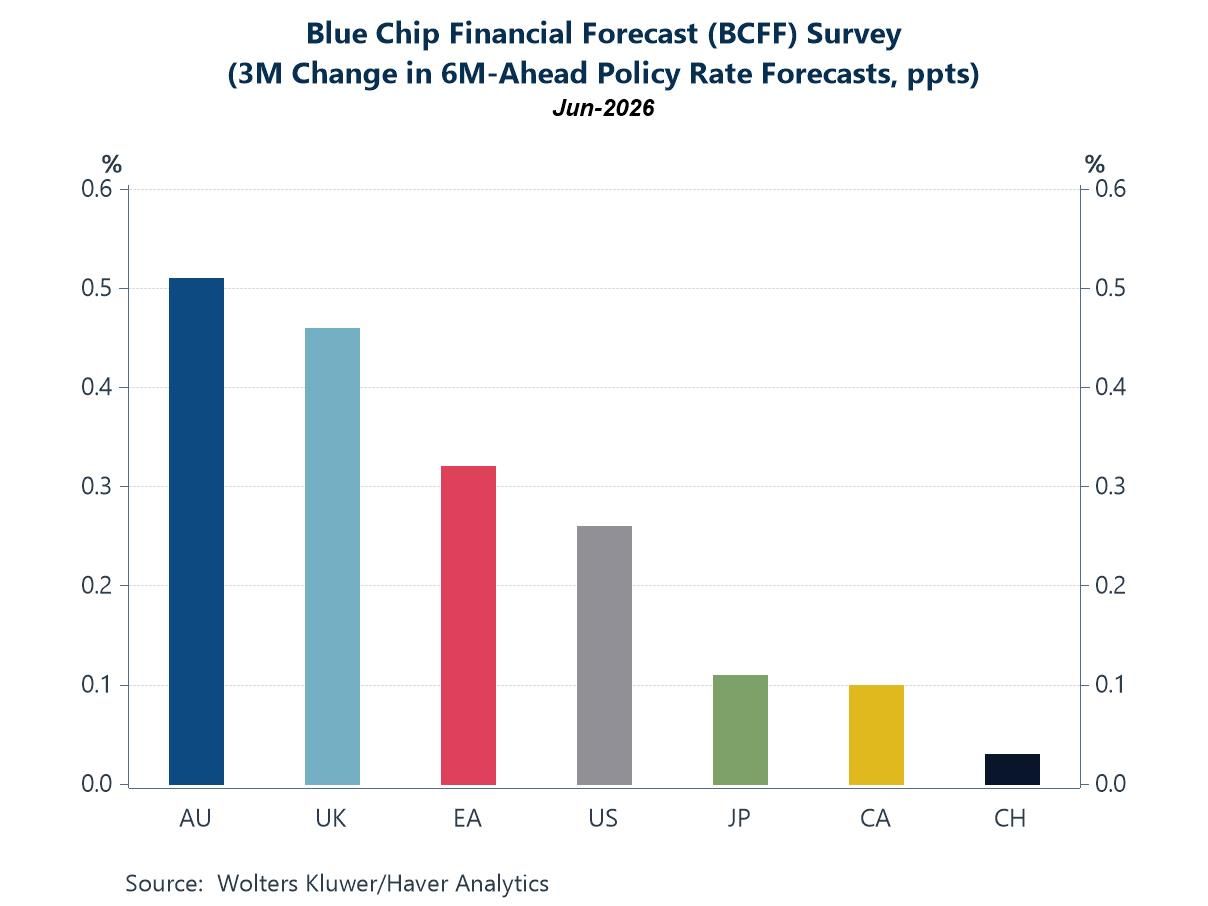
  • In this week’s Letter, we take stock of the latest Blue Chip Financial Forecast (BCFF) survey results and connect them with recent regional developments across Asia. Panellists have raised their policy rate forecasts relative to the pre–Middle East conflict baseline (chart 1), as inflation concerns intensify and several Asian central banks tighten policy (chart 2). Meanwhile, stronger US jobs data have strengthened the higher-for-longer rate narrative, tempering AI-driven equity gains in the US and Asia (chart 3).

    Turning to country specifics, the sharp rise in South Korean equities masks a more nuanced picture, where sustained foreign investor outflows have eventually weighed on the market and contributed to weakness in the South Korean won (chart 4). India has experienced a similar pattern, with a range of rupee supportive measures already introduced, although their effectiveness remains too early to assess (chart 5). Indonesia has likewise seen persistent foreign capital outflows alongside a weakening rupiah, with foreign participation in its government bond market declining to a worrying trickle (chart 6).

    Blue Chip Financial Forecast (BCFF) survey Looking at the latest Blue Chip Financial Forecast (BCFF) survey results, chart 1 shows that panellists have significantly revised upward their policy rate forecasts since the March survey (conducted at the end of February), reflecting the inflationary implications of the ongoing conflict in the Middle East and the continued closure of the Strait of Hormuz. Such revisions are understandable, as the disruption to one of the world's most important oil shipping routes has constrained global oil supply. With supply reduced while demand remains broadly unchanged, oil prices have risen sharply, feeding through to higher inflation and increasing the likelihood of further monetary policy tightening, or at the very least, a slower pace of policy easing. Among the economies covered by the survey, panellists have revised up their policy rate expectations for Australia by the largest margin, followed by the United Kingdom and the euro area.