

U.S. Wholesale Inventories Increase in September; Sales Jump
Summary
- Wholesale inventories +0.7% in Sept., eighth straight m/m gain; +7.6% y/y, highest y/y pace since March ’23.
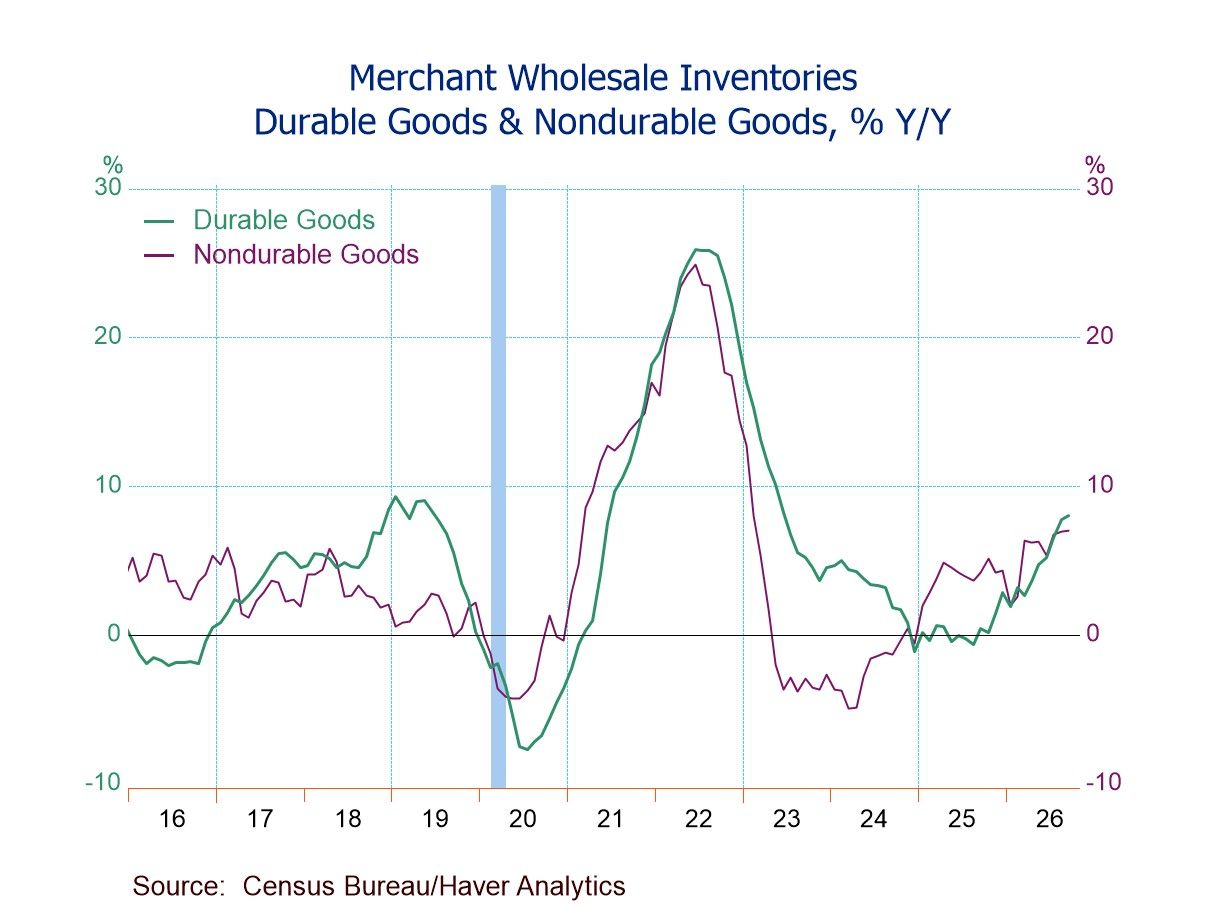
- Durable goods inventories +0.6% (+8.0% y/y), 11th consecutive m/m increase.
- Nondurable goods inventories +0.9% (+7.0% y/y), seventh m/m rise in eight mths.
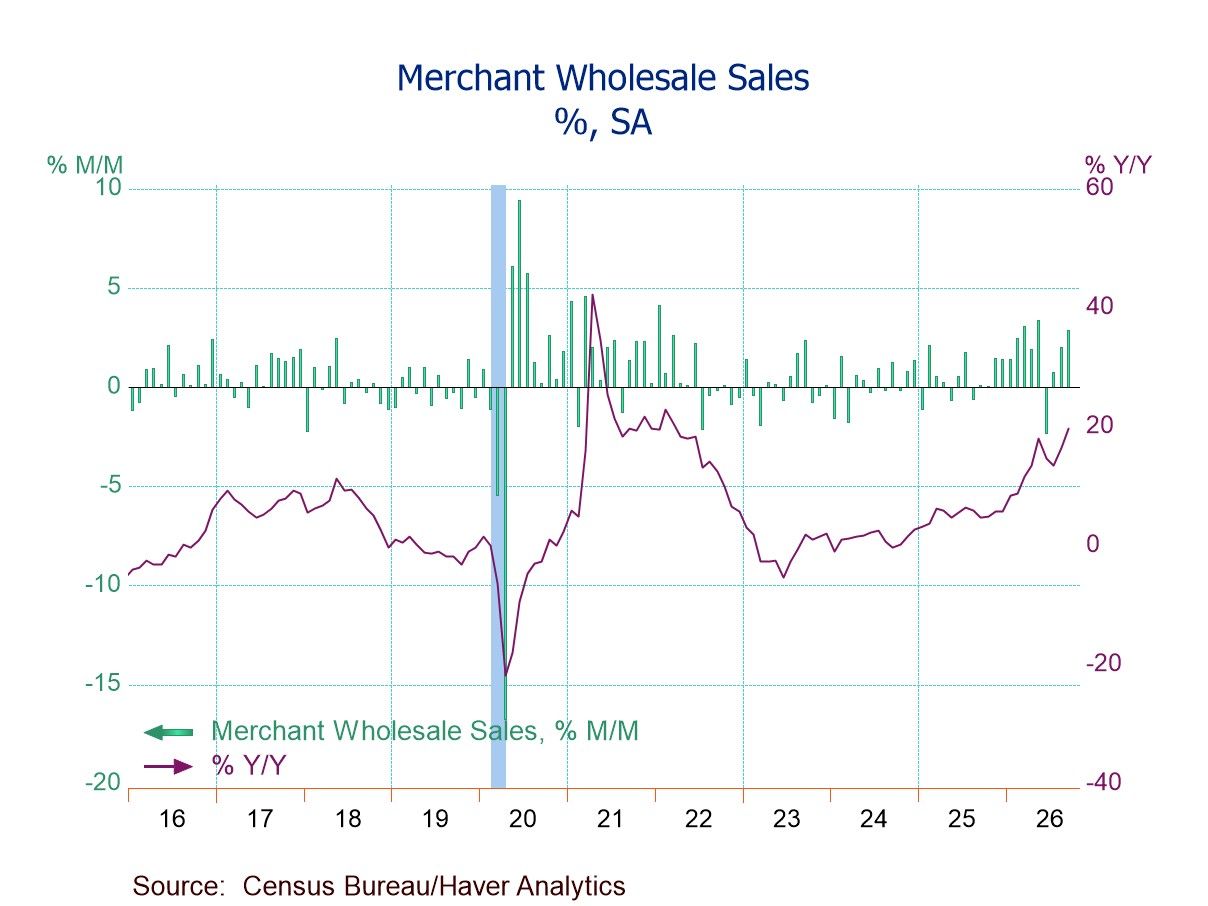
- Wholesale sales +2.8% (+19.8% y/y), 12th m/m gain in 13 mths., w/ durable goods sales up 1.3% and nondurable goods sales up 4.4%.
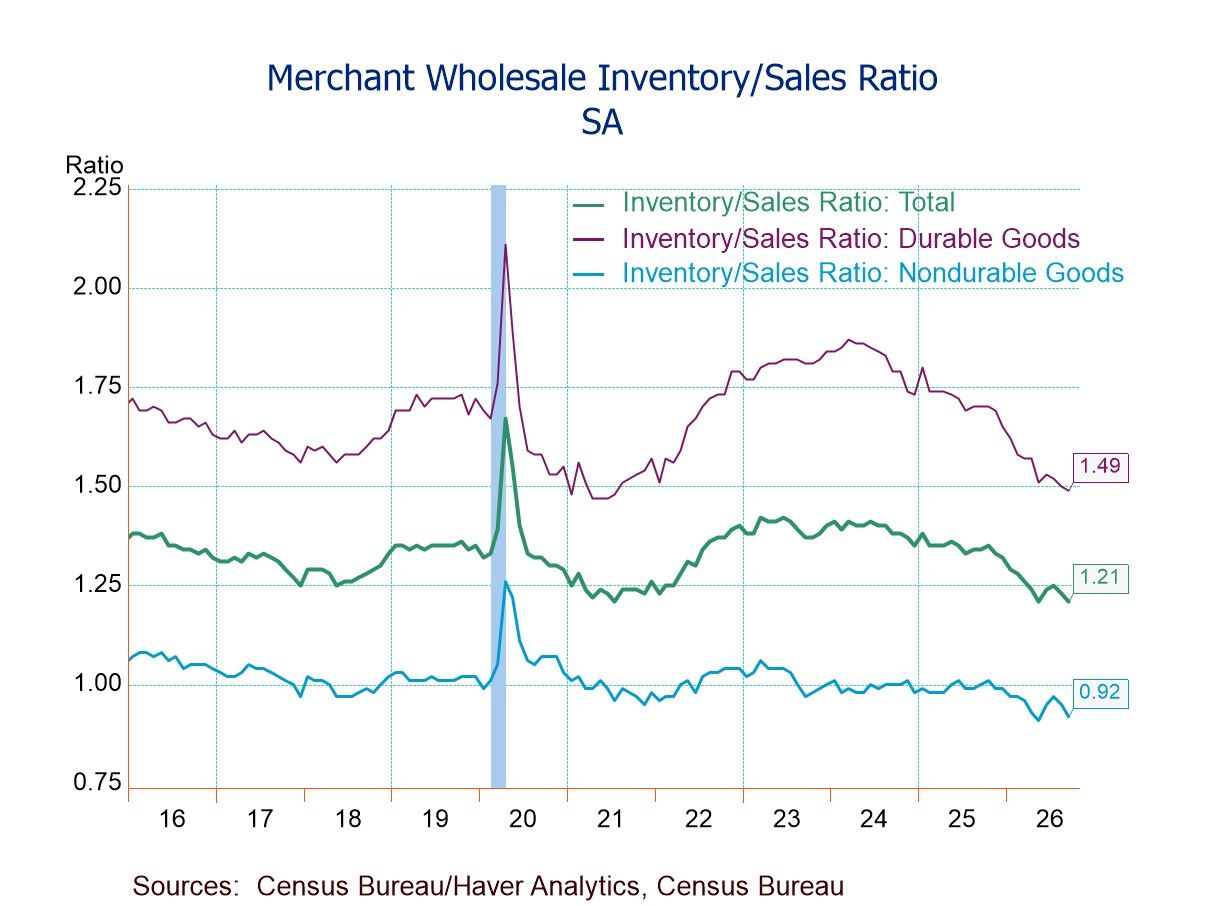
- I/S ratio down to 1.21, matching its lowest level since May.
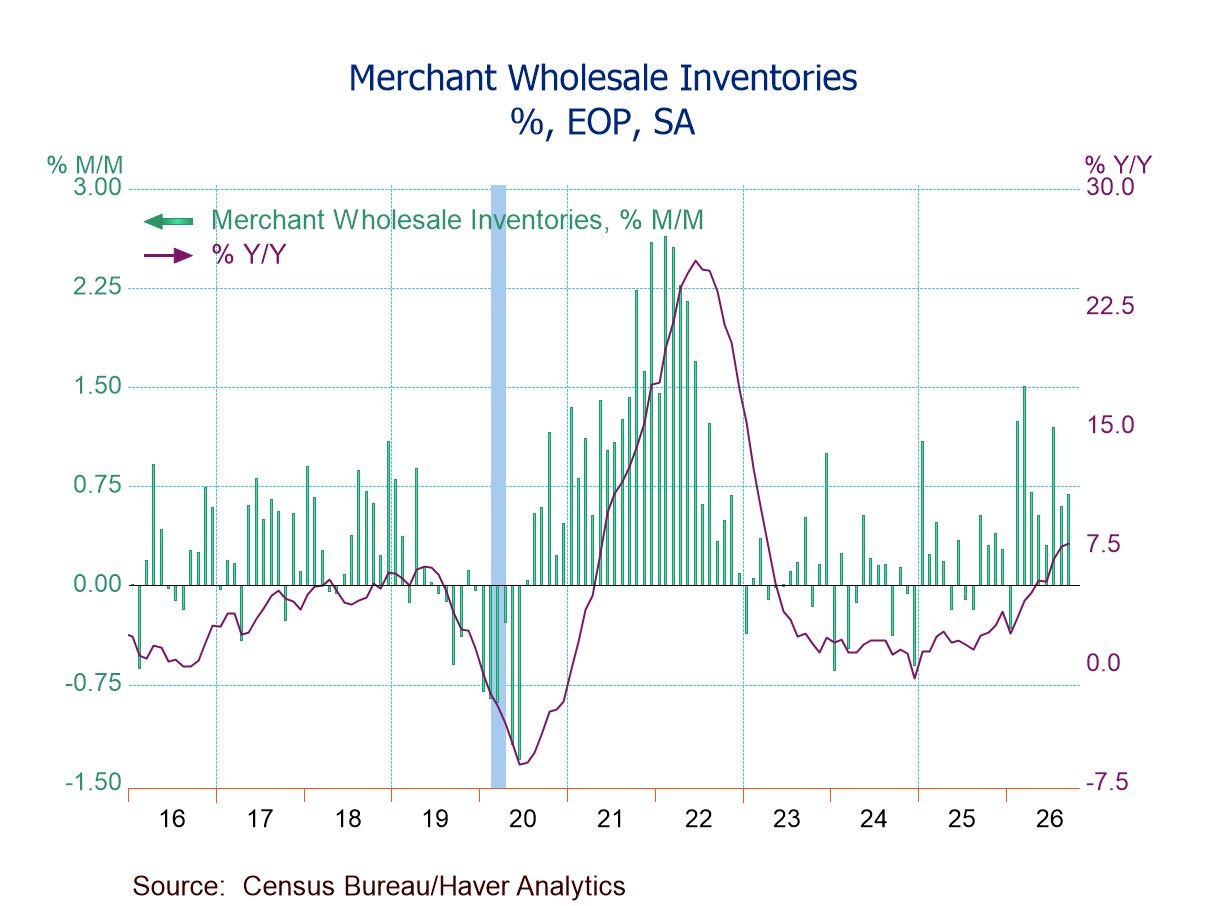
Wholesale inventories rose a slightly more-than-expected 0.7% (7.6% y/y) in September, the eighth straight m/m gain, after rises of 0.6% in August and 1.2% in July, indicating wholesalers continued to accumulate inventories at a solid pace. A 0.6% m/m September increase had been expected in the Informa Global Markets survey. The year-on-year rate rose to 7.6% in September, the 21st consecutive y/y rise and the fastest pace since March 2023, from 7.5% in August (1.8% in September 2025), remaining well above a low of -0.9% y/y in December 2024 but far below a peak of 25.5% y/y in June 2022.
Durable goods inventories grew 0.6% (8.0% y/y) in September, up for the 11th month running, after a 0.9% rise in August. The September m/m gain in durable goods inventories was led by a 2.5% advance (23.8% y/y) in electrical & electronic goods, followed by increases of 1.3% (4.5% y/y) in hardware, plumbing & heating equipment, 1.3% (4.6% y/y) in miscellaneous durable goods, 0.7% (4.1% y/y) in lumber & other construction materials, 0.5% (15.9% y/y) in professional & commercial equipment, and 0.4% (-2.4% y/y) in furniture & home furnishings. In contrast, durable goods wholesale inventories for metals & minerals (-0.9%; +2.7% y/y), motor vehicles & parts (-0.5%; +0.9% y/y), and machinery (-0.2%; +4.6% y/y) declined m/m in September.
Nondurable goods inventories climbed 0.9% (7.0% y/y) in September, the third successive m/m rise and the seventh in eight months, after a 0.1% uptick in August. The September m/m increase in nondurable goods inventories was driven by a 10.6% rebound (51.9% y/y) in petroleum & petroleum products, followed by rises of 2.6% (3.9% y/y) in apparel, 1.4% (2.7% y/y) in miscellaneous nondurable goods, 1.3% (9.1% y/y) in chemicals, 0.7% (0.6% y/y) in drugs, and 0.2% (4.6% y/y) in paper & paper products. To the downside, nondurable goods wholesale inventories for farm products (-7.4%; +18.9% y/y), alcoholic beverages (-1.8%; -3.3% y/y), and groceries (-0.8%; +1.5% y/y) fell m/m in September.
Wholesale sales jumped a larger-than-expected 2.8% (19.8% y/y) in September, the third straight m/m increase and the 12th in 13 months, on top of a 2.0% gain in August, indicating wholesale demand strengthened further. A 1.1% m/m September increase had been expected in the Action Economics Forecast Survey. Durable goods sales rose 1.3% (23.8% y/y) in September, the third consecutive m/m rise and the 10th in 11 months, after a 2.4% increase in August. The September m/m gain in durable goods sales was led by a 6.7% advance (37.5% y/y) in metals & minerals, followed by increases of 2.7% (19.8% y/y) in machinery, 2.6% (42.9% y/y) in electrical & electronic goods, 0.7% (19.5% y/y) in miscellaneous durable goods, and 0.2% (34.0% y/y) in professional & commercial equipment. In contrast, durable goods wholesale sales for motor vehicles & parts (-1.2%; +1.5% y/y), furniture & home furnishings (-1.0%; +12.5% y/y), hardware, plumbing & heating equipment (-0.5%; +6.8% y/y), and lumber & other construction materials (-0.1%; +6.6% y/y) decreased m/m in September.
Nondurable goods sales surged 4.4% (15.9% y/y) in September, the largest m/m gain since March, stronger than a 1.5% rebound in August. The September m/m increase in nondurable goods sales was driven by an 18.8% surge (62.8% y/y) in petroleum & petroleum products, followed by rises of 4.4% (26.5% y/y) in farm products, 2.3% (-2.6% y/y) in miscellaneous nondurable goods, 1.2% (19.0% y/y) in chemicals, 0.5% (-2.5% y/y) in alcoholic beverages, and 0.1% (2.4% y/y) in groceries. To the downside, nondurable goods wholesale sales for drugs (-1.5%; +4.7% y/y), paper & paper products (-0.8%; +4.9% y/y), and apparel (-0.6%; +1.3% y/y) fell m/m in September.
Wholesale sales outpaced inventory growth in September, pushing the inventory-to-sales ratio in the wholesale sector down to 1.21 in September, matching its lowest reading since May, from 1.23 in August (1.34 in September 2025); it was below a high of 1.42 in June 2023. The durable goods I/S ratio dipped to 1.49 in September, the lowest since July 2021, from 1.50 in August; it was below a high of 1.87 in March 2024. The durable goods I/S ratio ranged from 2.65 for machinery to 0.98 for electrical & electronic goods. The nondurable goods I/S ratio eased to 0.92 in September, the lowest since May, from 0.95 in August; it was below a high of 1.06 in March 2023. The nondurable goods I/S ratio ranged from 2.41 for apparel to 0.39 for petroleum & petroleum products.
The wholesale trade figures are available in Haver's USECON database. The expectations figure for inventories is contained in the MMSAMER database. Expectations for sales are from the AS1REPNA database.

Winnie Tapasanun
AuthorMore in Author Profile »Winnie Tapasanun has been working for Haver Analytics since 2013. She has 20+ years of working in the financial services industry. As Vice President and Economic Analyst at Globicus International, Inc., a New York-based company specializing in macroeconomics and financial markets, Winnie oversaw the company’s business operations, managed financial and economic data, and wrote daily reports on macroeconomics and financial markets. Prior to working at Globicus, she was Investment Promotion Officer at the New York Office of the Thailand Board of Investment (BOI) where she wrote monthly reports on the U.S. economic outlook, wrote reports on the outlook of key U.S. industries, and assisted investors on doing business and investment in Thailand. Prior to joining the BOI, she was Adjunct Professor teaching International Political Economy/International Relations at the City College of New York. Prior to her teaching experience at the CCNY, Winnie successfully completed internships at the United Nations. Winnie holds an MA Degree from Long Island University, New York. She also did graduate studies at Columbia University in the City of New York and doctoral requirements at the Graduate Center of the City University of New York. Her areas of specialization are international political economy, macroeconomics, financial markets, political economy, international relations, and business development/business strategy. Her regional specialization includes, but not limited to, Southeast Asia and East Asia. Winnie is bilingual in English and Thai with competency in French. She loves to travel (~30 countries) to better understand each country’s unique economy, fascinating culture and people as well as the global economy as a whole.
More Economy in Brief
 Global