U.S. ISM Manufacturing PMI at a Three-Month High in October; Production & New Orders Accelerating; Employment Moderating
Summary
- ISM Mfg. PMI up to 55.5 in Oct.; 10th straight month of expansion.
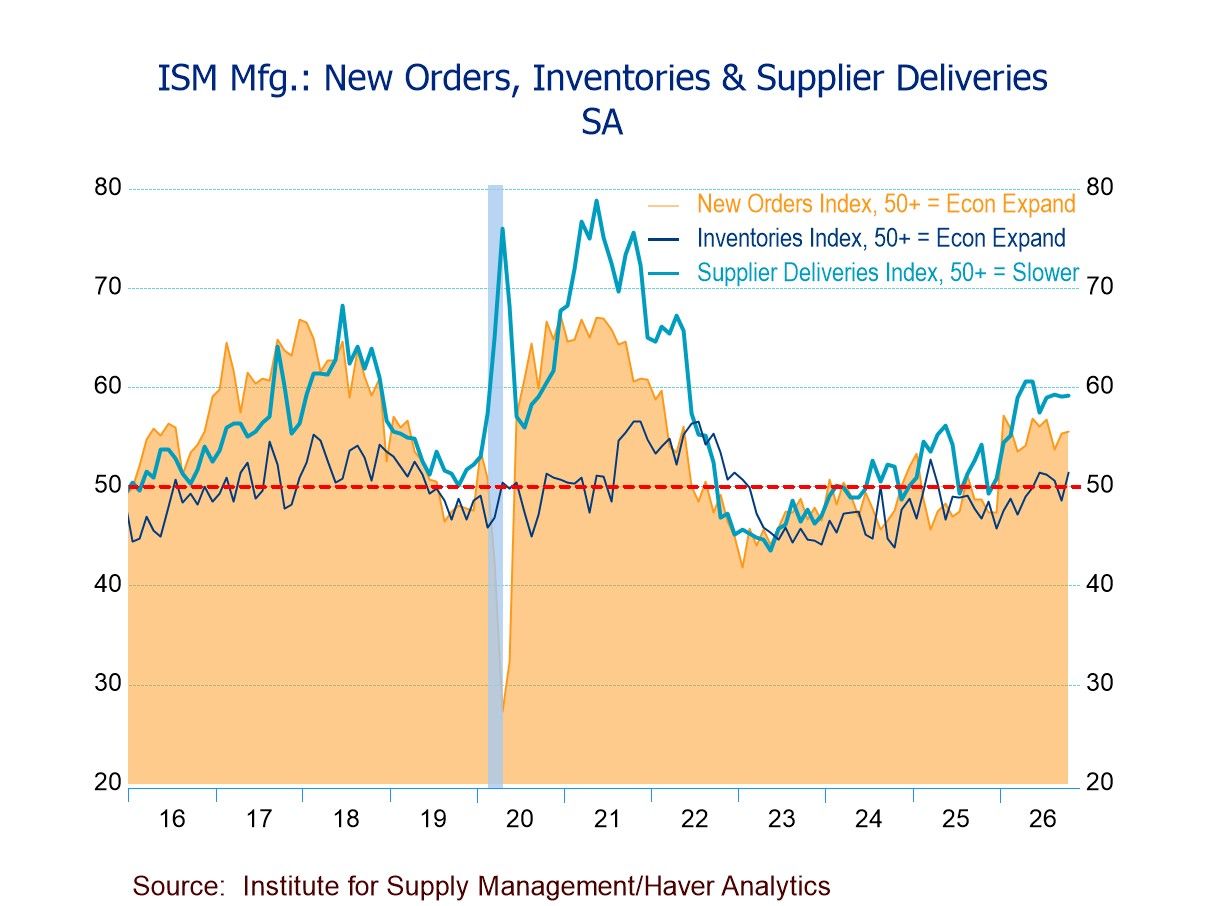
- Production (59.0) highest since Nov. ’21; expanding for the 12th consecutive mth.
- New orders (55.5) highest since July; 10th successive mth. above 50.
- Employment (52.4) expanding for the fourth straight mth., albeit at a slower rate.
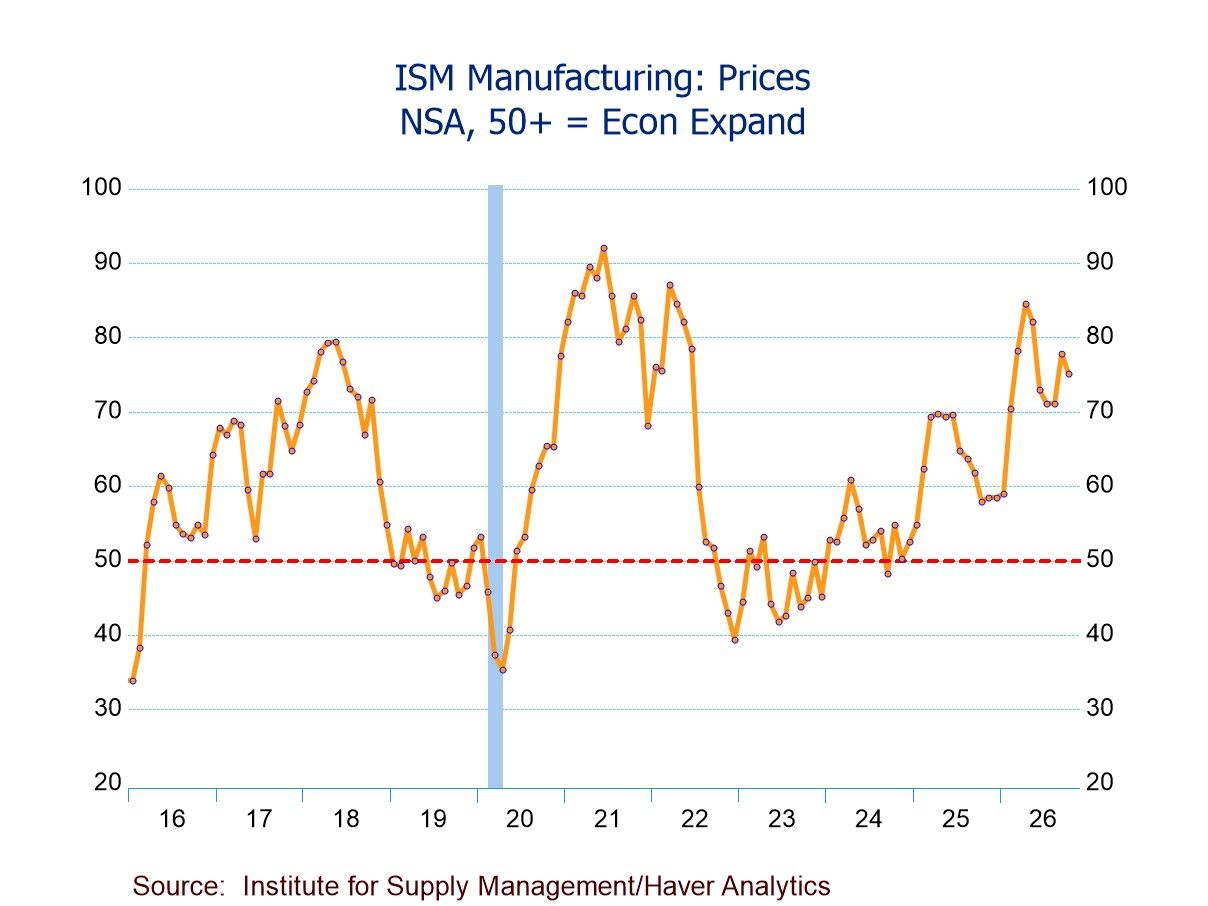
- Prices Index (75.2) down modestly, still indicating prices rising for 25 mths. running.
- Exports (51.2) up and imports (52.9) at a three-month high; both expanding.
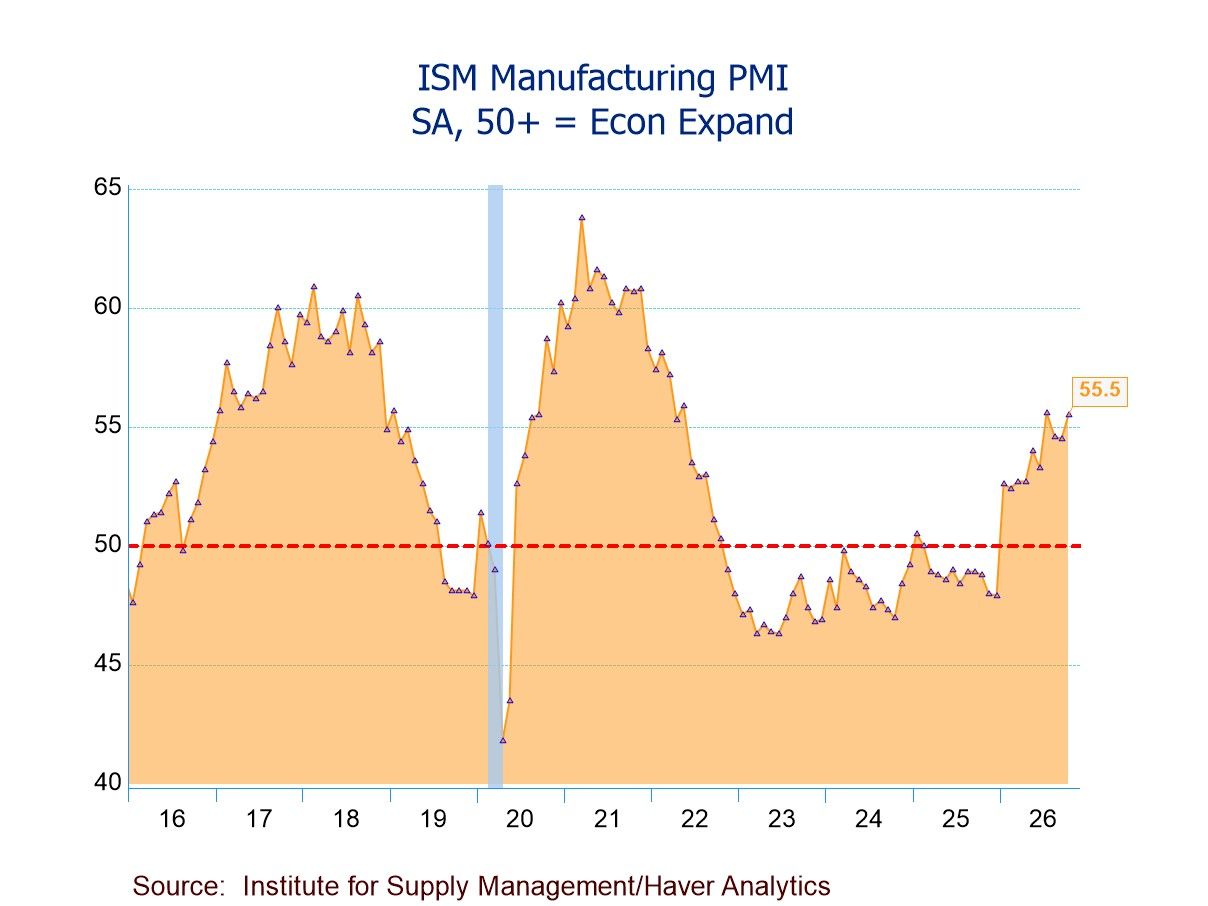
The ISM U.S. manufacturing PMI rose to a higher-than-expected 55.5 in October from 54.5 in September and 54.6 in August, according to data from the Institute for Supply Management. The October reading, above the 50 expansion-contraction threshold, indicated the U.S. manufacturing sector expanded for the 10th consecutive month and at the fastest pace since July. A reading of 54.7 for October had been expected in the Action Economics Forecast Survey. The latest manufacturing PMI was above a contractionary 48.8 in October 2025 and a low of 47.0 in October 2024, while remaining below a peak of 63.8 in March 2021.
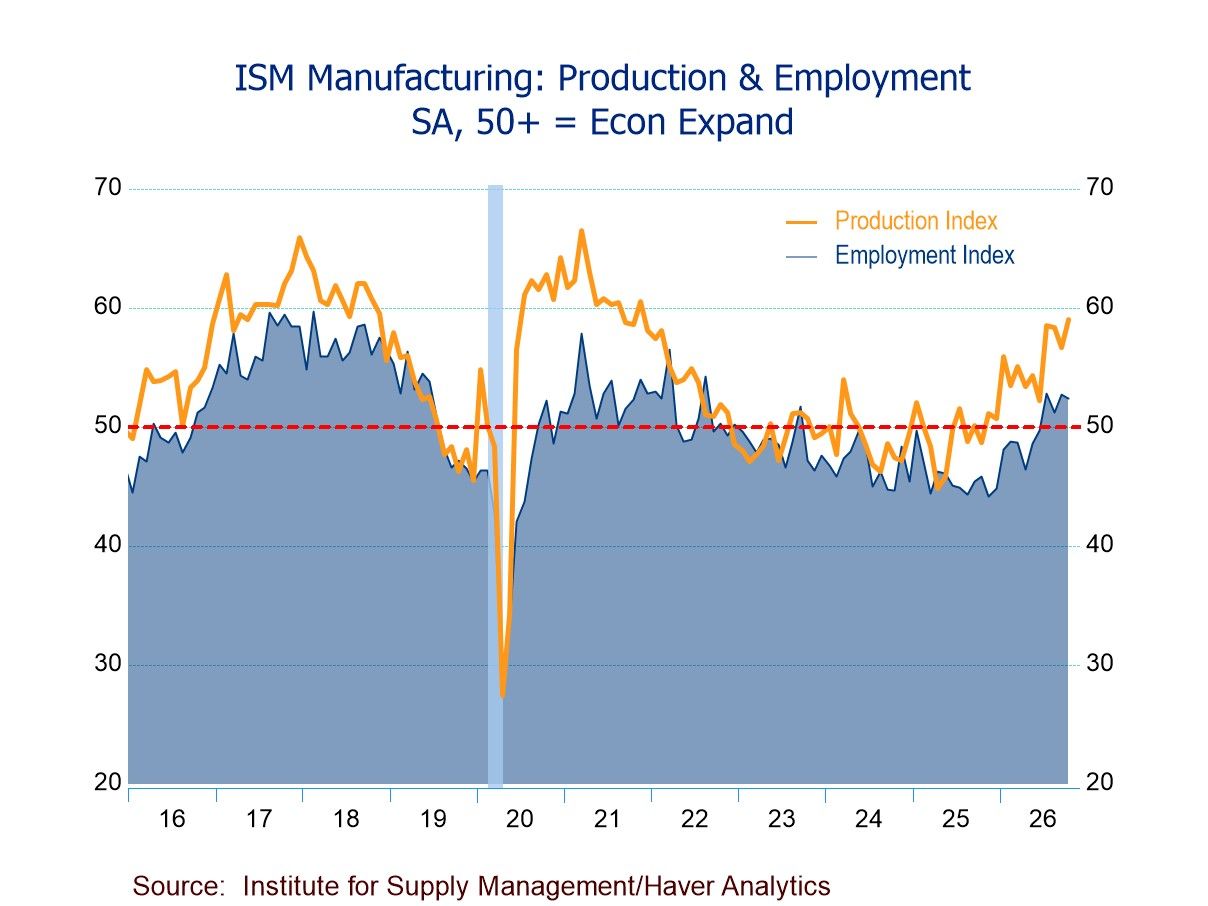
The production index advanced to 59.0 in October from 56.7 in September, indicating production expanded for the 12th straight month and at the highest level since November 2021. The index was above a low of 44.8 in April 2025 but below a peak of 66.5 in March 2021. In October, 27.6% (NSA) of respondents reported higher production while 11.5% reported lower production. The new orders index edged up to 55.5 in October from 55.3 in September, signaling new orders grew for the 10th successive month and at the fastest rate since July. The index remained well above a low of 41.8 in January 2023 but below a high of 67.0 in May 2021. In October, 24.2% (NSA) of respondents reported higher new orders while 16.9% reported declines. The inventories index rebounded to 51.4 in October from 48.6 in September, showing the fourth expansion in five months and matching the highest level since June. The index was below a high of 52.7 in March 2025 but above a low of 43.8 in October 2024. Meanwhile, the supplier deliveries index ticked up to 59.1 in October from 59.0 in September, indicating slowing delivery performance for the 11th straight month after faster deliveries in November 2025. In October, 21.2% (NSA) of respondents reported slower delivery speeds while 3.1% reported faster speeds.
On the labor front, the employment index slipped to 52.4 in October from 52.7 in September, showing employment expanded for the fourth consecutive month but at a slower pace, following 33 months of contraction. The index was above a low of 44.1 in November 2025 but below a high of 56.5 in March 2022. In October, 14.4% (NSA) of respondents reported higher employment while 10.8% reported lower hiring.
On the pricing front, the prices paid index declined to a still-elevated 75.2 (NSA) in October from 77.9 in September, indicating raw materials prices rose for 25 months running but at a slower rising pace. The index remained well above a low of 39.4 in December 2022 but below a high of 87.1 in March 2022 and a peak of 92.1 in June 2021. In October, 53.1% (NSA) of respondents reported higher prices while only 2.8% reported price declines.
In other ISM series not included in the composite index, the new export orders index rebounded to 51.2 in October from 50.9 in September, indicating new export orders grew for the fourth successive month and the fifth in six months. The index was up from a low of 40.1 in May 2025 but down from a peak of 57.1 in February 2022. The imports index rose to 52.9 in October from 51.0 in September, suggesting imports expanded for the ninth consecutive month and at the strongest rate since July. The index was above a low of 39.9 in May 2025 but below a peak of 61.0 in June 2021. The order backlog index slid to 54.6 (NSA) in October from 56.4 in September, showing backlog levels grew for the 10th straight month but at a slower pace. The index was well above a low of 37.5 in May 2023 but below a peak of 70.6 in May 2021.
The ISM figures are based on responses from over 400 purchasing and supply executives from 18 industries, which are weighted according to each industry’s contribution to GDP. These data are diffusion indexes where a reading above 50 indicates expansion; below 50 indicates contraction. The ISM Manufacturing PMI is a composite index based on the diffusion indexes of five of the indexes (seasonally adjusted) with equal weights: New Orders, Production, Employment, Supplier Deliveries, and Inventories. The figures from the Institute for Supply Management can be found in Haver’s USECON database; further detail is found in the SURVEYS database. The expectations number is available in Haver’s AS1REPNA database.

Winnie Tapasanun
AuthorMore in Author Profile »Winnie Tapasanun has been working for Haver Analytics since 2013. She has 20+ years of working in the financial services industry. As Vice President and Economic Analyst at Globicus International, Inc., a New York-based company specializing in macroeconomics and financial markets, Winnie oversaw the company’s business operations, managed financial and economic data, and wrote daily reports on macroeconomics and financial markets. Prior to working at Globicus, she was Investment Promotion Officer at the New York Office of the Thailand Board of Investment (BOI) where she wrote monthly reports on the U.S. economic outlook, wrote reports on the outlook of key U.S. industries, and assisted investors on doing business and investment in Thailand. Prior to joining the BOI, she was Adjunct Professor teaching International Political Economy/International Relations at the City College of New York. Prior to her teaching experience at the CCNY, Winnie successfully completed internships at the United Nations. Winnie holds an MA Degree from Long Island University, New York. She also did graduate studies at Columbia University in the City of New York and doctoral requirements at the Graduate Center of the City University of New York. Her areas of specialization are international political economy, macroeconomics, financial markets, political economy, international relations, and business development/business strategy. Her regional specialization includes, but not limited to, Southeast Asia and East Asia. Winnie is bilingual in English and Thai with competency in French. She loves to travel (~30 countries) to better understand each country’s unique economy, fascinating culture and people as well as the global economy as a whole.
More Economy in Brief
 Asia