Employment Cost Index: Unusually Steady Compensation Trend Reveals Slower Wage and Faster Benefit Cost Growth
Summary
- Compensation costs ease in Q3.
- Wage pressures at a five-year low.
- Benefit costs at a three-year high.


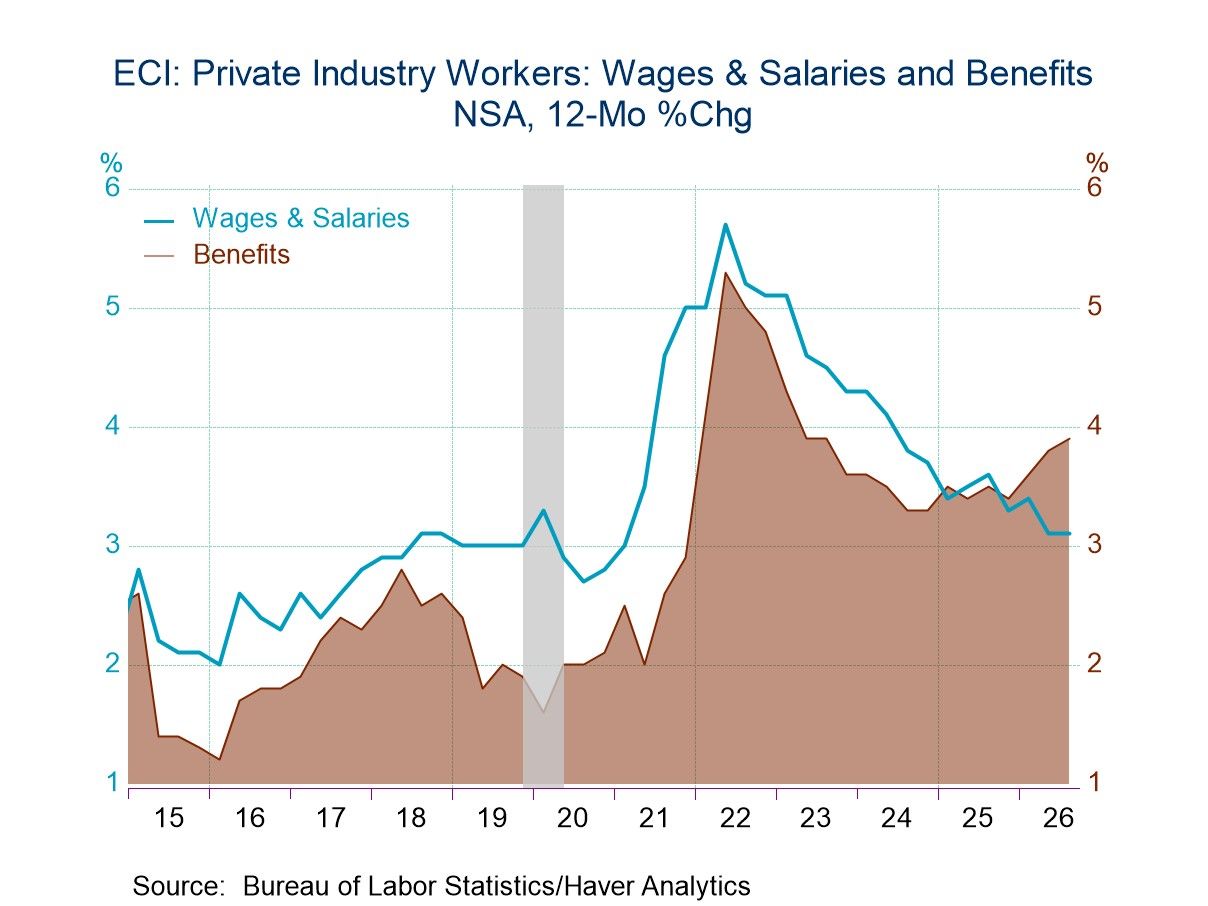
The U.S. Employment Cost Index (ECI) expanded at a slower 0.8% rate in the three months ended September, the softest quarterly pace since the fourth quarter of 2025 (0.7%). On a year-over-year (YoY) basis, compensation costs have been running at the same 3.4% figure for four consecutive quarters. The four-quarter stability in the annual trend is highly unusual for a cyclical indicator that oscillates with long-term wage cycles over time; it has occurred just 2% of the time since the 1982 inception of the series. A deeper dive beneath the headline ECI figure reveals persistently opposing paths for wages and benefits.
There is a trend divergence between ECI: Wages and Salaries and ECI: Benefits for all civilian workers. The former continued to grind down to 3.1% YoY in 2026’s third quarter, a fresh five-year low. The latter picked up to a 3.9% YoY rate, the highest in three years. Moreover, the Bureau of Labor Statistics’ (BLS) unpublished Health Benefits for Private Industry, a subset of ECI benefits, expanded at a 6.4% YoY pace, matching the 2025 fourth quarter’s 20-year high. The combination of higher benefit inflation and slower wage inflation shows an environment where employers’ management of compensation costs is falling directly on employees.
The details for the private sector are similar to that for all civilian workers. Private ECI: Compensation costs edged up to a 3.4% YoY figure in the third quarter. This marked the first uptick in the YoY compensation trend in five quarters. It was not due to higher wage pressures, though. Private ECI: Wages and Salaries was steady at a 3.1% YoY rate, the lowest since 2021’s first quarter. Private ECI: Benefits advanced to 3.9% YoY, the highest since 2023’s third quarter.
The spread between Private ECI: Wages and Private ECI: Benefits illustrates private sector profit pressure. In the second quarter, the -0.8-percentage point spread was the lowest in 14 years. Benefit costs are determined by market forces and are an expense beyond any private companies’ control. Wages and salaries, on the other hand, are an important line item completely under the purview of C-suite executives. The easing in private wage pressures suggests that firms are opting to trim one cost at the expense of another. From private workers’ perspective, the higher benefit/lower wage growth results in faster growth for paychecks, but slower growth for take-home pay.
The BLS report also has an alternative way to observe vacillating pressures on consumer purchasing power with “real” inflation-adjusted measures. To that end, consumers’ purchasing power loss in 2026’s third quarter, measured by the Real ECI: Wages and Salaries, amounted to a -0.6% YoY decline. This was the weakest since 2012’s first quarter (-0.9% YoY). The 14-year low also echoed other periods of economic stress during the Great Recession and the 2000s Housing Bust.
Lack of forward momentum from the Real ECI: Wages and Salaries fundamentally does not support an accelerating profile for Real Consumer Spending over the near term. To that end, this week’s Income and Spending report indicated a September stall in Real Consumer Spending at the same time that Real Income metrics – personal income less transfer and disposable personal income – posted the first monthly declines in five months.
The employment cost index measures the change in the cost of labor, free from the influence of employment shifts across occupations and industries. It is provided by the Bureau of Labor Statistics and is available in Haver’s USECON database. Consensus estimates from the Action Economics Forecast Survey are in Haver’s AS1REPNA database.

Jonathan Basile
AuthorMore in Author Profile »Jonathan Basile is Street veteran of more than three decades with extensive experience analyzing the global macro environment from the perspectives of sell-side economist, sovereign analyst, and buy-side strategist. He joined Danielle DiMartino Booth at Quill Intelligence in June 2025 as Director of Research where he regularly taps his assets for the firm’s key products, Weekly Quill, Saturday Intelligence Briefing, and Daily Feather.
The prior 11 years were spent at AIG’s and Corebridge Financial’s Investment arms as Head of Global Macro Strategy where his macro and market knowledge were utilized by key stakeholders, like the CIO teams, portfolio managers and third-party clients. Before the Corebridge spin-off from AIG, he built the Global Macro desk from scratch to become an integral part of the active investment process. He streamlined investment practices by steering a centralized monthly global macro discussion allowing subsequent asset-class meetings to be focused on strategy. Jonathan’s tactical rate views were frequently employed by public credit portfolio managers and traders. His storytelling prowess was displayed in a colorful weekly rant whose internal distribution grew steadily and organically.
Jonathan’s past experience with the likes of Dr. Lacy Hunt, Christopher Low, Ian Shepherdson, Elliott Platt, Dr. Neal Soss, and Kathleen Stephansen (twice) prepared him for almost anything thrown his way from the economy and the markets. His years at HSBC, DLJ and Credit Suisse combined saw him cover the economies of the US, Canada, Japan and the UK. He has been recognized as a four-time winning team member of the Marketwatch US Forecaster of the Month and was ranked by Bloomberg as a top forecaster of the Canadian economy.
Jonathan is married with three children – one of which is a Red Sox fan in a Yankees household. You can find Jonathan running or biking on weekends or catching for his men’s baseball team during the spring and summer. He holds a BA in Economics from Princeton University.
More Economy in Brief
 Global