U.S. Industrial Production Flat in August; Manufacturing IP Down
Summary
- August IP 0.0% (+1.4% y/y) after four consecutive m/m increases, remaining on an upward trend.
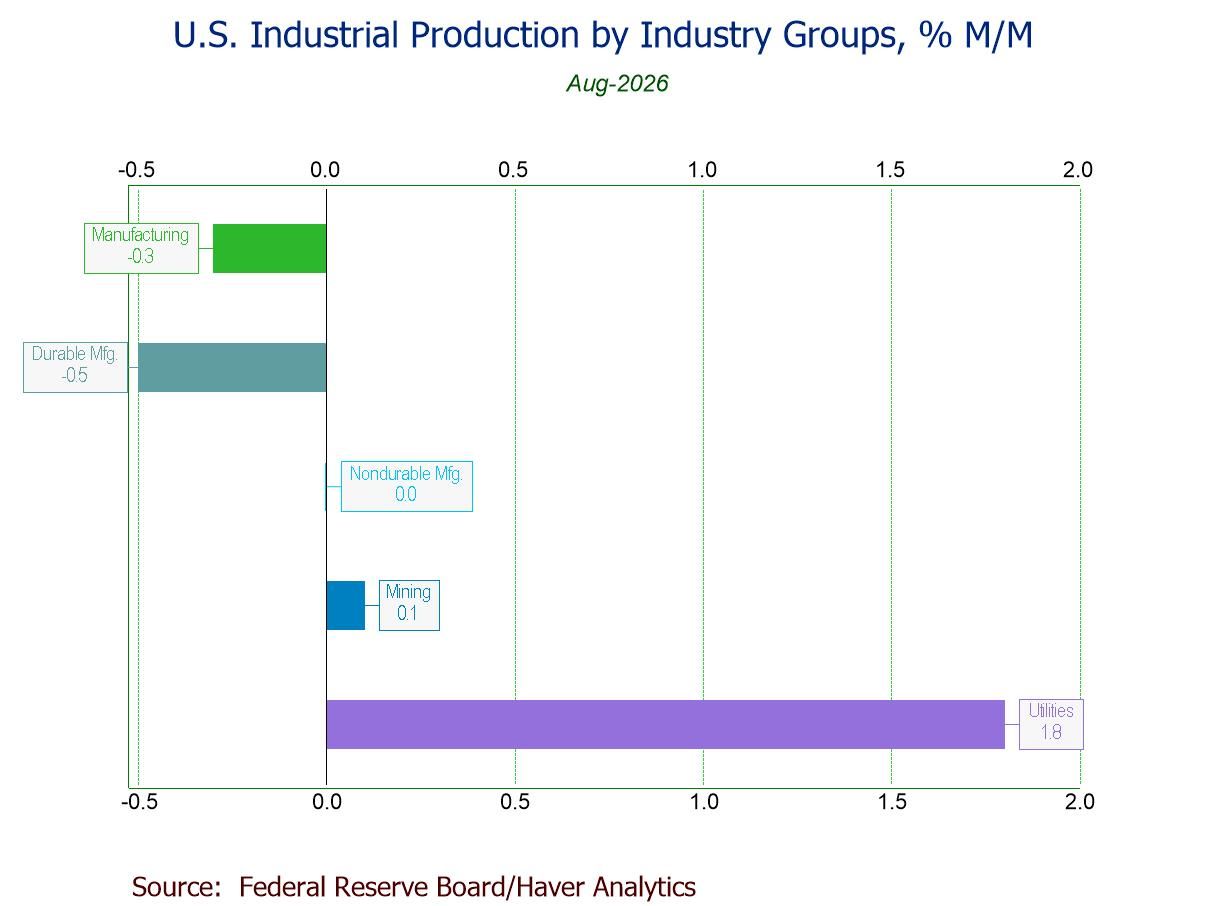
- Manufacturing -0.3% (+0.9% y/y), first m/m decline since Dec., w/ durables -0.5% and nondurables 0.0%.
- Selected high-tech 0.0% after four straight m/m rises; motor vehicles -1.2%, second successive m/m drop.
- Utilities +1.8% (+6.2% y/y), fourth rise in five mths., led by a 2.1% gain in electric utilities output.
- Mining +0.1% (+0.3% y/y), up for the fourth time in five mths.
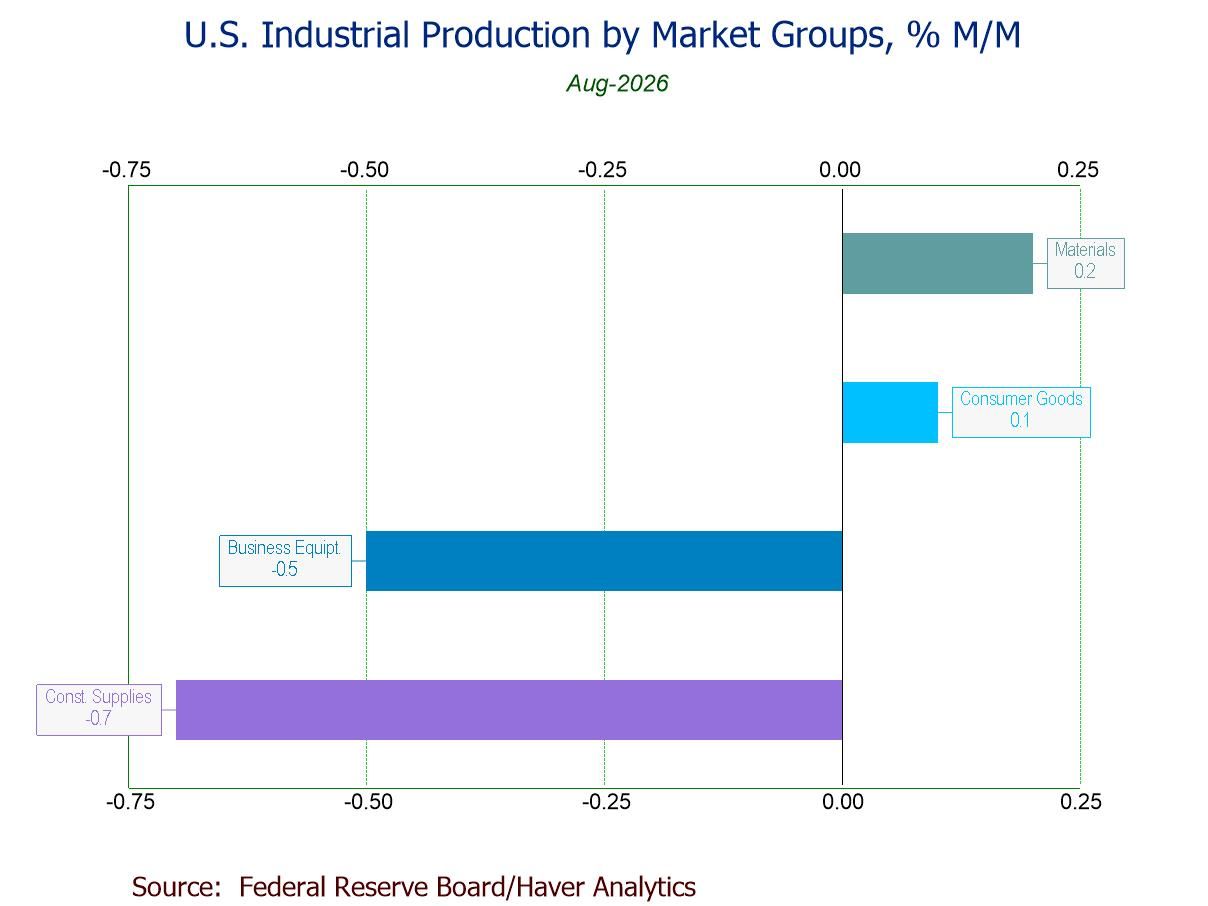
- Key categories in market groups post mixed results.
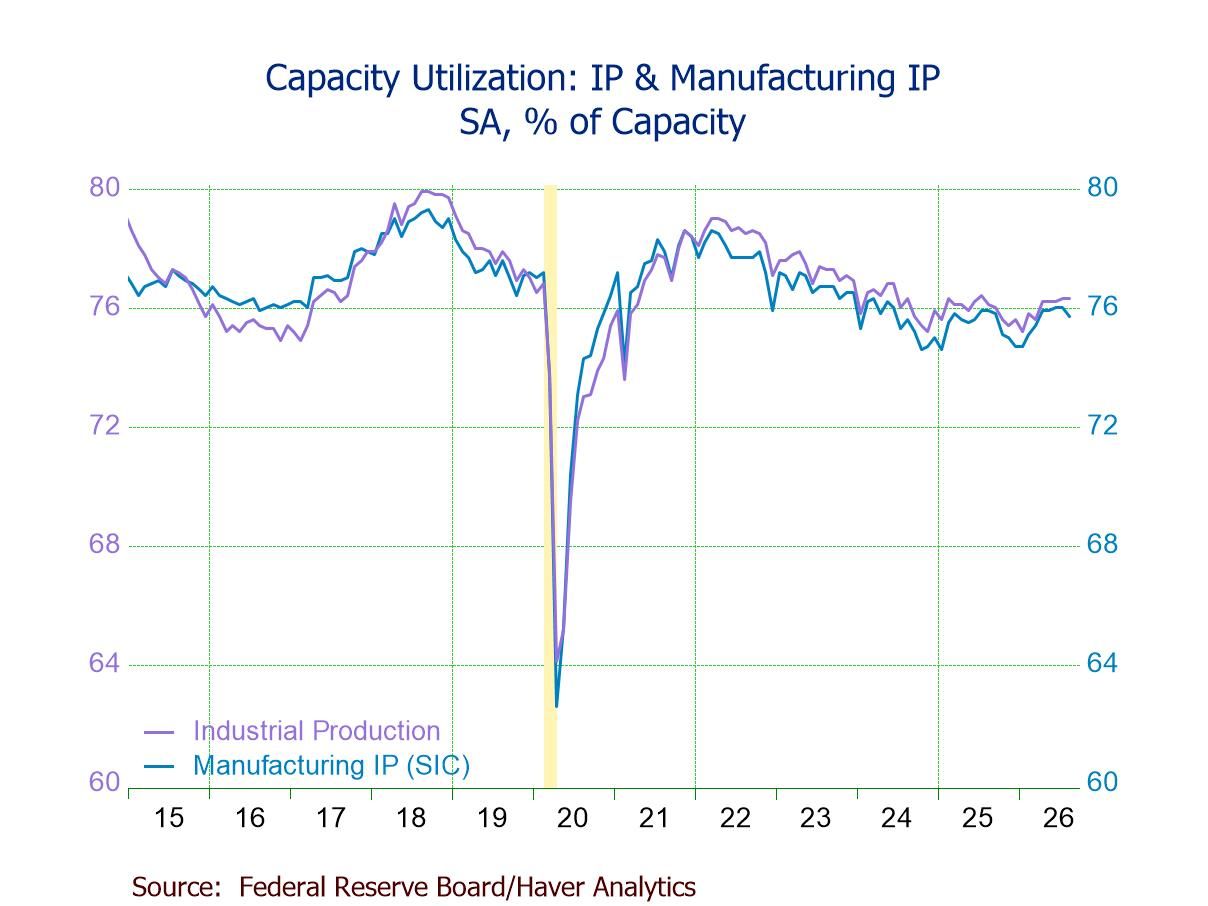
- Capacity utilization steady at 76.3%, highest since July ’25; mfg. capacity utilization down to 75.7%, lowest since March.
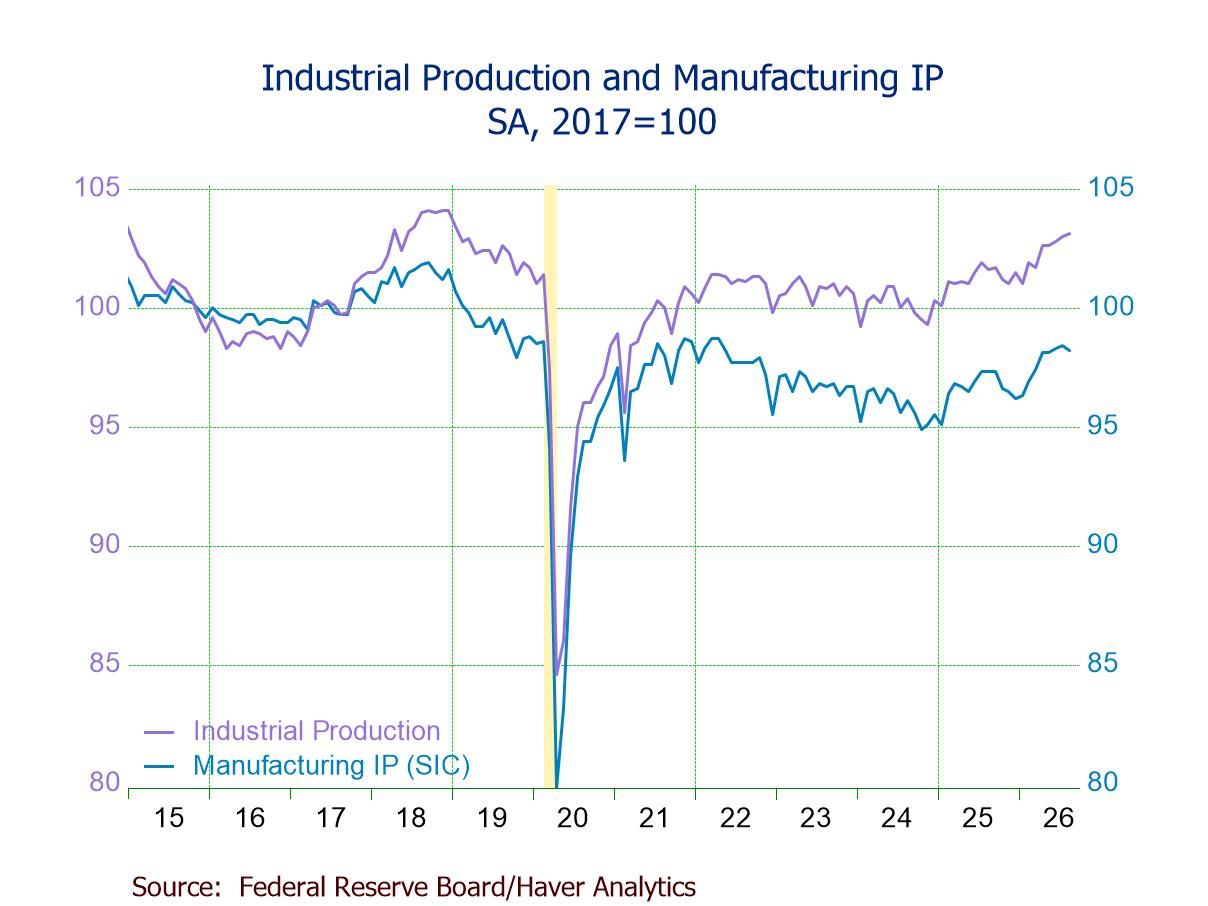
Industrial production (IP) was virtually unchanged m/m in August after rises of 0.2% in July (unrevised) and 0.2% in June (+0.3% previously), data from the Federal Reserve Board showed, indicating industrial activity remained on an upward trend despite little change in the latest month. A 0.3% m/m August increase had been expected in the Action Economics Forecast Survey. The year-on-year growth rate accelerated to 1.4% in August, the highest since May, from 1.1% in July (0.8% in August 2025). The August IP index at 103.1 was 3.8% above a low of 99.3 in November 2024 and 3.9% above a low of 99.2 in January 2024.
By industry groups, manufacturing production decreased 0.3% (+0.9% y/y) in August, the first m/m decline since December, after increases of 0.2% in July (unrevised) and 0.1% in June (+0.3% previously). Durable goods production fell 0.5% (+3.3% y/y) in August, down for the first time since November 2025, following a 0.6% rise in July. Within durables, almost all categories fell m/m in August, led by drops of 1.4% (-2.8% y/y) in furniture & related products and 1.4% (+0.7% y/y) in miscellaneous durable goods, followed by declines of 1.2% (+4.2% y/y) in aerospace & miscellaneous transportation equipment, 1.2% (-1.0% y/y) in motor vehicles & parts, 1.1% (+2.8% y/y) in nonmetallic mineral products, 0.5% (+8.7% y/y) in computer & electronic products, 0.3% (+0.5% y/y) in primary metals, and 0.1% (+3.6% y/y) in fabricated metal products. Notably, aircraft & parts production slid 1.4% (+7.7% y/y), the first m/m slide since January, after a 1.7% July gain. To the upside, durable goods categories for machinery (+0.5%; +6.3% y/y) and wood products (+0.2%; -0.7% y/y) posted m/m output gains in August. Durable goods for electrical equipment, appliances & components held steady m/m (+5.5% y/y) following a 0.4% July rebound.
Nondurable goods production was essentially unchanged m/m (-1.5% y/y) in August following a 0.4% decrease in July and a 0.4% rebound in June. The August flat reading reflected m/m falls of 1.0% (-4.8% y/y) in printing & related support activities, 0.9% (+0.8% y/y) in plastics & rubber products, 0.7% (+0.8% y/y) in petroleum & coal products, and 0.2% (-2.9% y/y) in paper. Meanwhile, nondurable goods categories for apparel & leather goods (+2.1%; +3.6% y/y), textiles & product mills (+1.3%; -0.1% y/y), and food, beverages & tobacco (+0.3%; -1.2% y/y) registered m/m output gains in August; output for chemicals held steady m/m (-2.6% y/y) following a 0.3% July decline.
Utilities output advanced 1.8% (6.2% y/y) in August on top of a 0.5% increase in July (unrevised), reflecting a 2.1% rise (7.0% y/y) in electric utilities output and a 0.5% decrease (+0.8% y/y) in natural gas utilities output. Mining activity edged up 0.1% (0.3% y/y) after a 0.1% July uptick (+0.2% initially). The utilities and mining series posted the third consecutive m/m gain and the fourth in five months, while recording May flat readings.
By market groups, materials production grew 0.2% (1.5% y/y) in August, the fourth m/m gain in five months, adding to a 0.3% rise in July. Consumer goods output ticked up 0.1% (-1.1% y/y) following a 0.3% July decrease, reflecting a 0.5% decline (-3.7% y/y) in durable consumer goods and a 0.3% increase (-0.4% y/y) in nondurable consumer goods. In contrast, construction supplies production fell 0.7% (+1.3% y/y), the first m/m fall since April, after a 0.5% July gain. Business equipment output slid 0.5% (+7.1% y/y) in August, the first m/m drop since October 2025, following a 1.0% July rise.
In special classifications, factory output of selected high-tech industries was virtually unchanged m/m (+12.5% y/y) in August after four straight m/m gains, including a 1.3% increase in July. Manufacturing production excluding selected high-tech industries fell 0.3% (+0.5% y/y) in August, the first m/m decline since January, after a 0.1% increase in July. Manufacturing production excluding selected high-tech and motor vehicles & parts slipped 0.2% (+0.7% y/y), down for the first time since May, reversing a 0.2% July gain.
Capacity utilization was at 76.3% in August, the highest since July 2025, unchanged from July (unrevised). The Action Economics Forecast Survey forecasted 76.4%. The August reading was 3.1 percentage points below its long-run (1972–2025) average. Manufacturing capacity utilization fell to 75.7% in August, the lowest since March, from 76.0% in July (unrevised). The August rate was 2.5 percentage points below its long-run average.
Industrial production and capacity data are in Haver’s USECON database. Additional detail on production and capacity utilization can be found in the IP database. The expectations figures come from the AS1REPNA database.

Winnie Tapasanun
AuthorMore in Author Profile »Winnie Tapasanun has been working for Haver Analytics since 2013. She has 20+ years of working in the financial services industry. As Vice President and Economic Analyst at Globicus International, Inc., a New York-based company specializing in macroeconomics and financial markets, Winnie oversaw the company’s business operations, managed financial and economic data, and wrote daily reports on macroeconomics and financial markets. Prior to working at Globicus, she was Investment Promotion Officer at the New York Office of the Thailand Board of Investment (BOI) where she wrote monthly reports on the U.S. economic outlook, wrote reports on the outlook of key U.S. industries, and assisted investors on doing business and investment in Thailand. Prior to joining the BOI, she was Adjunct Professor teaching International Political Economy/International Relations at the City College of New York. Prior to her teaching experience at the CCNY, Winnie successfully completed internships at the United Nations. Winnie holds an MA Degree from Long Island University, New York. She also did graduate studies at Columbia University in the City of New York and doctoral requirements at the Graduate Center of the City University of New York. Her areas of specialization are international political economy, macroeconomics, financial markets, political economy, international relations, and business development/business strategy. Her regional specialization includes, but not limited to, Southeast Asia and East Asia. Winnie is bilingual in English and Thai with competency in French. She loves to travel (~30 countries) to better understand each country’s unique economy, fascinating culture and people as well as the global economy as a whole.
More Economy in Brief
 Global