Total U.S. Retail Sales Slowed in October but Details Were Strong
by:Sandy Batten
|in:Economy in Brief
Summary
- Total retail sales increased 0.2% m/m in October, in line with expectations but meaningfully slower than in August and September.
- However, the underlying details were stronger with significant upward revisions.
- Even with the modest rise in October, consumer spending is off to a solid start for Q4 given the strong gains in August and September.
- Control-group sales (used to construct PCE in the NIPAs) rose 0.6% m/m in October on top of upwardly revised gains in August and September.
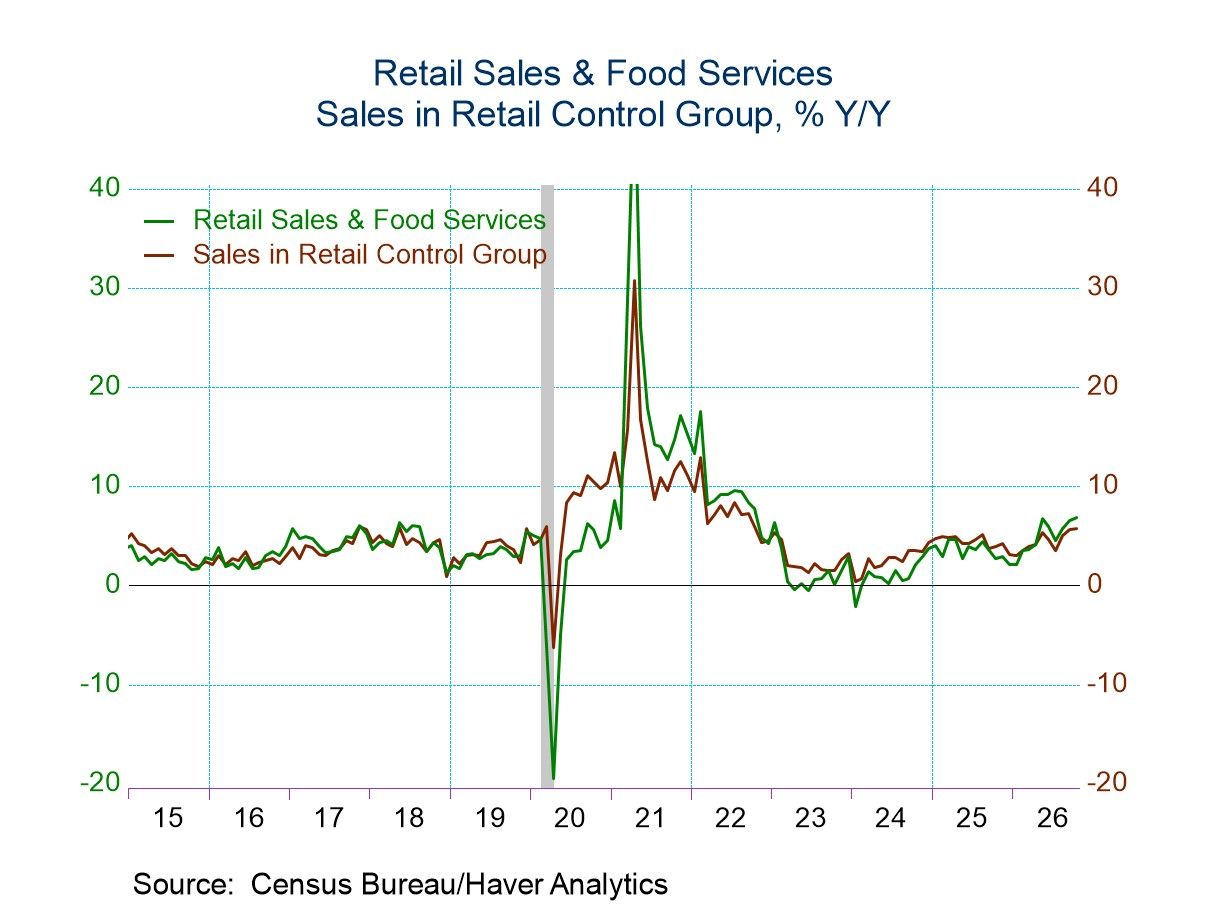
Total retail sales rose 0.2% m/m (+6.8% y/y) in October following an unrevised 0.8% monthly gain in September and an upwardly revised 1.5% m/m increase in August (previously 1.3% m/m), according to data released by the U.S. Census Bureau. The Action Economics Forecast Survey looked for a 0.2% monthly gain. Sales excluding autos were up 0.6% m/m (+8.1% y/y) in October versus 1.1% m/m in September (revised up from 0.9% m/m) and 1.6% m/m in August (revised up from 1.4% m/m). Expectations were for a 0.4% m/m increase in ex auto sales in October. Over the three months to October, sale ex autos have risen 3.4%.
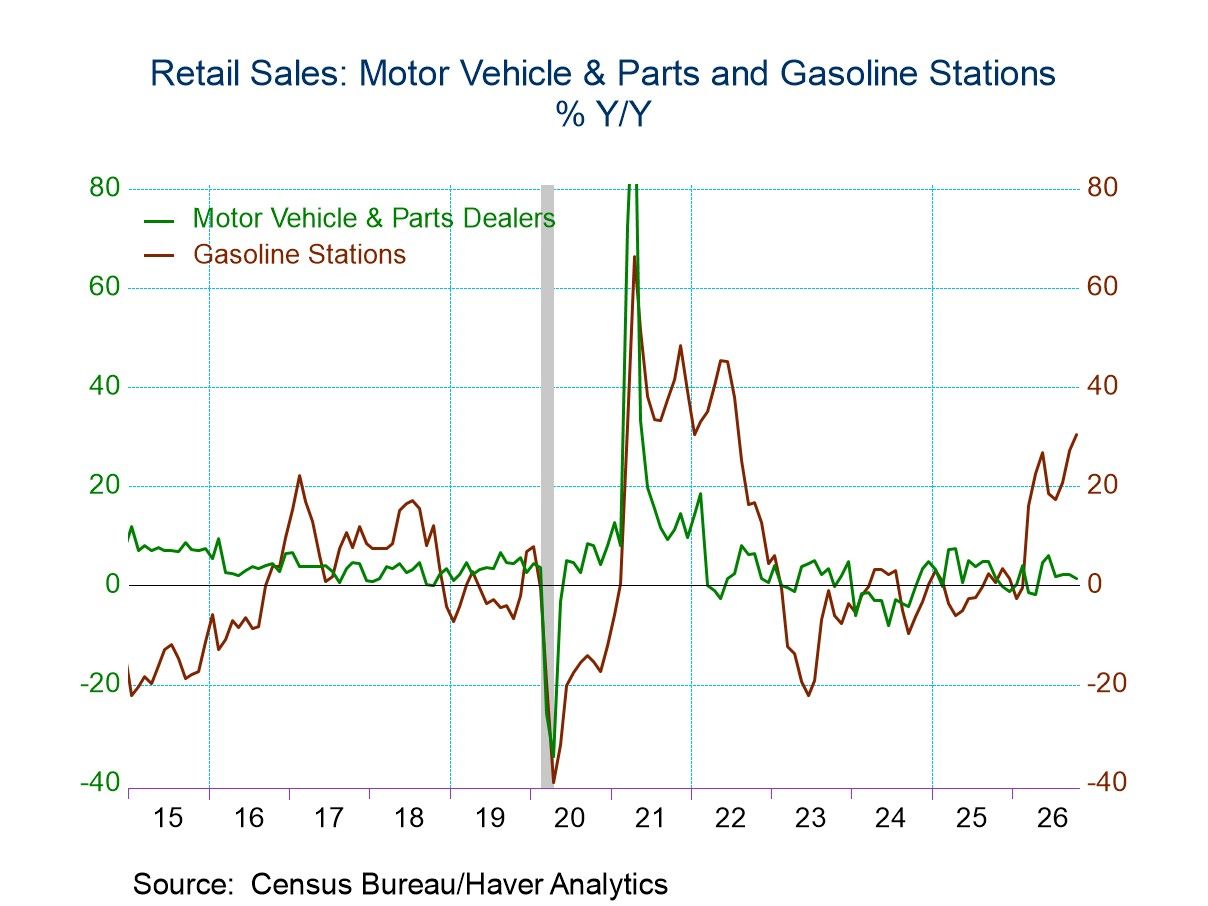
Retail gasoline prices rose further in October though at a slower pace than in August and September. Accordingly, retail sales at gasoline stations slowed, rising 1.5% m/m in October versus a 6.0% monthly gain in September and a 3.7% m/m increase in August. Sales excluding gasoline edged up 0.1% m/m in October versus 0.3% m/m in September while sales excluding gasoline and autos increased a solid 0.5% m/m, the same monthly gain as in September.
Control-group sales were also robust. The control group is the part of retail sales that flows directly into the calculation of personal consumption in the NIPAs. These sales increased 0.6% m/m (5.7% y/y) in October on top of upwardly revised gains of 0.5% m/m in September (previously +0.1% m/m) and 1.6% m/m in August (previously +1.4% m/m). Over the past three months, control-group sales have risen 2.7%. The October level of control-group sales is 8.9% annualized above the Q3 average, pointing to another quarter of solid consumer spending in the national accounts. Personal consumption expenditures increased 3.8% q/q saar in Q3 (adding 2.5%-points to overall real GDP growth) and is on course to another strong increase in Q4.
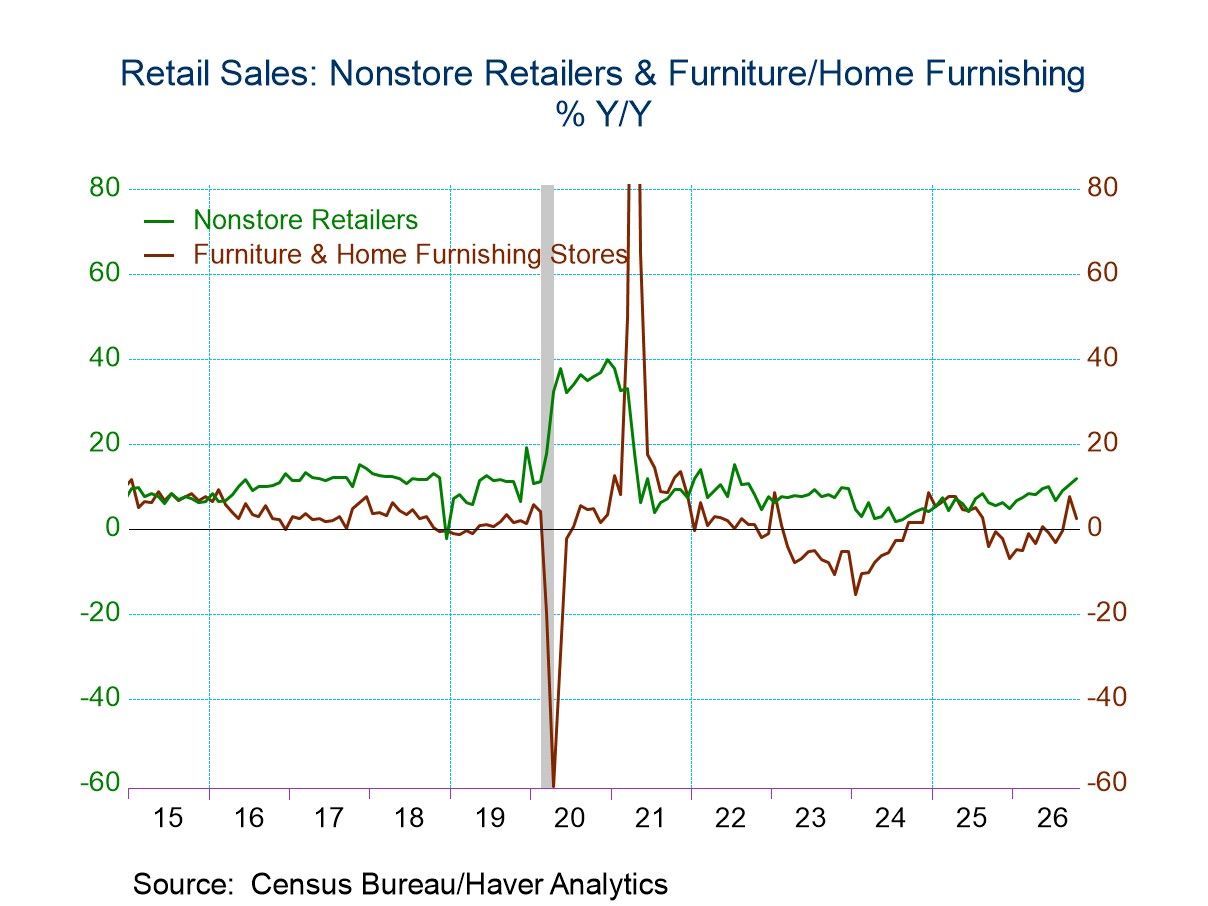
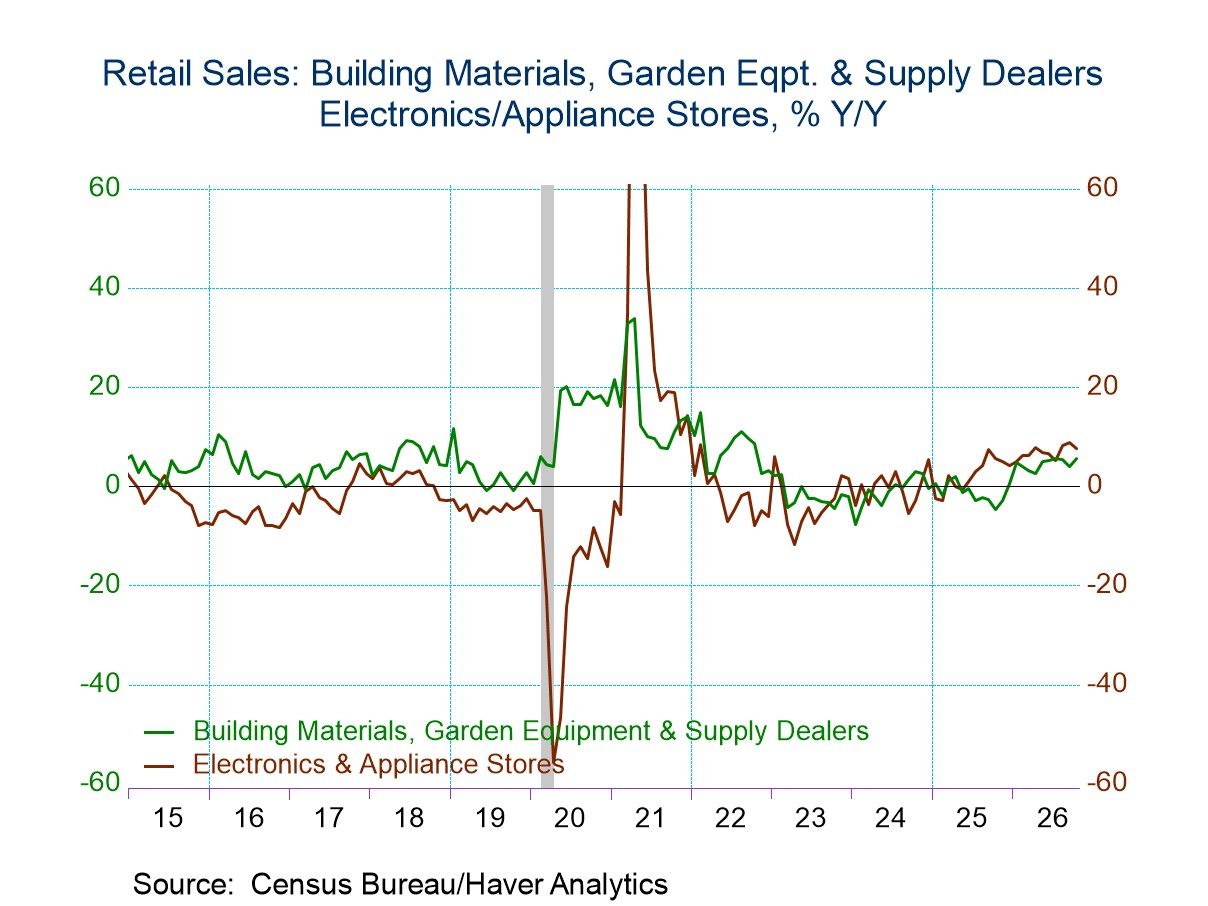
Across major categories, furniture stores (-2.3% m/m), grocery stores (-0.2% m/m), and apparel retailers (-0.7% m/m) all registered monthly declines in October after healthy gains in September. By contrast, building materials/lawn and garden stores (+0.5% m/m) and the “miscellaneous” category (+4.7% m/m) rebounded in October after September falls. Department store sales slipped 0.1% m/m in October following an outsized 1.1% monthly jump in September. The largest contributor to overall sales in October was the nonstore retailer category (mainly internet-only sites), which grew by 1.2%, a third straight month of gains larger than 1%. On a slightly less optimistic note, eating out, a key indicator of discretionary spending, slowed in October, rising only 0.2% m/m following a string of robust monthly increases.
Retail sales data can be found in Haver’s USECON database. The expectations figures are from the Action Economics Forecast Survey in AS1REPNA.
Sandy Batten
AuthorMore in Author Profile »Sandy Batten has more than 30 years of experience analyzing industrial economies and financial markets and a wide range of experience across the financial services sector, government, and academia. Before joining Haver Analytics, Sandy was a Vice President and Senior Economist at Citibank; Senior Credit Market Analyst at CDC Investment Management, Managing Director at Bear Stearns, and Executive Director at JPMorgan. In 2008, Sandy was named the most accurate US forecaster by the National Association for Business Economics. He is a member of the New York Forecasters Club, NABE, and the American Economic Association. Prior to his time in the financial services sector, Sandy was a Research Officer at the Federal Reserve Bank of St. Louis, Senior Staff Economist on the President’s Council of Economic Advisors, Deputy Assistant Secretary for Economic Policy at the US Treasury, and Economist at the International Monetary Fund. Sandy has taught economics at St. Louis University, Denison University, and Muskingun College. He has published numerous peer-reviewed articles in a wide range of academic publications. He has a B.A. in economics from the University of Richmond and a M.A. and Ph.D. in economics from The Ohio State University.
More Economy in Brief
 Asia