U.S. New Home Sales Rebound to an Eight-Month High in August
Summary
- Sales +6.4% m/m (-2.0% y/y) to 684,000 in Aug.; up 27.9% from a July ’22 low.
- Sales m/m up in the Midwest (+84.9%) and South (+6.9%); down in the Northeast (-36.1%) and West (-15.2%).
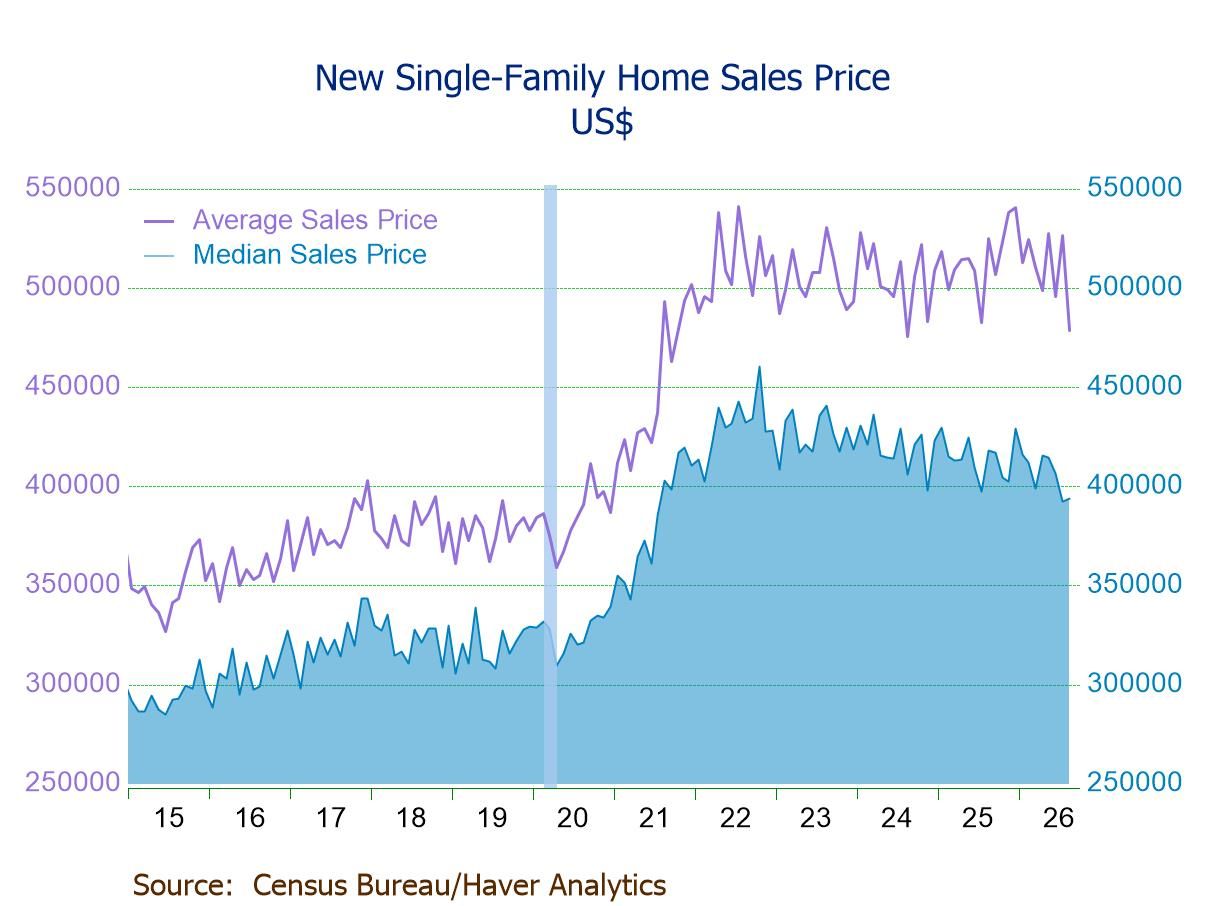
- Median sales price +0.4% m/m to $393,700, first rise since Apr.; avg. price -9.1% m/m to $478,700, a two-year low.
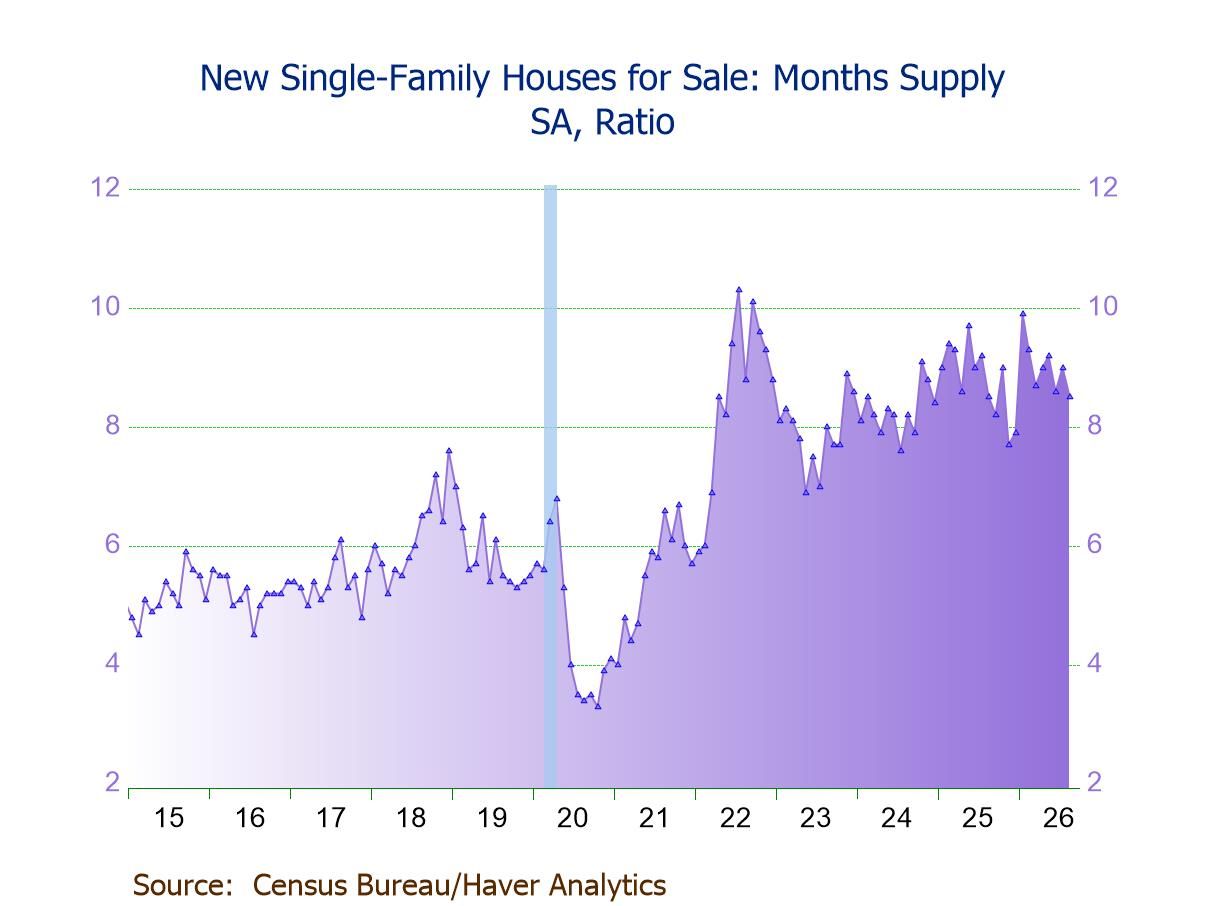
- Unsold inventory unchanged (-2.0% y/y) at 483,000; months' supply down to 8.5 mths., lowest since Dec. ’25.
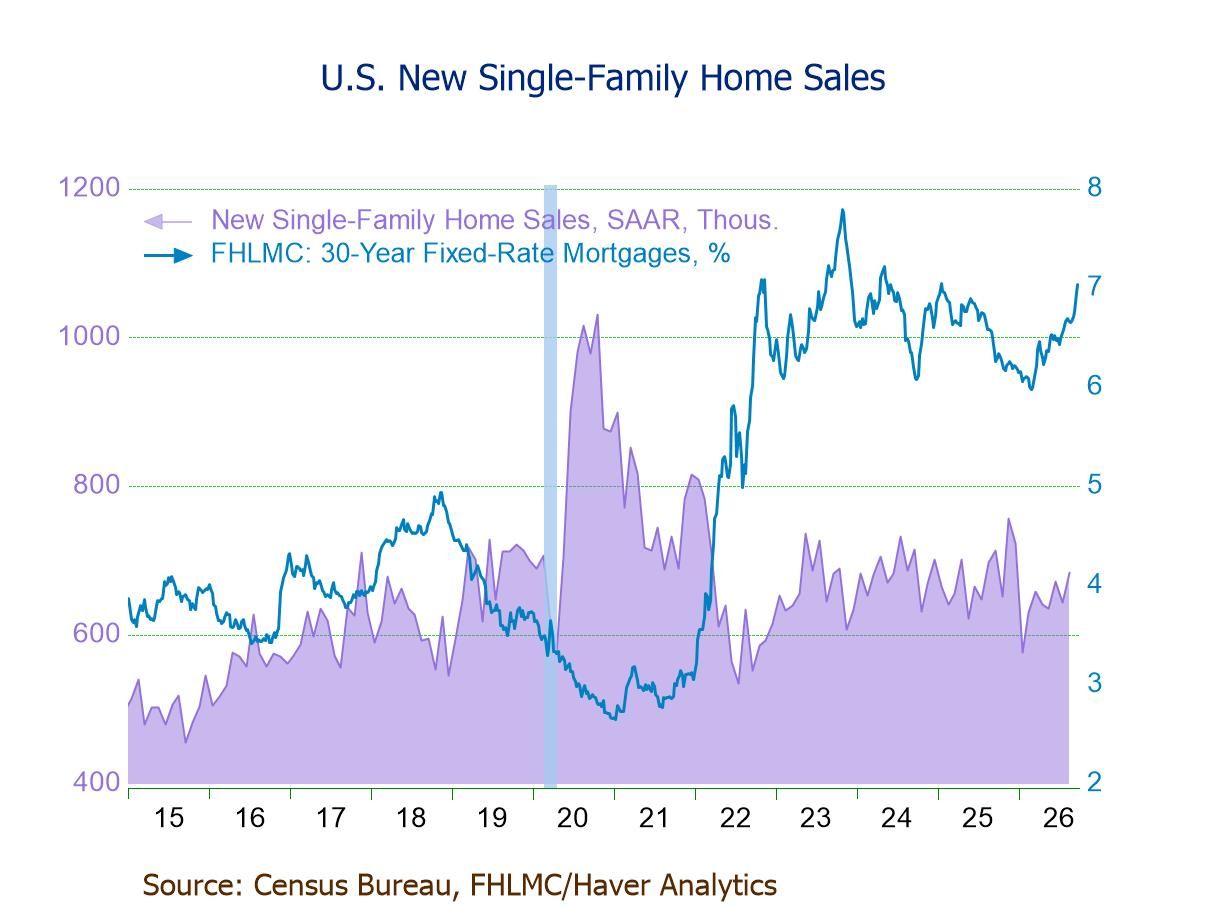
New single-family home sales rose 6.4% m/m (-2.0% y/y) to a seasonally adjusted annual rate of 684,000 units in August, exceeding expectations, following an upwardly revised 4.3% decline to 643,000 in July (initially -10.5%, 607,000) and a downwardly revised 5.7% increase to 672,000 in June (previously +7.6%, 678,000), according to data from the U.S. Census Bureau. The Action Economics Forecast Survey had expected August sales of 615,000. August marked the highest level since December 2025, down 9.6% from a high of 757,000 in November 2025 but up 27.9% from a low of 535,000 in July 2022. The August rise occurred alongside an increase in the average 30-year fixed mortgage rate to 6.67%, the highest since July 2025, from 6.54% in July, according to Freddie Mac.
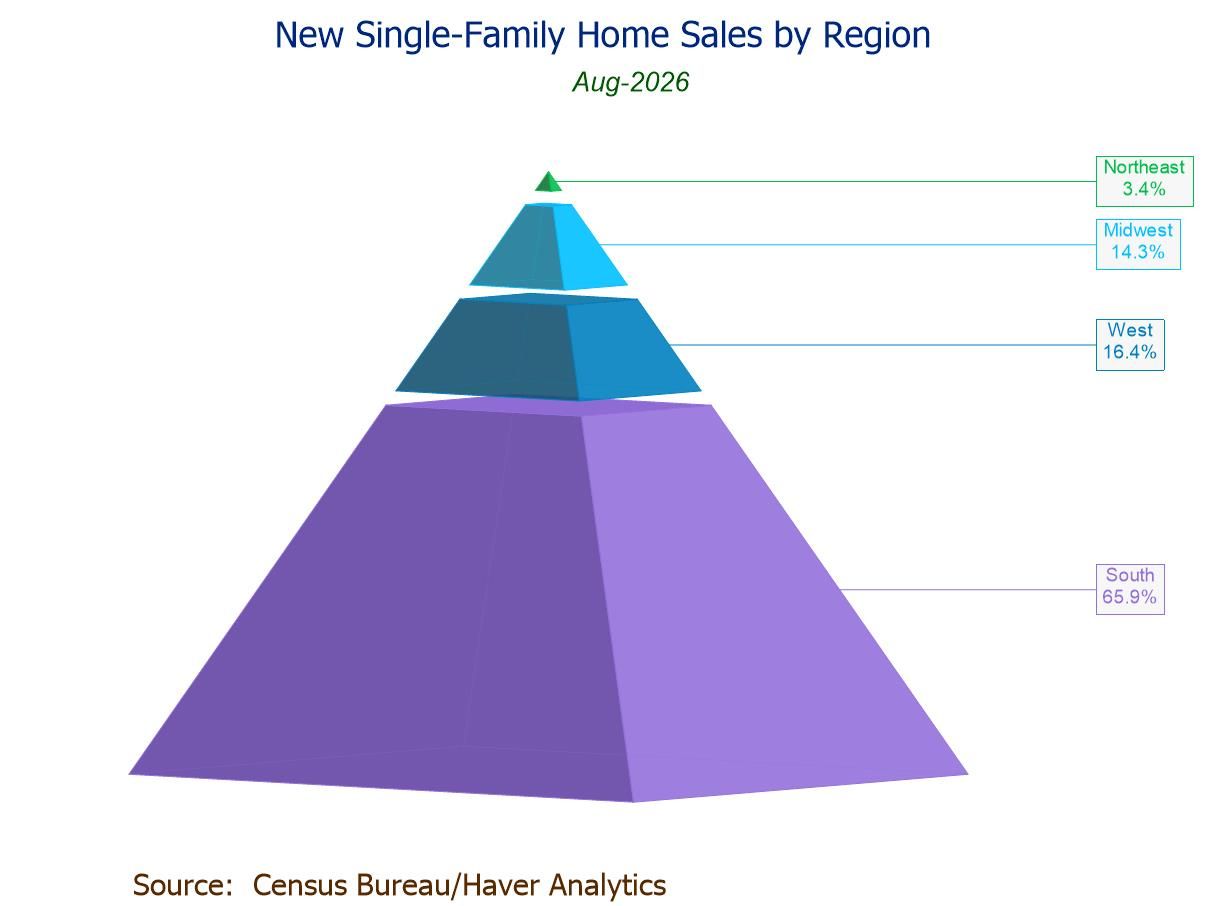
Regionally, August new home sales showed a mixed performance. Sales in the Midwest surged 84.9% (22.5% y/y) to 98,000 in August, the first m/m rise in three months and the highest reading since December 2025, following a 32.1% plunge to 53,000 in July. Sales in the South climbed 6.9% (3.4% y/y) to 451,000, the third m/m gain in four months and the strongest level since November 2025, after a 3.7% July decline to 422,000. In contrast, sales in the Northeast plummeted 36.1% (-20.7% y/y) to 23,000, the first m/m decrease and the lowest level since February, after a 16.1% July advance to 36,000. Sales in the West dropped 15.2% (-26.8% y/y) to 112,000, matching the lowest level since October 2025, following a 5.6% July rebound to 132,000. Notably, the South remained the dominant region, accounting for 65.9% of total U.S. new home sales.
The median sales price of a new home rose 0.4% (-5.8% y/y) to $393,700 in August, the first m/m rise since April, after a 3.5% decline to $392,200 in July. The median sales price was 14.5% below its record high of $460,300 in October 2022 but 9.0% above a low of $361,100 in June 2021. The average sales price fell 9.1% (-8.8% y/y) to $478,700, the lowest since August 2024, following a 6.2% July gain to $526,400. The average price was 0.7% above a low of $475,600 in August 2024 but 11.5% below a peak of $541,200 in July 2022. These sales price data are not seasonally adjusted.
The number of unsold new homes on the market was unchanged (-2.0% y/y) at 483,000 in August and July following a 1.4% decrease to 480,000 in June. The latest figure was 13.9% above a low of 424,000 in May 2023. The seasonally adjusted months' supply of new homes for sale fell to 8.5 months in August, the lowest since December 2025, from 9.0 months in July, still above a low of 6.9 months in May 2023 but below a high of 10.3 months in July 2022.
The median number of months a new home stayed on the market held steady at 3.2 months in August and July after registering at 3.4 months in June, remaining the lowest since January. The latest reading was above its record low of 1.5 months in September and October 2022 but well below a peak of 5.1 months in March 2021. These figures date back to January 1975.
New home sales are recorded when the sales contract is signed. New home sales activity and prices are available in Haver's USECON database. The consensus expectation figure from Action Economics is available in the AS1REPNA database.

Winnie Tapasanun
AuthorMore in Author Profile »Winnie Tapasanun has been working for Haver Analytics since 2013. She has 20+ years of working in the financial services industry. As Vice President and Economic Analyst at Globicus International, Inc., a New York-based company specializing in macroeconomics and financial markets, Winnie oversaw the company’s business operations, managed financial and economic data, and wrote daily reports on macroeconomics and financial markets. Prior to working at Globicus, she was Investment Promotion Officer at the New York Office of the Thailand Board of Investment (BOI) where she wrote monthly reports on the U.S. economic outlook, wrote reports on the outlook of key U.S. industries, and assisted investors on doing business and investment in Thailand. Prior to joining the BOI, she was Adjunct Professor teaching International Political Economy/International Relations at the City College of New York. Prior to her teaching experience at the CCNY, Winnie successfully completed internships at the United Nations. Winnie holds an MA Degree from Long Island University, New York. She also did graduate studies at Columbia University in the City of New York and doctoral requirements at the Graduate Center of the City University of New York. Her areas of specialization are international political economy, macroeconomics, financial markets, political economy, international relations, and business development/business strategy. Her regional specialization includes, but not limited to, Southeast Asia and East Asia. Winnie is bilingual in English and Thai with competency in French. She loves to travel (~30 countries) to better understand each country’s unique economy, fascinating culture and people as well as the global economy as a whole.
 Global