U.S. New Home Sales Ease in September Following August Rebound
Summary
- Sales -0.6% m/m (-5.3% y/y) to 676,000 in Sept.; still 26.4% above a July ’22 low.
- Sales m/m down in the Midwest (-7.3%) and South (-6.6%); up in the Northeast (+28.0%) and West (+21.4%).
- Sales y/y down in all regions except the Northeast (+10.3%).
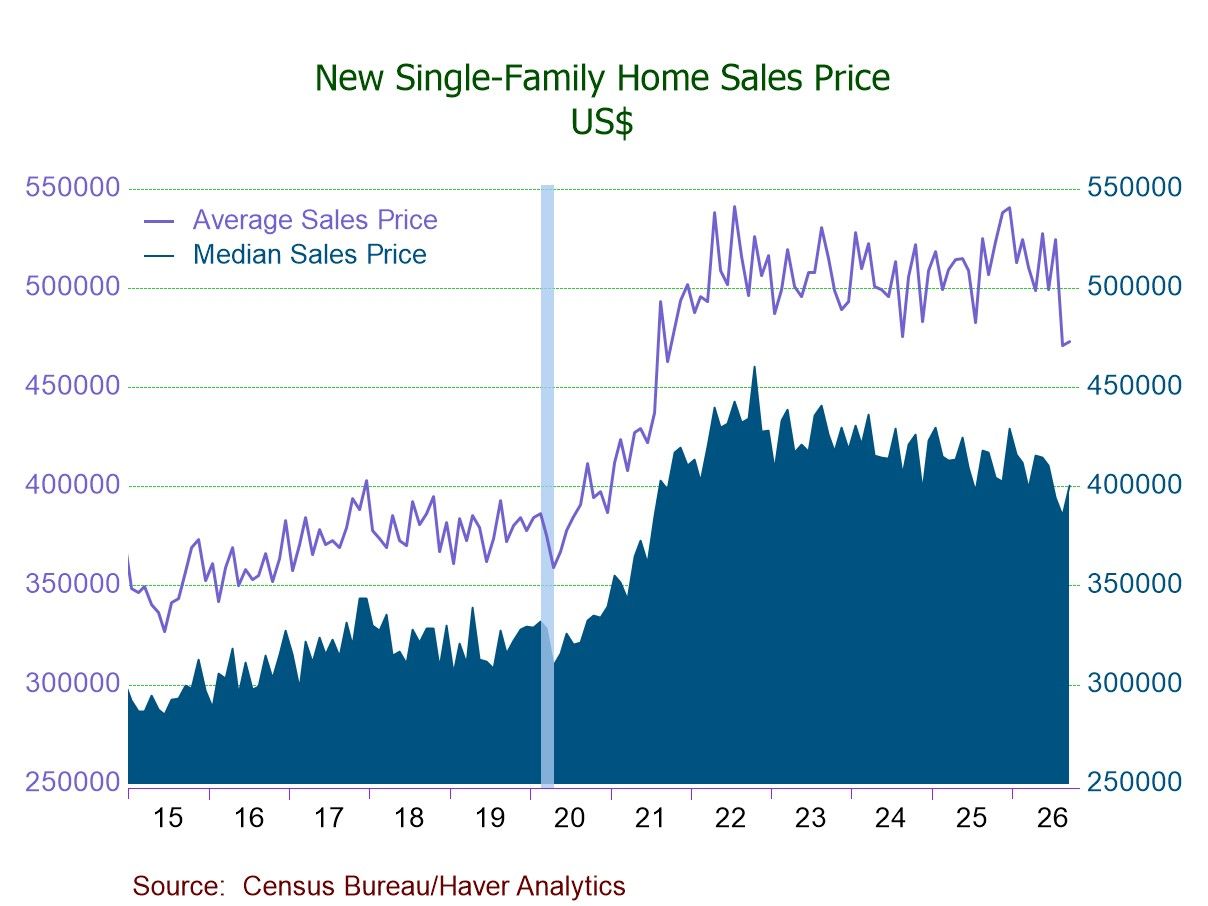
- Median sales price +3.9% m/m to $400,400, first rise in five mths.; avg. price +0.4% m/m to $472,800.
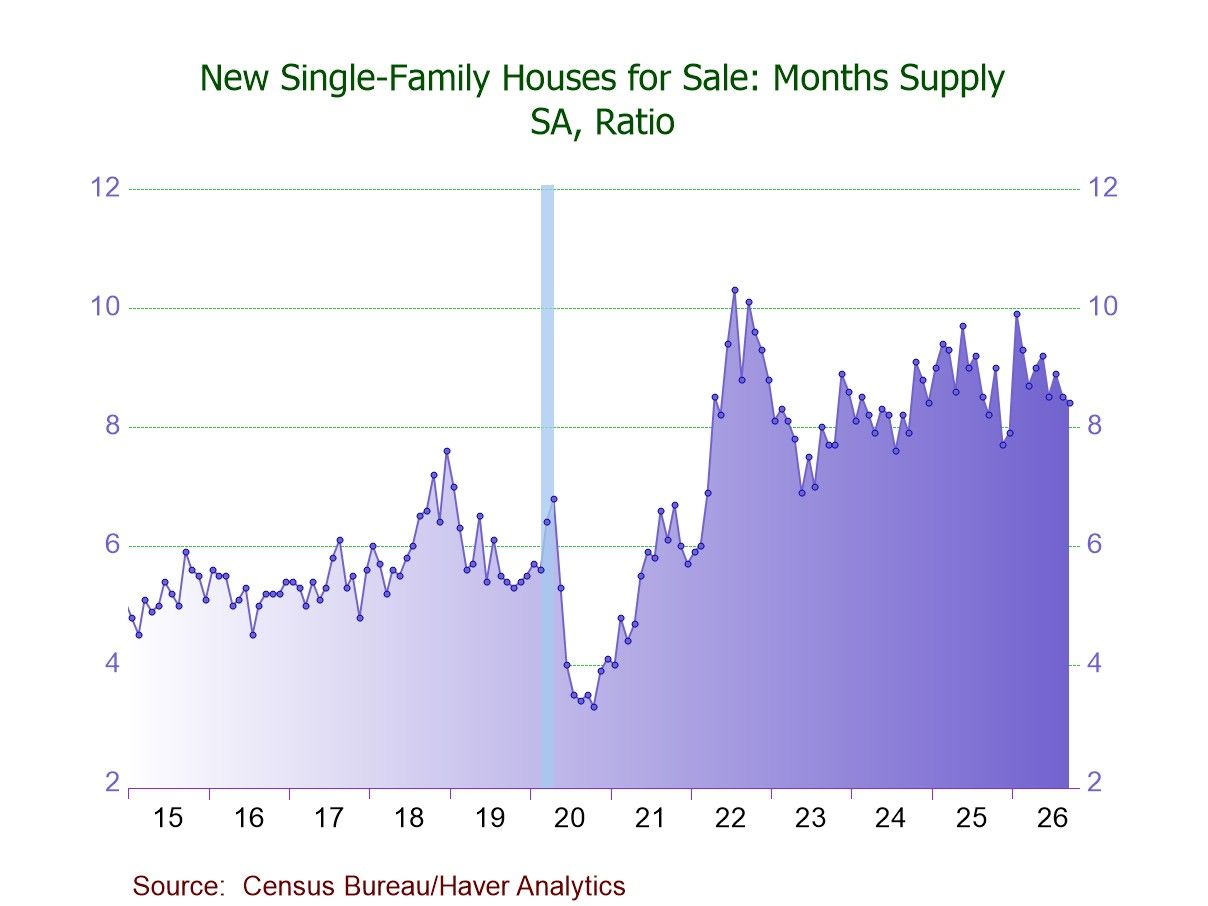
- Unsold inventory -1.0% m/m (-2.3% y/y) to 476,000, lowest since Sept. ’24; months' supply down to 8.4 mths., a Dec. ’25 low.
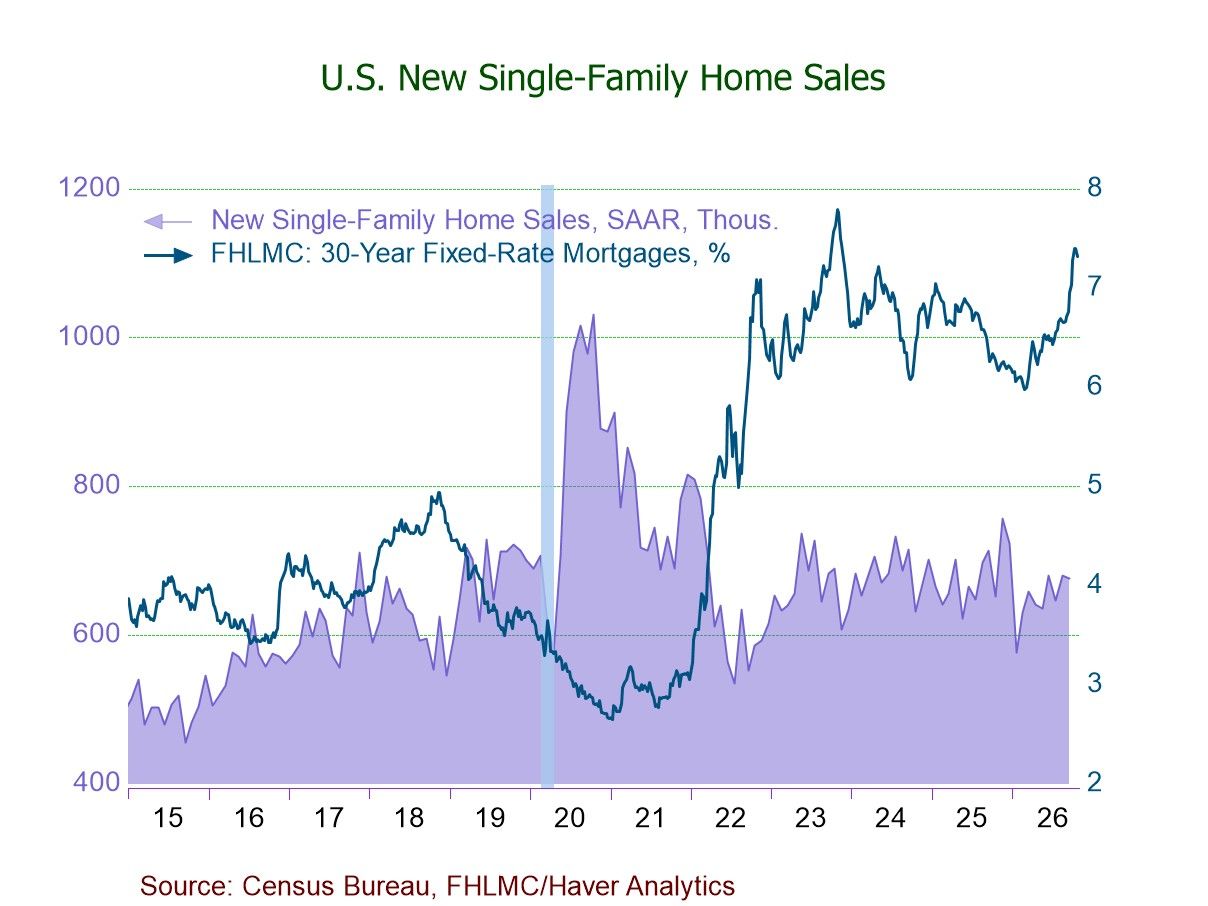
New single-family home sales slipped 0.6% m/m (-5.3% y/y) to a seasonally adjusted annual rate of 676,000 units in September, above expectations, following a downwardly revised 5.1% gain to 680,000 in August (initially +6.4%, 684,000) and a revised 4.9% drop to 647,000 in July (previously -4.3%, 643,000), data from the U.S. Census Bureau showed, indicating that demand for new homes remained relatively resilient amid high mortgage rates, with sales outperforming market forecasts despite remaining below year-earlier levels. The Action Economics Forecast Survey had expected September sales of 652,000. September marked the second m/m decrease in three months, leaving sales 10.7% below a high of 757,000 in November 2025 but 26.4% above a low of 535,000 in July 2022. The September decline coincided with a rise in the average 30-year fixed mortgage rate to 6.86%, the highest since January 2025, from 6.67% in August, according to Freddie Mac.
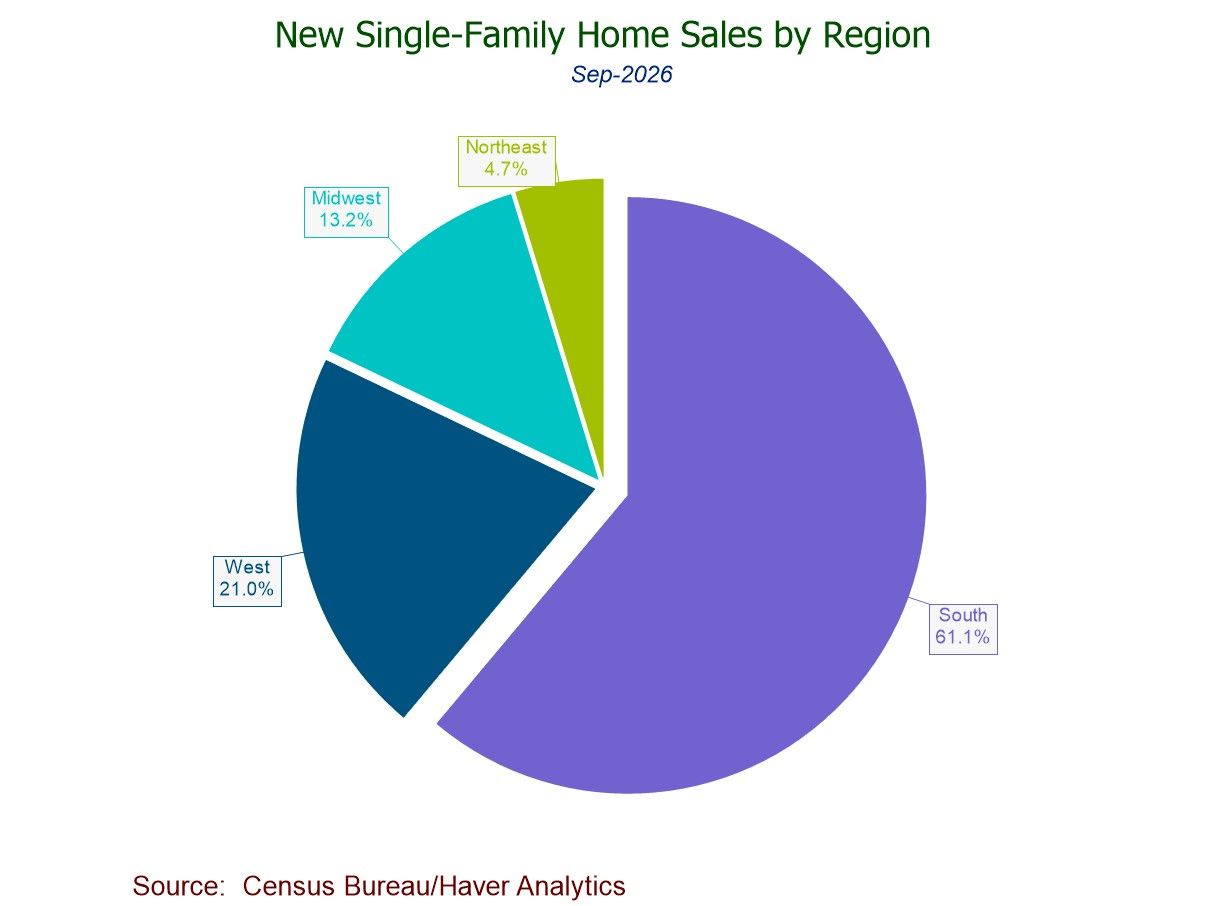
Regionally, September new home sales were mixed. Sales in the Midwest fell 7.3% (-8.2% y/y) to 89,000 in September, the third m/m fall in four months, after an 81.1% surge to 96,000 in August. Sales in the South slid 6.6% (-0.7% y/y) to 413,000, the lowest level since May, following a 5.5% August rebound to 442,000. In contrast, sales in the Northeast soared 28.0% (10.3% y/y) to 32,000, the third m/m gain in four months, after a 30.6% August plunge to 25,000. Sales in the West jumped 21.4% (-17.4% y/y) to 142,000, the strongest level since April, reversing a 15.8% August drop to 117,000. Notably, the South remained the dominant region, accounting for 61.1% of total U.S. new home sales.
The median sales price of a new home climbed 3.9% (-3.9% y/y) to $400,400 in September, the first m/m increase since April, after a 2.2% slide to $385,400 in August. The median sales price was 13.0% below its record high of $460,300 in October 2022 but 10.9% above a low of $361,100 in June 2021. The average sales price edged up 0.4% (-6.7% y/y) to $472,800 following a 10.2% August decrease to $470,800. The average price was 12.6% below a high of $541,200 in July 2022 but 2.1% above a low of $462,900 in September 2021. These sales price data are not seasonally adjusted.
The number of unsold new homes on the market fell 1.0% (-2.3% y/y) to 476,000 in September, the third m/m slide in four months and the lowest level since September 2024, after a 0.2% decline to 481,000 in August. The latest figure was 12.3% above a low of 424,000 in May 2023. The seasonally adjusted months' supply of new homes for sale ticked down to 8.4 months in September, the lowest level since December 2025, from 8.5 months in August and 8.9 months in July, still above a low of 6.9 months in May 2023 but below a high of 10.3 months in July 2022.
The median number of months a new home stayed on the market dipped to 3.0 months in September, matching the lowest level since January, from 3.1 months in August and July. The latest reading was above its record low of 1.5 months in September and October 2022 but well below a peak of 5.1 months in March 2021. These figures date back to January 1975.
New home sales are recorded when the sales contract is signed. New home sales activity and prices are available in Haver's USECON database. The consensus expectation figure from Action Economics is available in the AS1REPNA database.

Winnie Tapasanun
AuthorMore in Author Profile »Winnie Tapasanun has been working for Haver Analytics since 2013. She has 20+ years of working in the financial services industry. As Vice President and Economic Analyst at Globicus International, Inc., a New York-based company specializing in macroeconomics and financial markets, Winnie oversaw the company’s business operations, managed financial and economic data, and wrote daily reports on macroeconomics and financial markets. Prior to working at Globicus, she was Investment Promotion Officer at the New York Office of the Thailand Board of Investment (BOI) where she wrote monthly reports on the U.S. economic outlook, wrote reports on the outlook of key U.S. industries, and assisted investors on doing business and investment in Thailand. Prior to joining the BOI, she was Adjunct Professor teaching International Political Economy/International Relations at the City College of New York. Prior to her teaching experience at the CCNY, Winnie successfully completed internships at the United Nations. Winnie holds an MA Degree from Long Island University, New York. She also did graduate studies at Columbia University in the City of New York and doctoral requirements at the Graduate Center of the City University of New York. Her areas of specialization are international political economy, macroeconomics, financial markets, political economy, international relations, and business development/business strategy. Her regional specialization includes, but not limited to, Southeast Asia and East Asia. Winnie is bilingual in English and Thai with competency in French. She loves to travel (~30 countries) to better understand each country’s unique economy, fascinating culture and people as well as the global economy as a whole.
More Economy in Brief
 Asia