U.S. Durable Goods Orders Jump in September on Surge in Aircraft Orders
by:Sandy Batten
|in:Economy in Brief
Summary
- New orders for durable goods jumped a larger-than-expected 1.8% m/m in September, led by a surge in nondefense aircraft orders.
- Orders excluding aircraft rose a more modest 0.1% m/m.
- Core capital goods shipments rose 3.9% q/q in Q3, pointing to another strong increase in business spending on equipment.
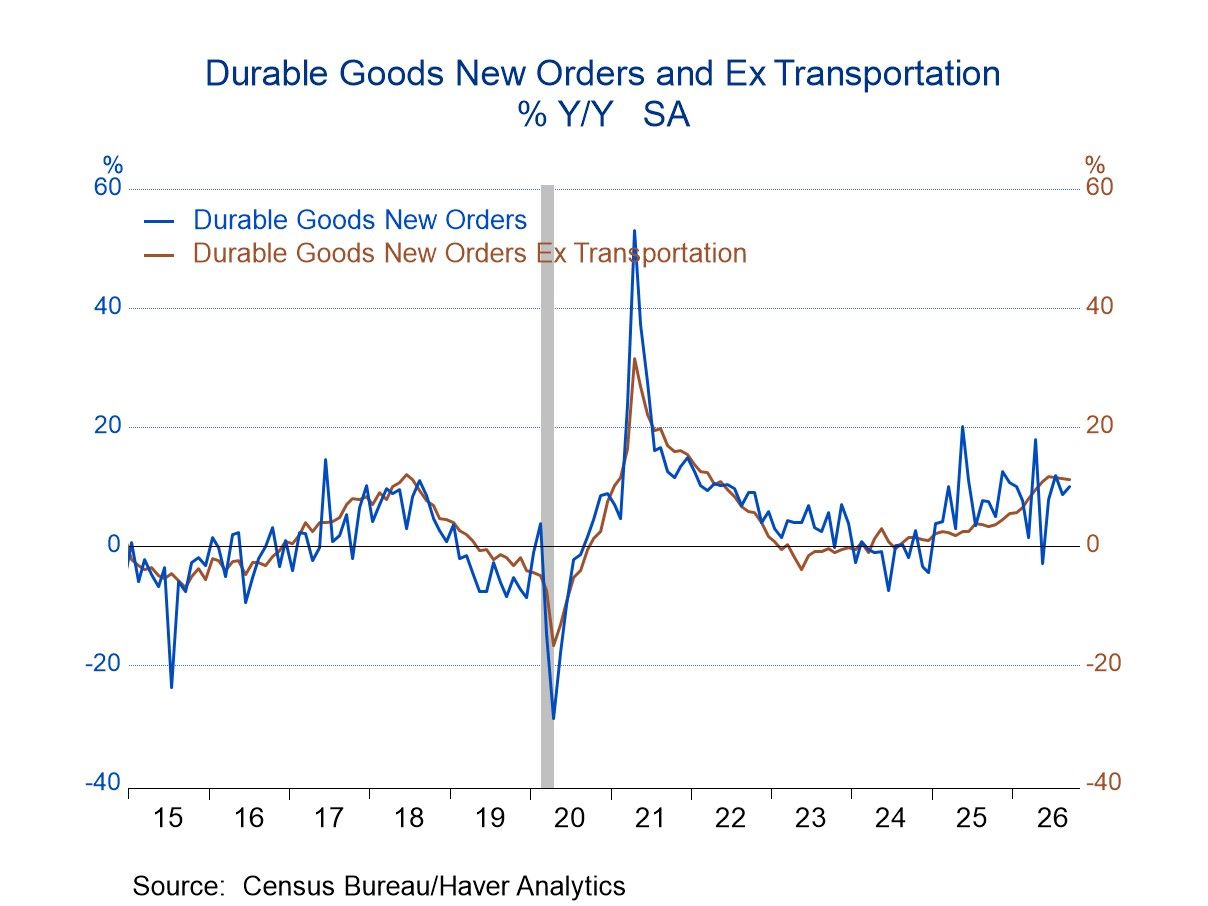
New orders for durable goods rose more than expected in September, helped significantly by a surge in aircraft orders. Total orders increased 1.8% m/m (+9.9% y/y) in September following an upwardly revised 0.1% m/m gain in August (previously -0.1% m/m). The Action Economics Forecast Survey expected a 1.4% monthly increase. Aircraft orders jumped 23.2% m/m, led by a 28.4% m/m rise in nondefense aircraft orders. This accounted for much of the September advance in total orders. Excluding aircraft, other orders increased by a more modest 0.1% m/m in September, the same monthly gain as in August. Overall, transportation orders increased 4.6% m/m (7.9% y/y) in September with orders ex transportation rising 0.5% m/m (11.1% y/y). For all of the third quarter, total orders increased 0.6% q/q while ex transportation orders rose 2.4% q/q.
Across major sectors, orders for computers and related products led the way, rising 3.9% m/m (+26.7% y/y) in September on top of a 2.3% monthly gain in August. Primary metals orders increased 0.5% m/m (+20.4% y/y); orders for fabricated metals rose 0.4% m/m (8.3% y/y); machinery orders were up 1.2% m/m (+16.1% y/y). By contrast, orders for communications equipment fell 1.3% m/m (+26.8% y/y), the second consecutive monthly decline, and orders for electrical equipment and appliances slipped 0.3% m/m (+4.8% y/y), the second monthly decline in the past three months.
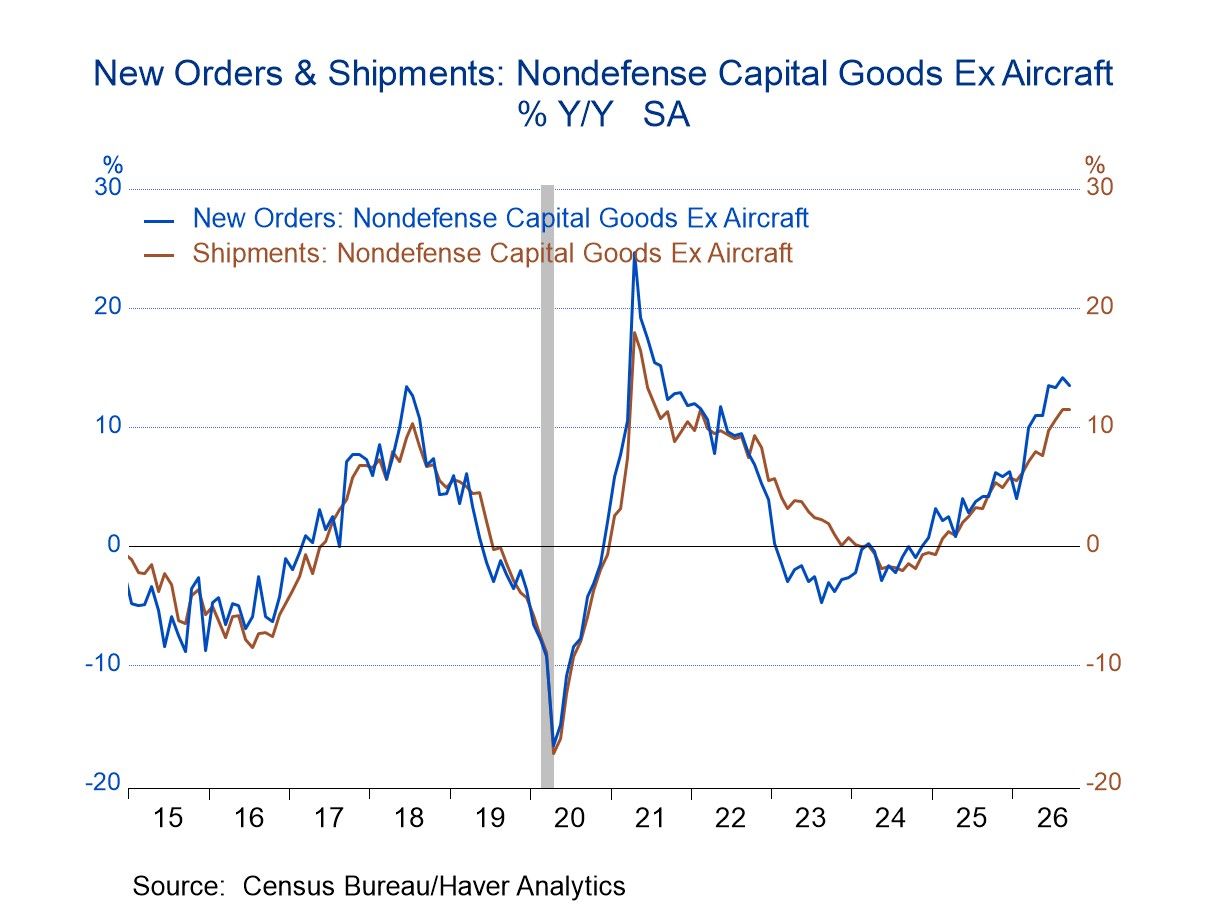
Strong business spending on equipment has been a key factor supporting the economy over the past several quarters. Shipments of core capital goods (nondefense capital goods shipments excluding aircraft) are a reliable coincident indicator of business spending on equipment in the national accounts. They rose 1.2% m/m (+11.5% y/y) in September to post another solid quarter. For all of Q3, core capital goods shipments were up 3.9% q/q after a 2.8% quarterly gain in Q2. Real business spending on equipment jumped 13.4% q/q saar in Q2. The Q3 gain in core capital goods shipments points to another strong quarterly increase in Q3 (scheduled for release with GDP on Thursday, October 29). Core capital goods orders increased 0.5% m/m (+13.5% y/y) in September on top of a 1.6% monthly jump in August. For all of Q3 they were up 3.6% q/q versus 4.3% q/q in Q2.
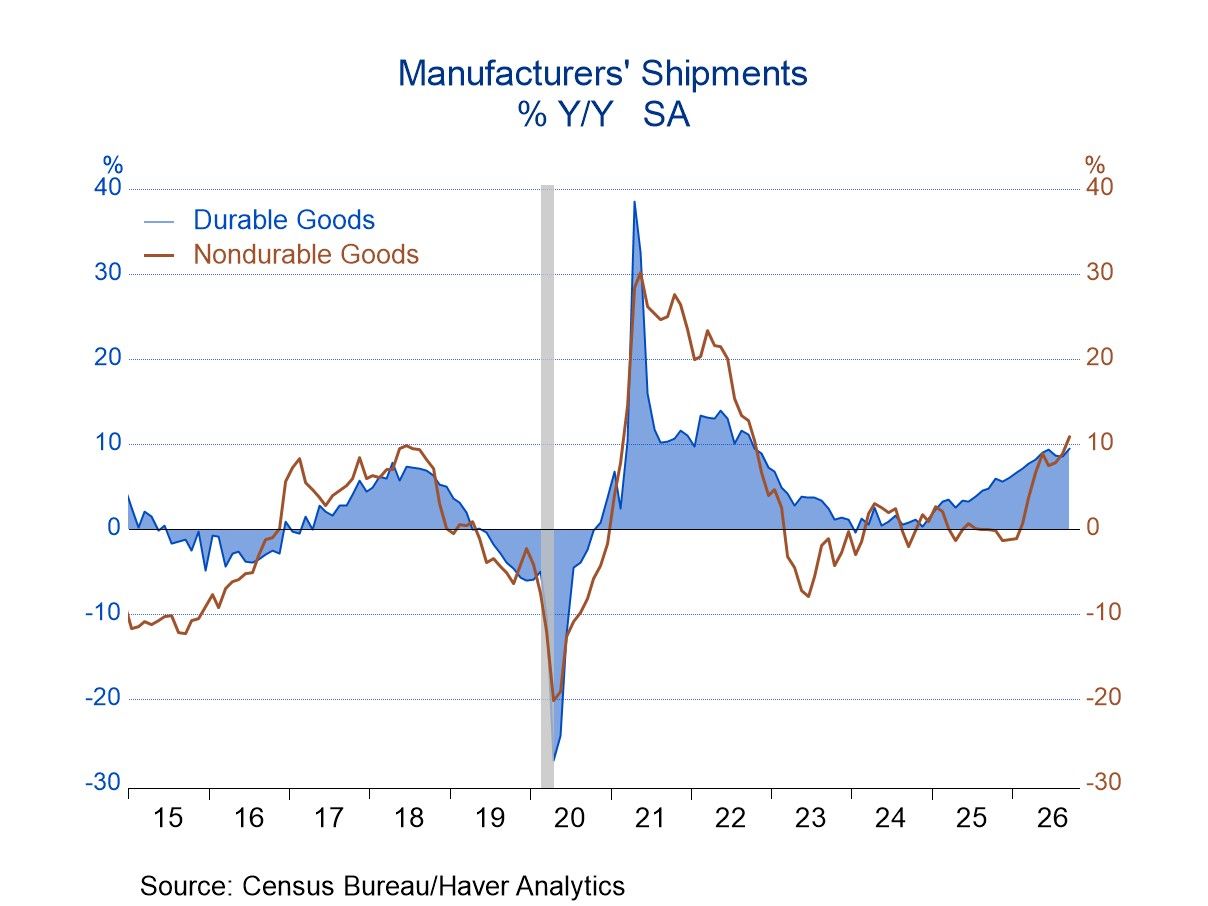
Total manufacturing shipments rose a solid 1.3% m/m (+10.1% y/y) in September following a 0.1% monthly rise in August. For all of Q3, shipments increased 1.9% q/q versus 4.0% q/q in Q2. Shipments of durable goods rose 0.9% m/m (+9.4% y/y) in September while shipments of nondurable goods jumped 1.7% m/m (+10.9% y/y). Durable goods shipments excluding transportation increased 0.7% m/m (+9.3% y/y), led by a 3.4% monthly rise in computer shipments and a 1.7% monthly gain in machinery shipments. By contrast, shipments of communications equipment fell 0.6% m/m in September, the first monthly decline in 11 months.
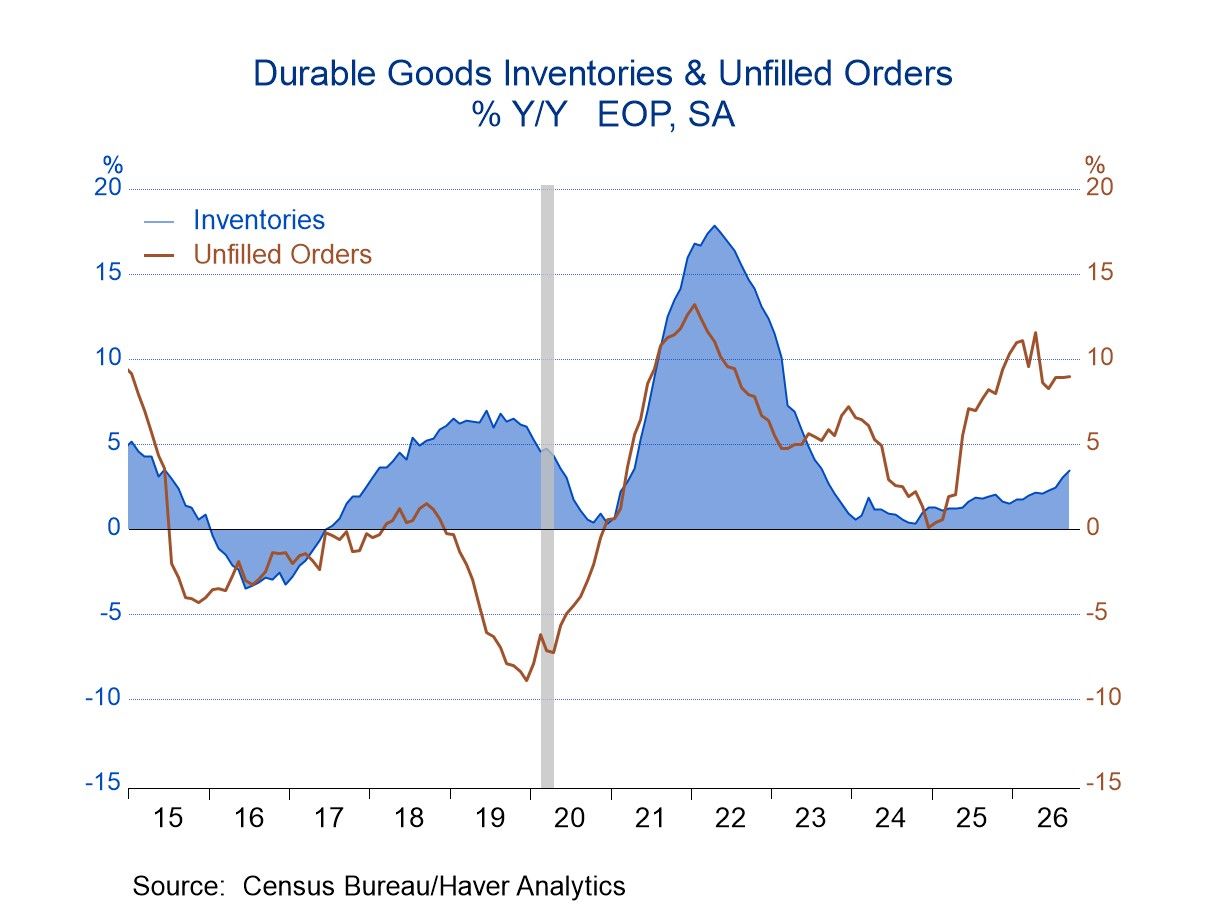
Unfilled durable goods orders rose 0.8% m/m (+9.0% y/y) in September, the largest monthly gain since April. Total factor inventories increased 0.3% m/m (+3.0% y/y) following a 0.5% monthly gain in August. Durable goods inventories rose 0.3% m/m (+3.4% y/y), and nondurable goods inventories increased 0.4% m/m (+2.4% y/y).
Manufacturers’ orders and shipments of durable and nondurable goods, along with unfilled orders and inventories, are compiled by the U.S. Census Bureau. They are available in Haver’s USECON database. The Action Economics forecast data are in the AS1REPNA database.
Sandy Batten
AuthorMore in Author Profile »Sandy Batten has more than 30 years of experience analyzing industrial economies and financial markets and a wide range of experience across the financial services sector, government, and academia. Before joining Haver Analytics, Sandy was a Vice President and Senior Economist at Citibank; Senior Credit Market Analyst at CDC Investment Management, Managing Director at Bear Stearns, and Executive Director at JPMorgan. In 2008, Sandy was named the most accurate US forecaster by the National Association for Business Economics. He is a member of the New York Forecasters Club, NABE, and the American Economic Association. Prior to his time in the financial services sector, Sandy was a Research Officer at the Federal Reserve Bank of St. Louis, Senior Staff Economist on the President’s Council of Economic Advisors, Deputy Assistant Secretary for Economic Policy at the US Treasury, and Economist at the International Monetary Fund. Sandy has taught economics at St. Louis University, Denison University, and Muskingun College. He has published numerous peer-reviewed articles in a wide range of academic publications. He has a B.A. in economics from the University of Richmond and a M.A. and Ph.D. in economics from The Ohio State University.
More Economy in Brief
 Asia