U.S. JOLTS: Labor Demand Improved in September
Summary
- Large industry gains drove September increases in job openings and hires.
- Quits jump ran counter to alternative job leavers.
- Hires-Separations point to mixed nonfarm payroll revisions.
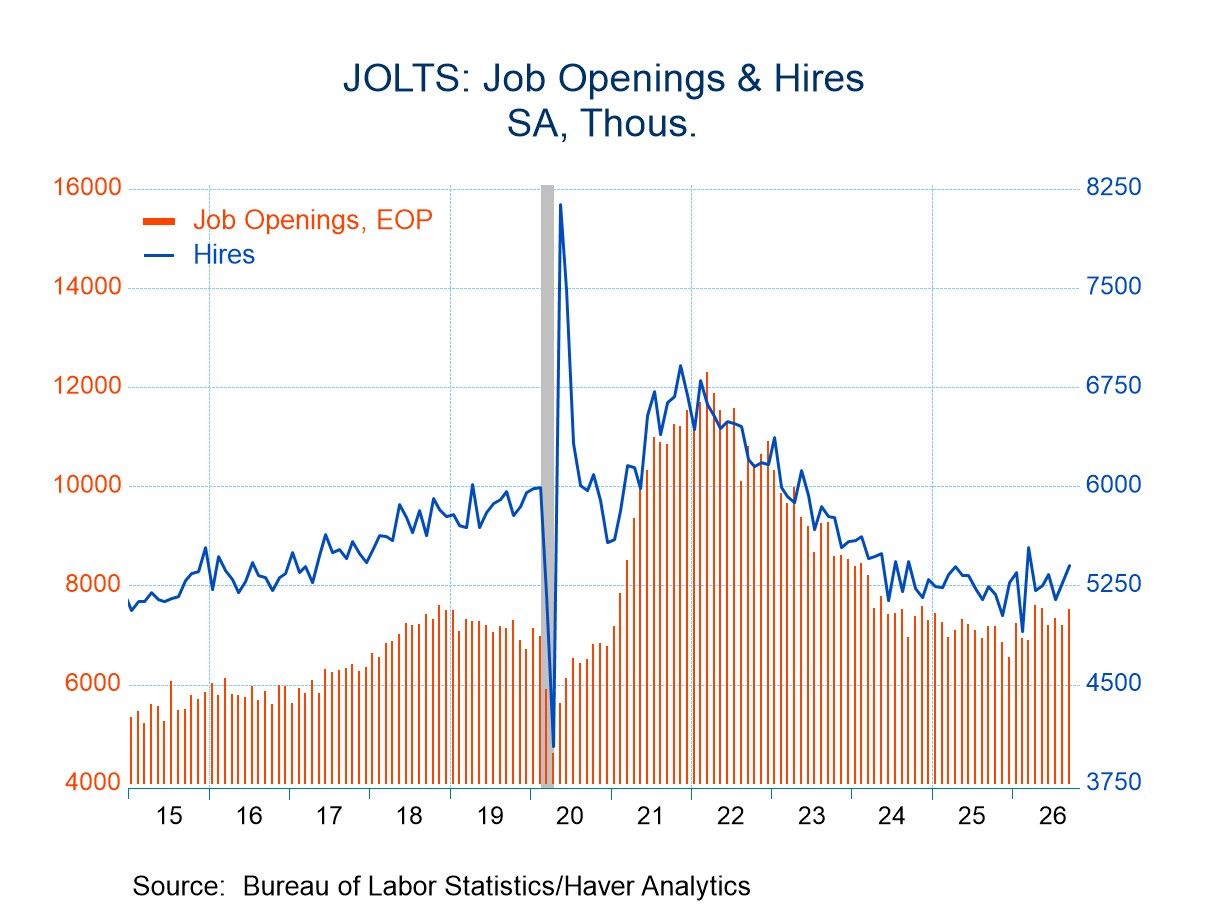
The September Job Openings and Labor Turnover Survey (JOLTS) portrayed optimism for the U.S. labor demand picture as the third quarter came to an end. On the surface, total nonfarm job openings rose 333,000 in September, following August’s 145,000 decline. This left the current level of 7.523 million up 4.9% compared to a year ago. Looking closer in, however, job openings have yet to reattain the April 2026 high (7.585 million), running 2.0% annualized below this point. Large one-month industry gains were notable in Professional & Business Services (106,000) and State and Local Excluding Education (104,000).
Total nonfarm hires did not have the same feel as job openings. Despite rising back-to-back in August (125,000) and September (131,000), the current 5.402 million rate stood 4.7% annualized below the March 2026 high (5.535 million). Granted, the year-over-year trend was up 3.0%, but this didn’t shake hires out of the 4.9-5.6 million range that has been in place since mid-2024. Moreover, one industry – accommodation & food services (up 158,000) – was responsible for more than the entire gain in September nonfarm hires. This questions the sustainability of the rise.
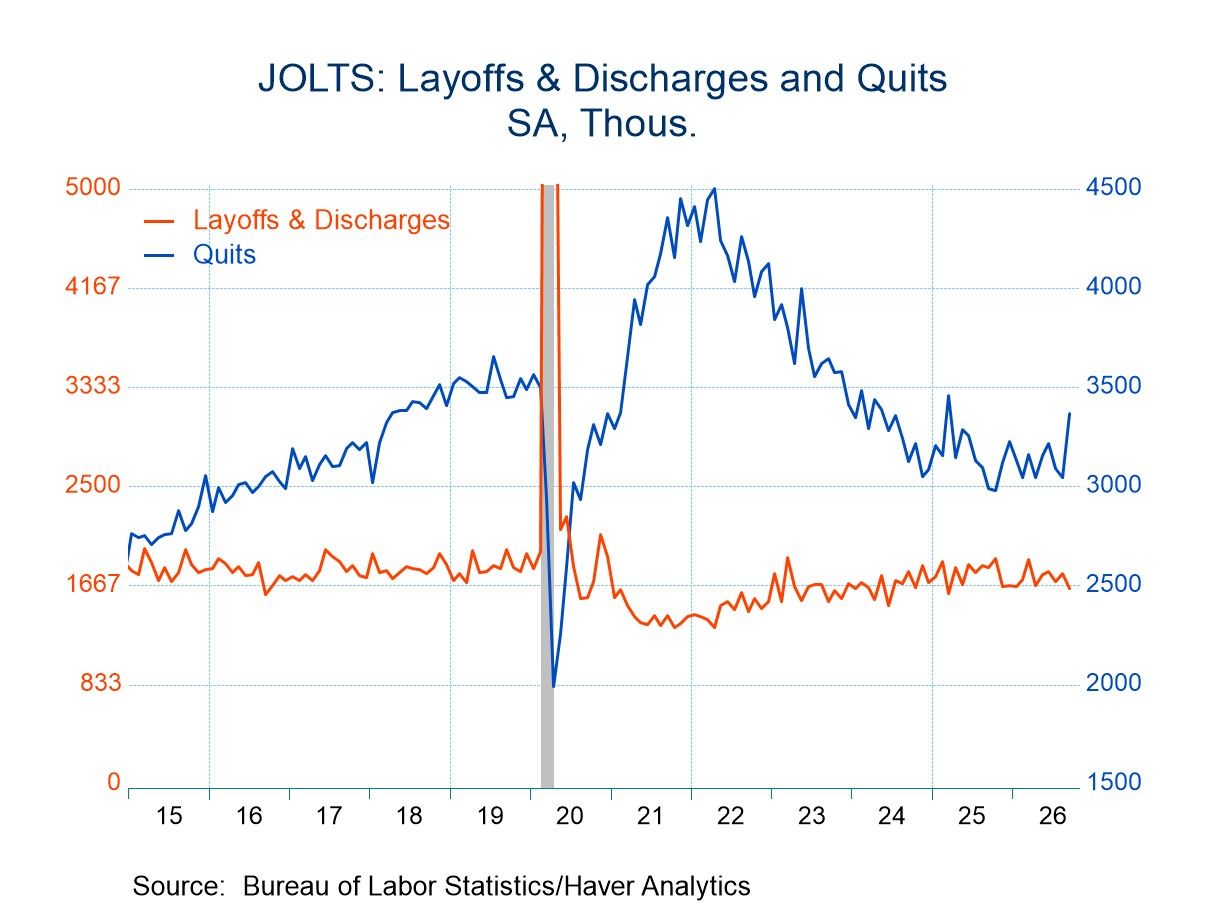
Total nonfarm quits advanced 321,000 to 3.365 million in September, reaching the highest level since March 2025’s 3.456 million. The 12.5% year-over-year rise bucked the prior trend that had seen just three trailing 12-month increases in the previous 48 months. From a technical standpoint, September’s gain was the fifth largest on record, suggesting a high hurdle to improve from the end of the third quarter. Like with hires, accommodation & food services (up 197,000) had a sizable influence, questioning the strength of the aggregate signal. To be sure, September’s quits ran counter to the 173,000-drop in job leavers, the Bureau of Labor Statistics’ Household Survey’s sister quits gauge, that fell to a 16-month low of 10.5% of the total unemployed in September.
Nonfarm layoffs fell in September by 127,000 to 1.641 million. This left the YoY comparison at -9.6% for September. While this reinforced the wider “low fire” narrative, the current level of layoffs remained in the wider 1.6-1.9 million range that has been in place since July 2024. Since bottoming in 2022, nonfarm layoffs have moved in a similar manner to the higher frequency series, weekly continuing claims. JOLTS layoffs are reported with a lag relative to continuing claims. The latter’s sideways movement in September (1.709 million) and October (1.709 million month-to-date average) suggests no further improvement in the near-term pink slip picture.
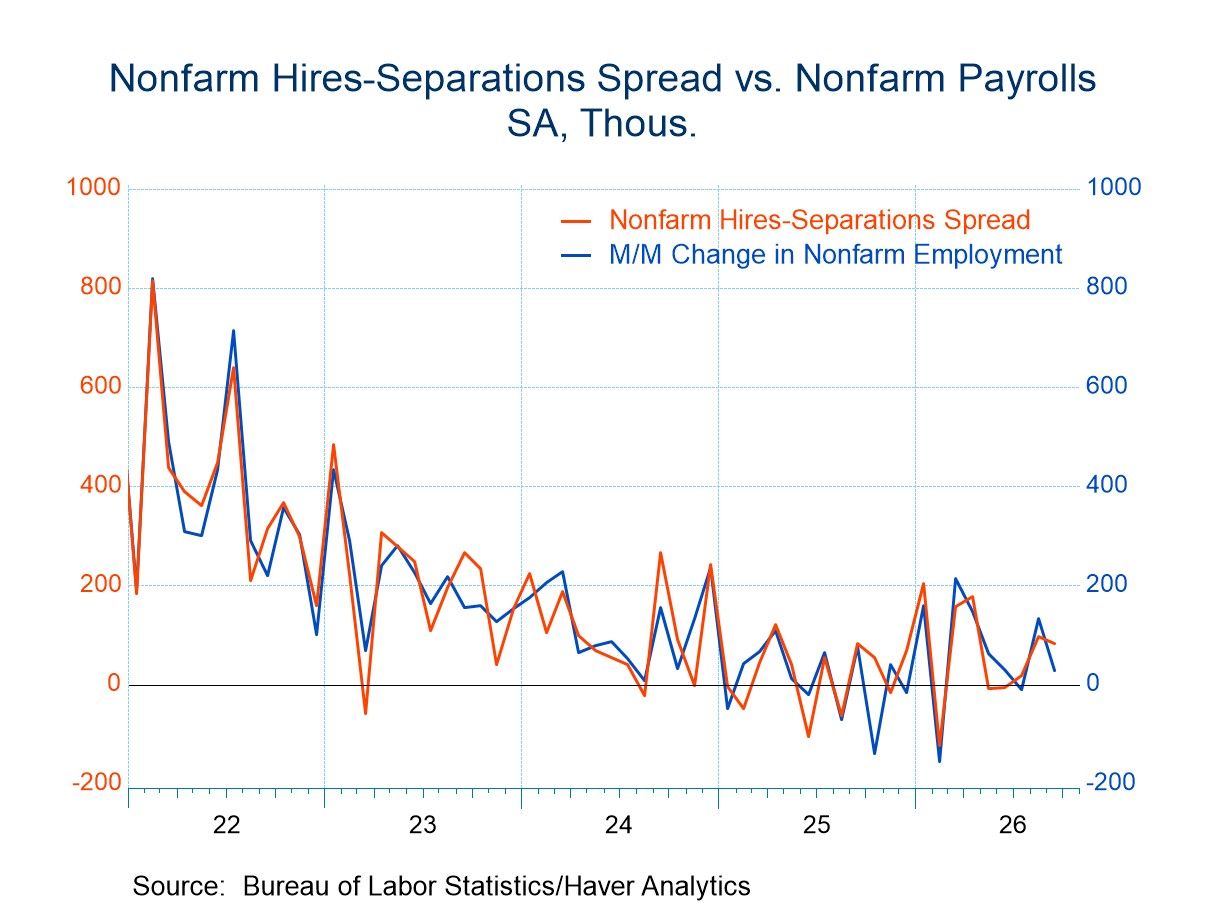
The nonfarm hires-separations spread acts as a channel check for the monthly change in nonfarm payroll employment (NFP). The JOLTS report points to mixed results for NFP revisions in this Friday’s U.S. Employment report. The hires-separations spread in August was revised down to 96,000 from the previous 122,000; the -26,000 difference translates to the direction of the NFP revision. For September, the hires-separations spread came in at 83,000 versus the 29,000 initial NFP gain for that month, implying a +54,000 adjustment. Taken together, the net two-month revision would be +28,000.
The Job Openings and Labor Turnover Survey (JOLTS) data are available in Haver’s USECON database.
Jonathan Basile
AuthorMore in Author Profile »Jonathan Basile is Street veteran of more than three decades with extensive experience analyzing the global macro environment from the perspectives of sell-side economist, sovereign analyst, and buy-side strategist. He joined Danielle DiMartino Booth at Quill Intelligence in June 2025 as Director of Research where he regularly taps his assets for the firm’s key products, Weekly Quill, Saturday Intelligence Briefing, and Daily Feather.
The prior 11 years were spent at AIG’s and Corebridge Financial’s Investment arms as Head of Global Macro Strategy where his macro and market knowledge were utilized by key stakeholders, like the CIO teams, portfolio managers and third-party clients. Before the Corebridge spin-off from AIG, he built the Global Macro desk from scratch to become an integral part of the active investment process. He streamlined investment practices by steering a centralized monthly global macro discussion allowing subsequent asset-class meetings to be focused on strategy. Jonathan’s tactical rate views were frequently employed by public credit portfolio managers and traders. His storytelling prowess was displayed in a colorful weekly rant whose internal distribution grew steadily and organically.
Jonathan’s past experience with the likes of Dr. Lacy Hunt, Christopher Low, Ian Shepherdson, Elliott Platt, Dr. Neal Soss, and Kathleen Stephansen (twice) prepared him for almost anything thrown his way from the economy and the markets. His years at HSBC, DLJ and Credit Suisse combined saw him cover the economies of the US, Canada, Japan and the UK. He has been recognized as a four-time winning team member of the Marketwatch US Forecaster of the Month and was ranked by Bloomberg as a top forecaster of the Canadian economy.
Jonathan is married with three children – one of which is a Red Sox fan in a Yankees household. You can find Jonathan running or biking on weekends or catching for his men’s baseball team during the spring and summer. He holds a BA in Economics from Princeton University.
More Economy in Brief
 Global