U.S. Existing Home Sales Drop in October to Lowest Level Since August 2010
Summary
- October sales -5.5% m/m to 3.75 mil., fourth m/m decline in five mths.; -8.8% y/y, third straight y/y drop.
- Sales m/m down in the West (-9.7%), South (-6.5%), and Midwest (-3.2%); flat in the Northeast.
- Sales y/y down in all four regions, w/ the steepest decline in the West (-14.5%).
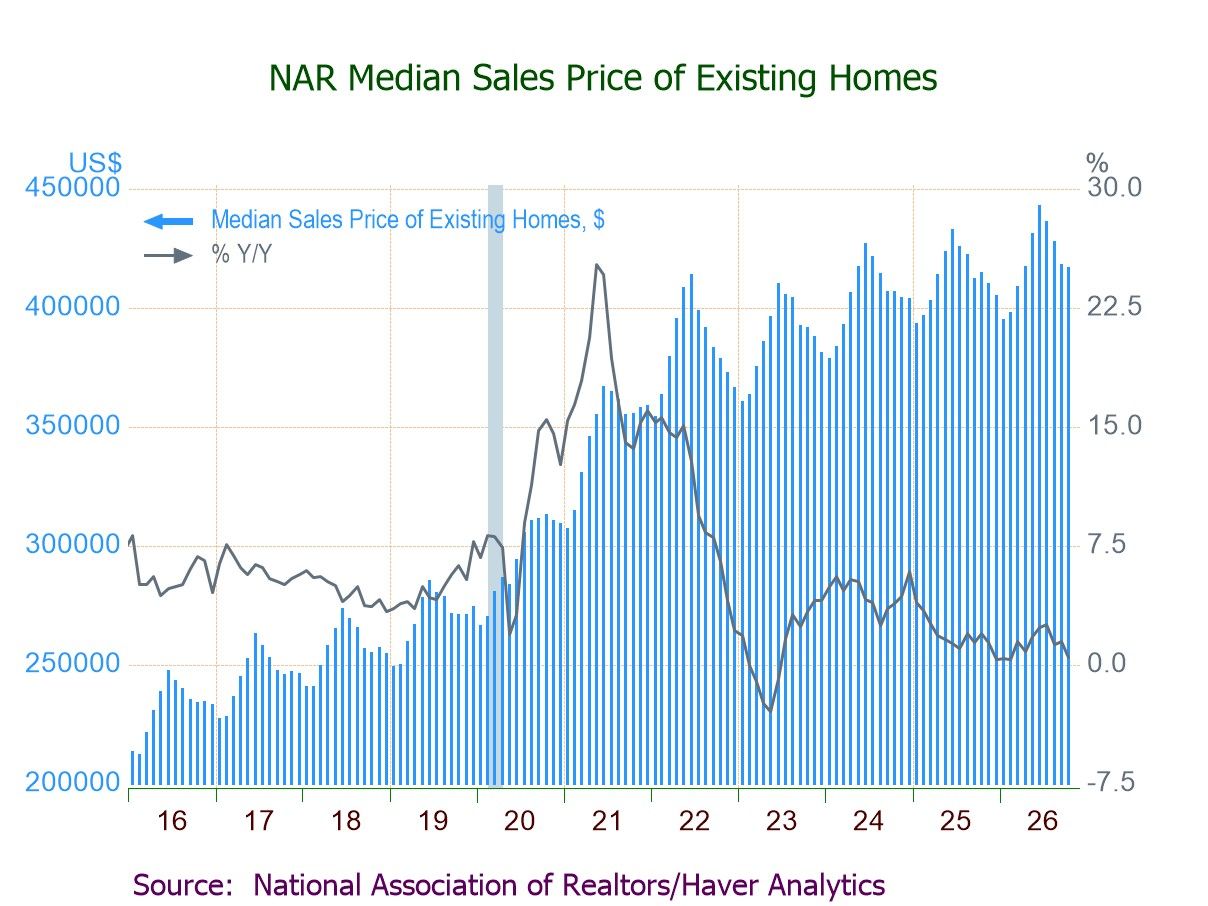
- Median sales price -0.4% (+0.4% y/y) to $416,700, lowest since March.
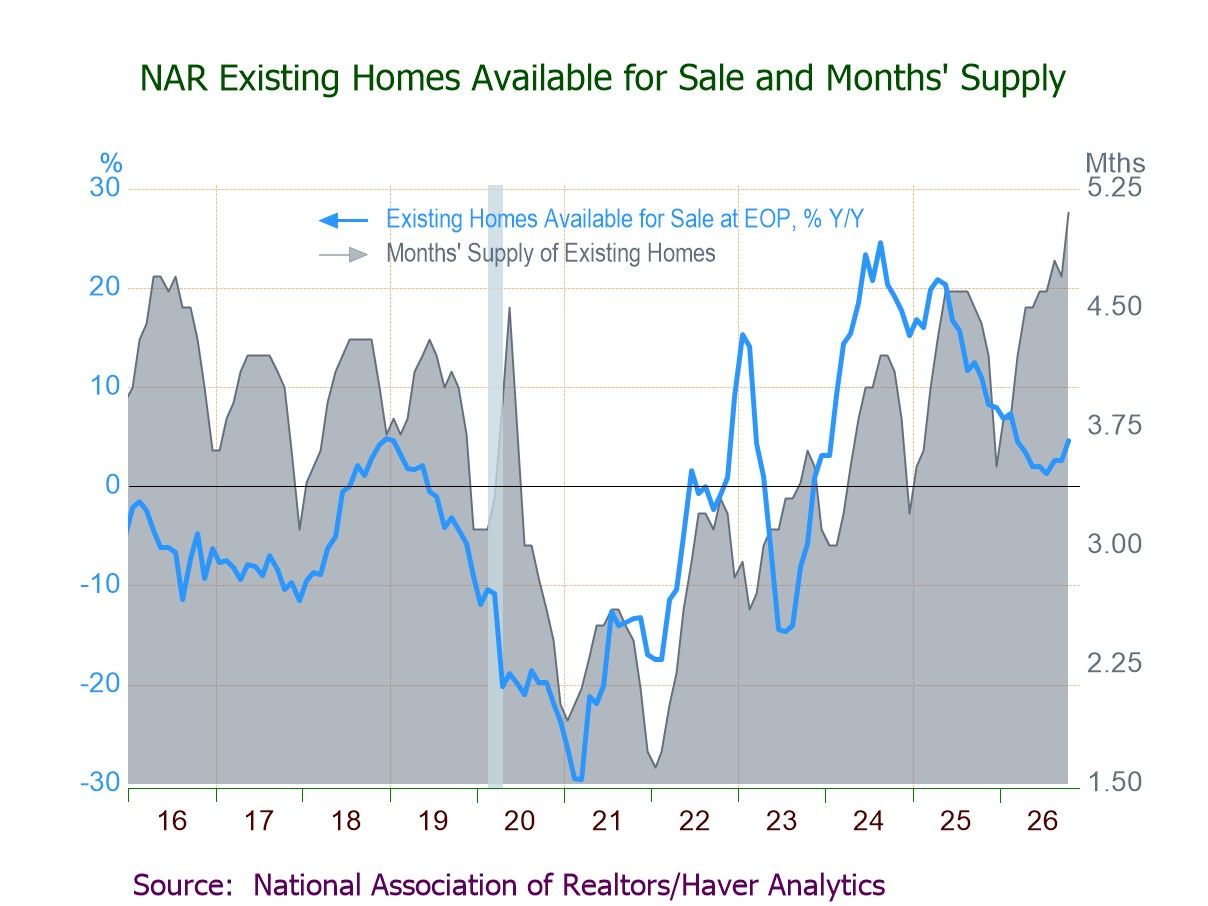
- Unsold inventory +1.3% (+4.6% y/y) to 1.59 mil. units, highest level since Nov. ’19; 5.1 months' supply, highest since Nov. ’15.
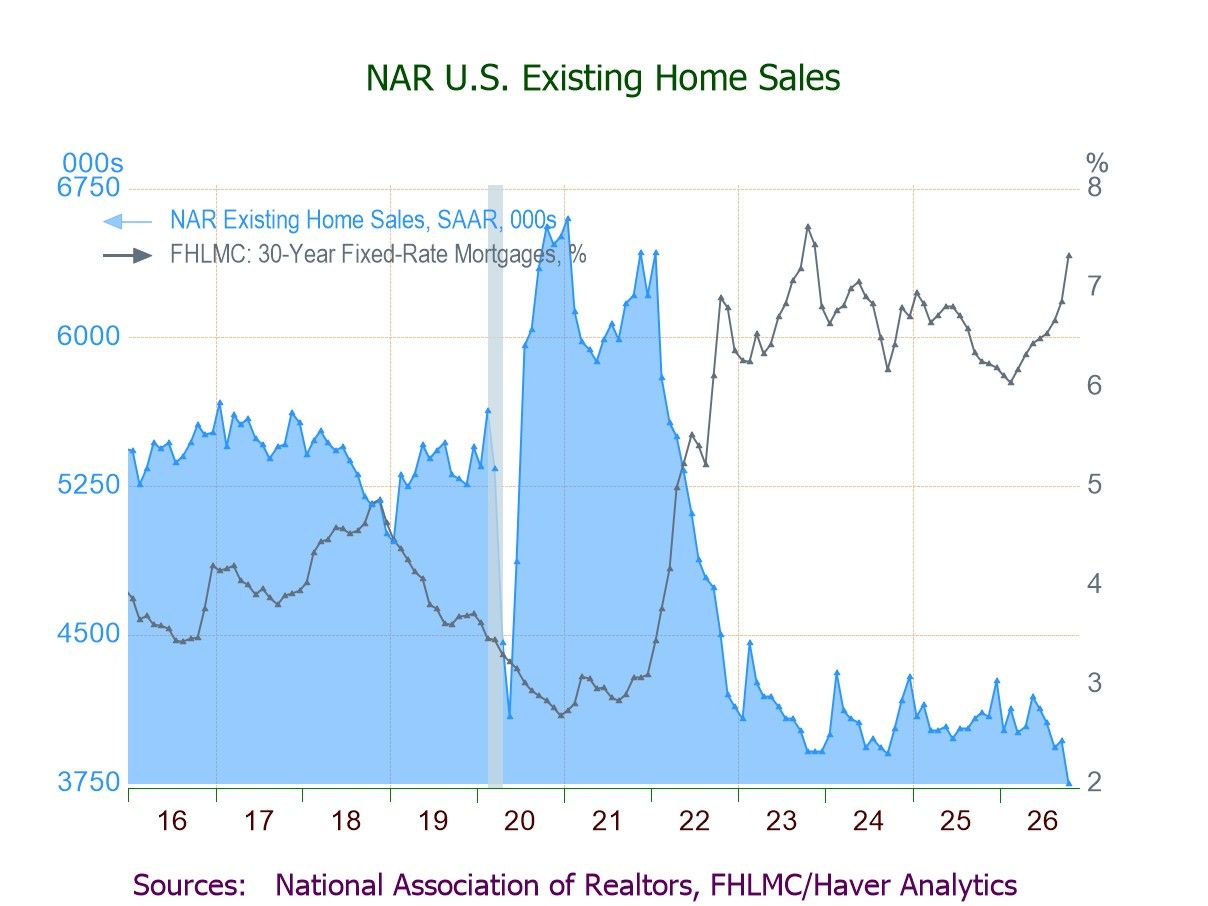
Existing home sales fell 5.5% m/m (-8.8% y/y) to a lower-than-expected 3.75 million units (SAAR) in October, the fourth monthly fall in five months and the lowest level since August 2010, after a 1.0% increase to 3.97 million in September (previously +1.5%; 3.99 mil.), data from the National Association of Realtors (NAR) showed, indicating that affordability constraints, particularly high mortgage rates, continued to suppress housing demand. The Action Economics Forecast Survey had expected October sales of 3.86 million units. Sales were 41.7% below a high of 6.43 million in January 2022 and 43.2% below a peak of 6.60 million in January 2021. The October decrease coincided with a rise in the average 30-year fixed mortgage rate to 7.33%, the highest since November 2023, after increasing to 6.86% in September, according to Freddie Mac. The sales figures are based on closings of sales contracts signed over the past couple of months.
Existing single-family home sales dropped 5.8% (-8.6% y/y) to 3.41 million units in October, the fourth m/m decline in five months and the lowest level since October 2010, reversing a 1.4% gain to 3.62 million in September; sales were 40.2% below a high of 5.70 million in January 2022. Sales of condos and co-ops slid 2.9% (-10.5% y/y) to 340,000 in October, the third consecutive m/m slide and a record low, after a 2.8% decrease to 350,000 in September, remaining 53.4% below a high of 730,000 in January 2022.
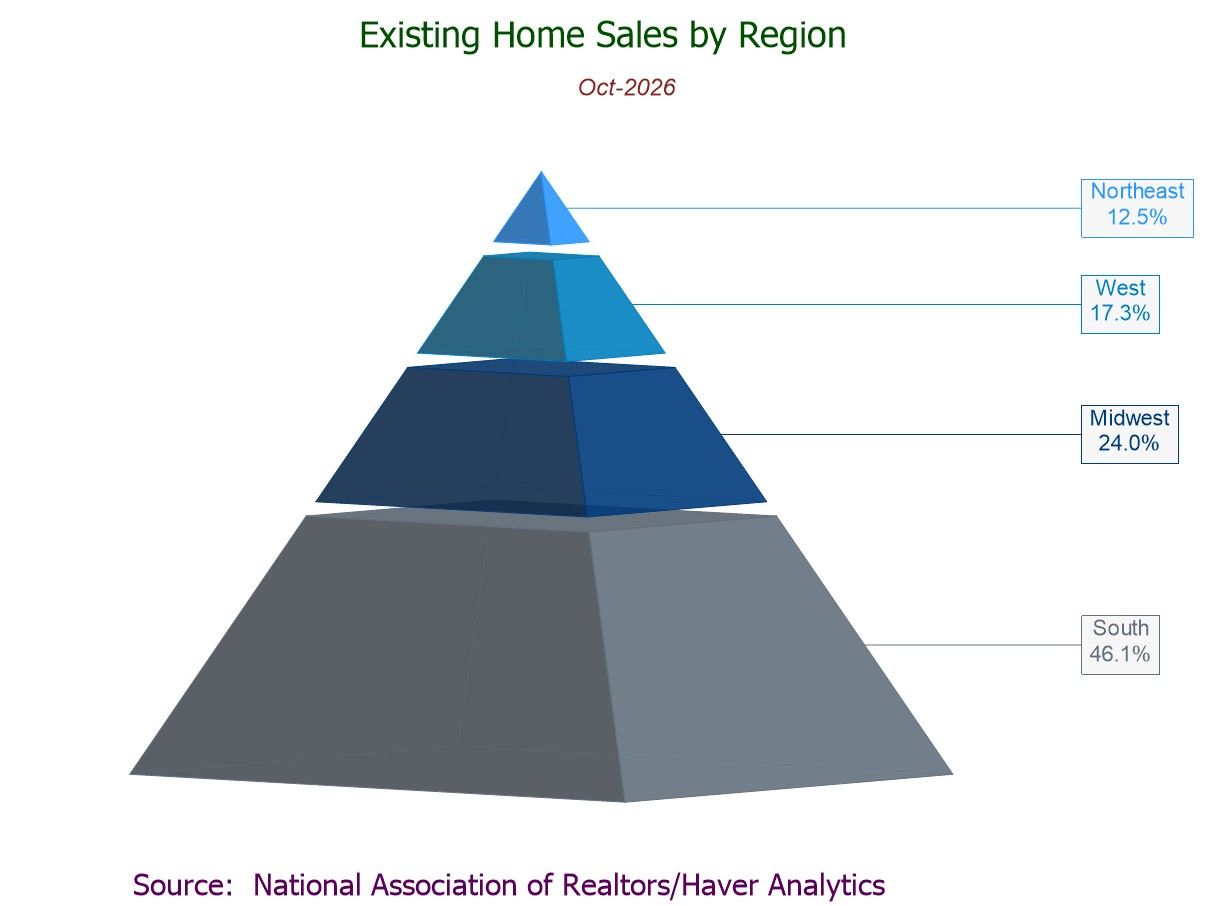
Regionally, October existing home sales declined m/m in all regions except the Northeast, where they were flat. Sales in the West dropped 9.7% (-14.5% y/y) to 650,000 in October, the lowest level on record, following a 1.4% rebound in September. Sales in the South fell 6.5% (-8.0% y/y) to 1.73 million, the lowest reading since January 2012, after a 2.2% September rise. Sales in the Midwest slid 3.2% (-8.2% y/y) to 900,000, the lowest level since July 2011, after registering at 930,000 in September and August. Sales in the West, South, and Midwest posted the fourth m/m decrease in five months. Meanwhile, sales in the Northeast held steady m/m (-4.1% y/y) at 470,000 in October, matching the lowest reading since May, after a 2.1% slide in September. Notably, the South remained the dominant region, accounting for 46.1% of total U.S. existing home sales.
The median price of all existing homes (NSA) slipped 0.4% (+0.4% y/y) to $416,700 in October, the fourth successive m/m decline and the lowest since March, on top of a 2.2% decrease to $418,200 in September ($417,500 previously). Prices remained 15.5% above a low of $360,800 in January 2023. The median price of an existing single-family home slid 0.4% (+0.4% y/y) to $421,900 in October, down for the fourth straight month and the lowest since April, after a 2.3% fall to $423,600 in September. The median price of condos and co-ops, however, rose 0.7% (0.3% y/y) to $365,100, the first m/m rise since June, following a 2.1% September slide to $362,400. Regionally, overall prices fell m/m in October in the Midwest (-2.4%; +1.5% y/y), Northeast (-0.2%; +3.2% y/y), and South (-0.1%; -0.4% y/y), but rebounded m/m in the West (+2.0%; 0.0% y/y).
Inventories of homes for sale climbed to the highest level since November 2019. The number of existing homes for sale (NSA) advanced 1.3% (4.6% y/y) to 1.59 million units in October after holding steady at 1.57 million during the May to September period. The supply of homes on the market at the current selling rate (NSA) rose to 5.1 months in October, matching the highest level since November 2015, from 4.7 months in September. A record low in supply of 1.6 months was in January 2022.
The data on existing home sales, prices and affordability are compiled by the National Association of Realtors. The data on single-family home sales extend back to February 1968. Total sales and price data and regional sales can be found in Haver's USECON database. Regional price and affordability data and national inventory data are available in the REALTOR database. Mortgage interest rates can be found in the WEEKLY database. The expectations figure is from the Action Economics Forecast Survey, reported in the AS1REPNA database.

Winnie Tapasanun
AuthorMore in Author Profile »Winnie Tapasanun has been working for Haver Analytics since 2013. She has 20+ years of working in the financial services industry. As Vice President and Economic Analyst at Globicus International, Inc., a New York-based company specializing in macroeconomics and financial markets, Winnie oversaw the company’s business operations, managed financial and economic data, and wrote daily reports on macroeconomics and financial markets. Prior to working at Globicus, she was Investment Promotion Officer at the New York Office of the Thailand Board of Investment (BOI) where she wrote monthly reports on the U.S. economic outlook, wrote reports on the outlook of key U.S. industries, and assisted investors on doing business and investment in Thailand. Prior to joining the BOI, she was Adjunct Professor teaching International Political Economy/International Relations at the City College of New York. Prior to her teaching experience at the CCNY, Winnie successfully completed internships at the United Nations. Winnie holds an MA Degree from Long Island University, New York. She also did graduate studies at Columbia University in the City of New York and doctoral requirements at the Graduate Center of the City University of New York. Her areas of specialization are international political economy, macroeconomics, financial markets, political economy, international relations, and business development/business strategy. Her regional specialization includes, but not limited to, Southeast Asia and East Asia. Winnie is bilingual in English and Thai with competency in French. She loves to travel (~30 countries) to better understand each country’s unique economy, fascinating culture and people as well as the global economy as a whole.
More Economy in Brief
 Global