

Are Wages Keeping Pace? Analyzing the Data Correctly and Avoiding Mixing Apples and Oranges
|in:Viewpoints
With the U.S. economy growing at a healthy clip and unemployment low, many people ask: Are workers paid appropriately? The rise in stock market valuations, high home prices and the soaring wealth of artificial-intelligence innovators make the question even more urgent. On a topic so central to fairness and living standards, it’s important to use data that carefully measure and evaluate compensation. In particular, the benchmarks we look to need to account for inflation and reflect worker productivity.
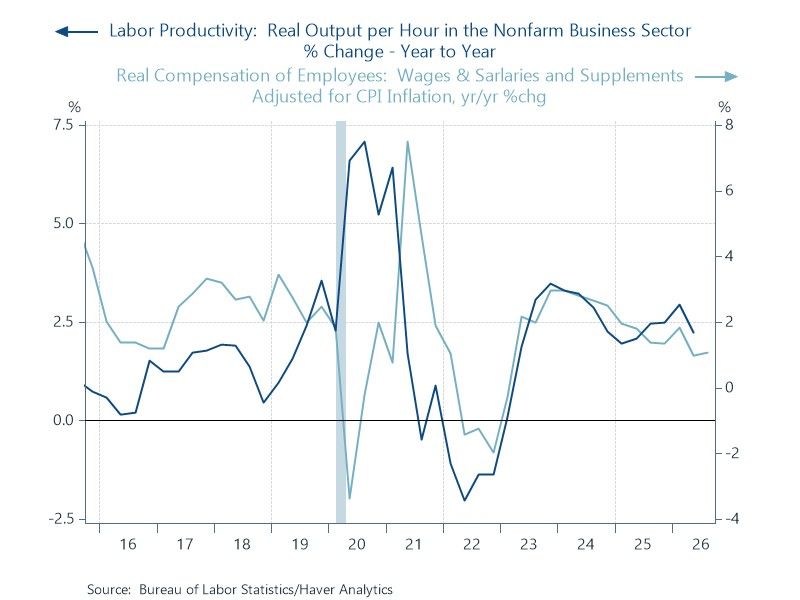
In the years prior to Covid, when adjusted for inflation, show that wage compensation—total wages and salaries plus supplements such as employer contributions to pensions and savings plans—closely tracked productivity gains (Chart 1). The 2020s have been a different story. Wages have increased significantly, but persistently high inflation has undercut those gains. Consequently, while real wages have increased, they haven’t kept pace with worker productivity. No wonder surveys show Americans losing confidence in the economy. Persistent inflation is the culprit.
Chart 1. Real Compensation and Labor Productivity
Another measure that is getting a lot of attention but is highly misleading is the labor-compensation share of gross domestic product. It shows how much wages have fallen relative to GDP. Critics compare the labor-compensation share with the ratios of profits and returns to capital to GDP, which are rising. Too many economists who refer to these ratios and base their observations on them do not carefully think about what their numerators and denominators measure and what they don’t--and inadvertently are mixing apples and oranges.
In fact, in an advancing economy with healthy growth and innovations, it’s natural and unsurprising that the labor-compensation share of GDP falls while profits and returns to capital rise. Chart 2 shows wage compensation as a percent of GDP, often referred to as the “labor share”. Chart 3 shows corporate operating profits, the S&P500 (including dividend reinvestment) and nominal GDP, all indexed to 2000=100. Profits and returns to capital are rising sharply as a share of GDP.
Chart 2. Labor Share: Wage Compensation as a % of GDP
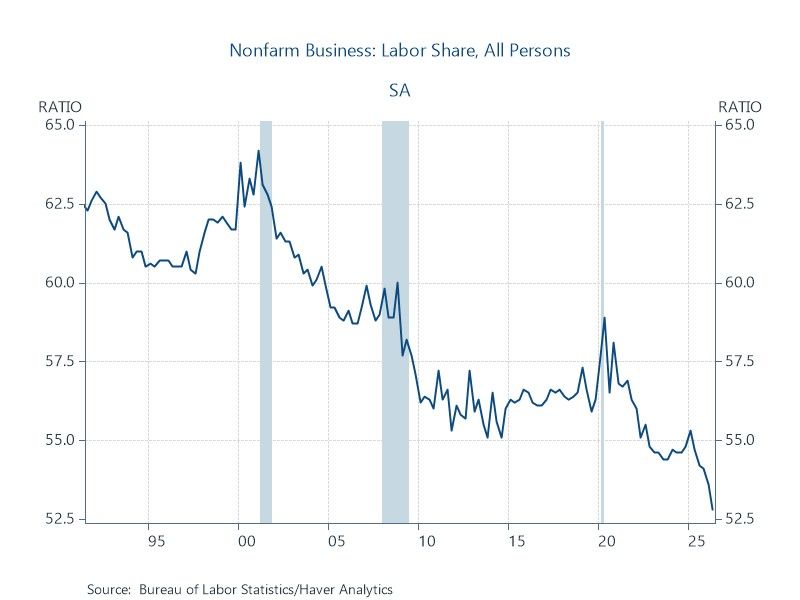
Chart 3. Profits and S&P 500 Total Returns, 2000=100
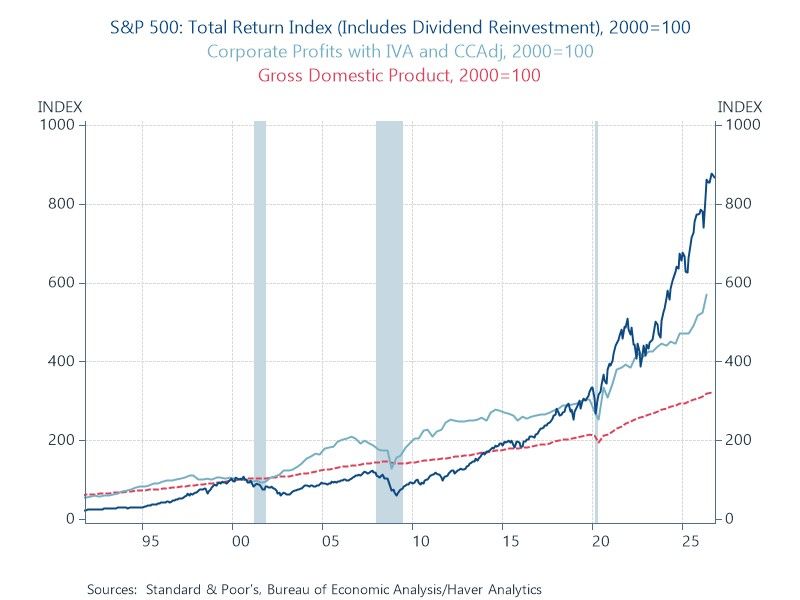
Thinking through the data, particularly what GDP measures and what it doesn’t, helps to explain how rising profits and returns to capital are largely complements to worker compensation and enhance economic well-being. Yet this measure of wage compensation to GDP is widely used to suggest that companies and capitalists are getting ahead at the expense of workers.
I would like to see wage compensation to rise and catch up to productivity gains. The persistent inflation makes it an uphill struggle. Many businesses may find that raising worker compensation reduces job turnover and lowers business operating costs and improves business efficiency. But in any case, misusing data muddles the issue.
GDP measures what is produced in the U.S. by both domestic and foreign companies. In its most familiar expenditure form, GDP covers consumption and business and residential investment spending (largely spending on new construction and improvements) and government purchases (largely spending that absorbs national resources but not transfer payments like Social Security) plus exports minus imports. (U.S. National income, a closely related counterpart to GDP, measures the total income earned by residents, but diverges from GDP in the short-run, reflecting changes in net income from abroad, capital depreciation and statistical discrepancies. Like GDP, it is not a good basis for evaluating the fairness of worker wage compensation).
You can see how the labor share in Chart 1 can be misinterpreted. When businesses increase investment—say, for new computers or a new production facility-- it adds arithmetically to GDP and lowers the ratio of wages to GDP. Yet the investment is clearly a positive for the economy and enhances workers’ productive capacity.
It’s important to keep in mind what GDP doesn’t include, and here’s how comparing the labor share of GDP to profits or returns to capital as a percent of GDP is flawed analysis. While U.S. workers are compensated for their contributions to domestic production, U.S. businesses’ activities overseas, involving overseas employees (either U.S. citizens or foreign) and production generate profits and boost returns on capital, but are largely uncounted in U.S. GDP.
Among S&P 500 companies, an estimated one-third of employees work overseas and one-third of revenues and an even higher share of profits are generated overseas. Smaller firms have substantially less international activity, but the overseas activities of large multinational U.S. firms significantly affect the aggregate data. Goods produced overseas by subsidiaries of U.S. businesses are counted in GNP (gross national product) but not GDP. Goods produced overseas by non-U.S. firms that are critical part of supply chains of U.S. companies also largely fall outside of U.S. GDP. Nevertheless, they too may add significantly to the well-being of U.S. consumers and provide net benefits to U.S. workers. No wonder profits and returns to capital are rising compared to GDP.
Apple Inc. is a good modern example of a U.S.-based company that relies heavily on overseas production and global supply chains. Nearly all of Apple’s iPhones, laptops and other hardware are made and assembled overseas by companies that aren’t subsidiaries of Apple. Those Apple products sold internationally (60% to 65%) don’t show up in U.S. GDP. The 35% to 40% of Apple goods that are purchased in the U.S. have little impact on GDP, as imports largely offset domestic consumption. But they have boosted Apple’s profits, and have helped lift its capitalization to around $5 trillion. The economic benefits to U.S. consumers and Apple’s 80,000 domestic employees and many other U.S. workers are obvious. Such benefits are not reflected by comparing the labor share of GDP to the ratios of profits and returns to capital divided by GDP.
U.S. workers’ far larger concern is the persistent inflation that has raised the consumer-price index more than 30% since late 2019. For many working households, prices of necessities have risen even faster (Charts 4 and 5). Food prices are up more than 34%, and the cost of childcare and preschool more than 31%. Gasoline prices are up 54%, and automobile insurance and maintenance combined are up about 50%. For the 34% of households that don’t own their dwellings, rental costs are up 34%. Taxes, too, cut into take-home pay.
Chart 4. CPI and Select Components, Indexed Dec 2019=100
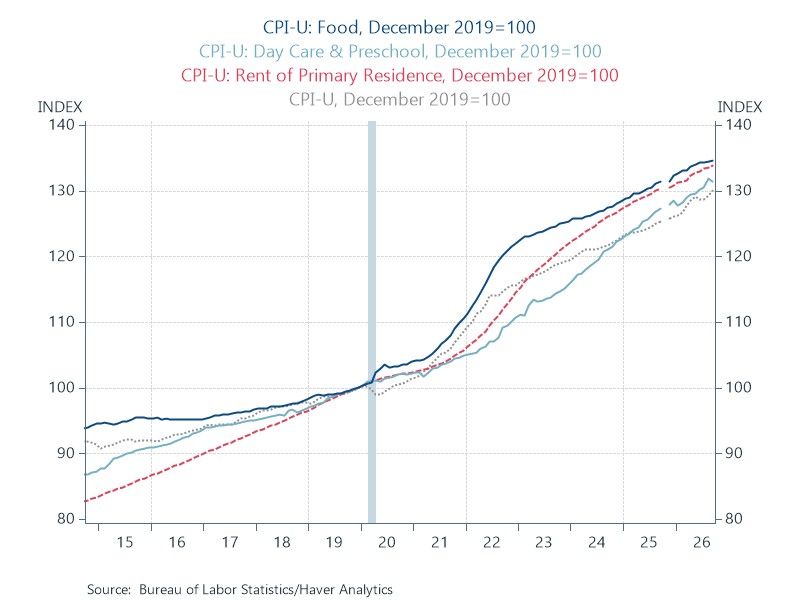
Chart 5. CPI and Select Components, Indexed Dec 2019=100
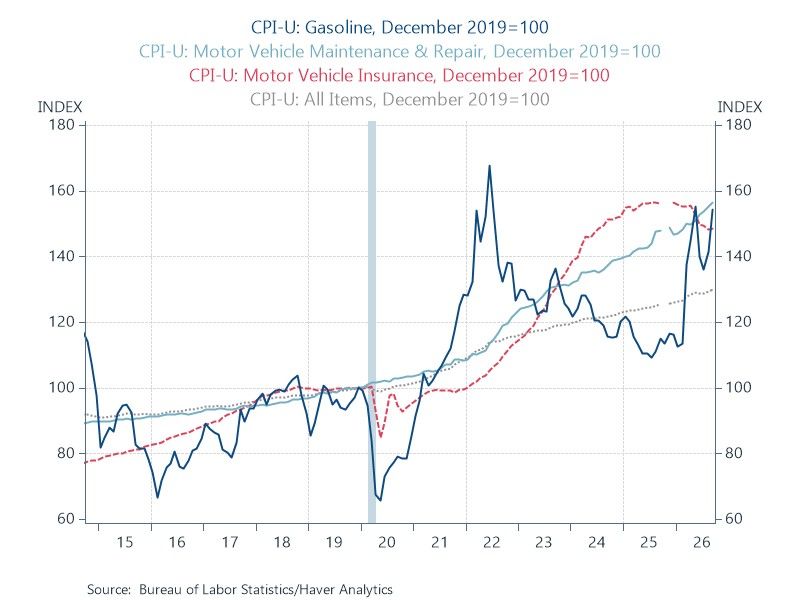
Chart 6. Case Shiller Home Price Index and CPI, December 2019=100
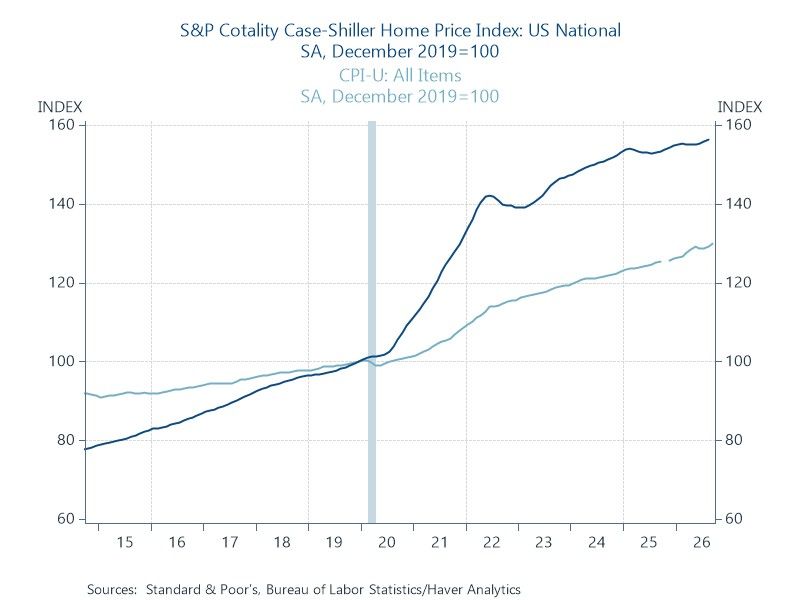
Employment gains and low unemployment help, but the Fed’s excessive monetary easing has contributed to persistent high inflation and the increased value of long-lived asset prices, benefitting homeowners and stockholders. The Federal Reserve’s consecutive zero rates and extensive purchases of mortgage-backed securities in 2020-21 helped boost housing values more than 50%, but that raised costs for renters and put home prices out of reach for many potential buyers (Chart 6). Note that the Fed’s target of 2% inflation means prices will still rise but at a slower pace. The Fed should achieve its 2% target. After that, however, it should seriously reconsider its notion that 2% inflation amounts to price stability.

Mickey D. Levy
AuthorMore in Author Profile »Mickey Levy is a macroeconomist who uniquely analyzes economic and financial market performance and how they are affected by monetary and fiscal policies. Dr. Levy started his career conducting research at the Congressional Budget Office and American Enterprise Institute, and for many years was Chief Economist at Bank of America, followed by Berenberg Capital Markets. He is a Visiting Fellow at the Hoover Institution at Stanford University and a long-standing member of the Shadow Open Market Committee.
Dr. Levy is a leading expert on the Federal Reserve’s monetary policy, with a deep understanding of fiscal policy and how they interact. He has researched and spoken extensively on financial market behavior, and has a strong track record in forecasting. Dr. Levy’s early research was on the Fed’s debt monetization and different aspects of the government’s public finances. He has written hundreds of articles and papers for leading economic journals on U.S. and global economic conditions. He has testified frequently before the U.S. Congress on monetary and fiscal policies, banking and credit conditions, regulations, and global trade, and is a frequent contributor to the Wall Street Journal.
He is a member of the Council on Foreign Relations and the Economic Club of New York, and previously served on the Panel of Economic Advisors to the Federal Reserve of New York, as well as the Advisory Panel of the Office of Financial Research.
Dr. Levy holds a Ph.D. in Economics from University of Maryland, a Master’s in Public Policy from U.C. Berkeley, and a B.A. in Economics from U.C. Santa Barbara.
 Global