U.S. Trade Deficit Narrowed Slightly in September
by:Sandy Batten
|in:Economy in Brief
Summary
- The deficit in goods and services narrowed to $105.0 billion in September from $105.7 billion in August.
- This capped off a quarter in which the trade deficit widened markedly, subtracting 3.3%-points from overall GDP.
- The goods deficit narrowed to $135.9 billion in September, while the services surplus was essentially unchanged at $30.9 billion.
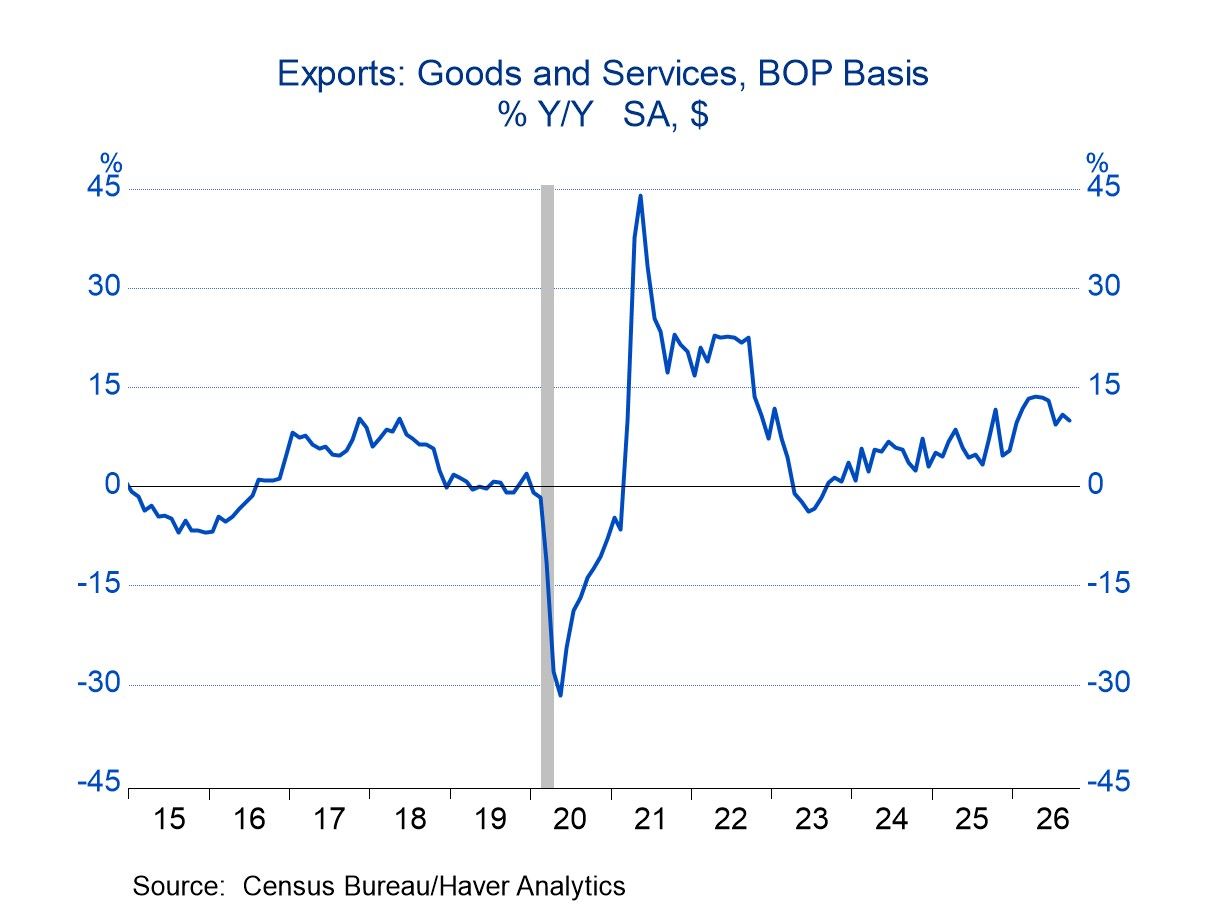
- Exports rose 1.9% m/m, led by strong increases in exports of food and feeds and of capital goods.
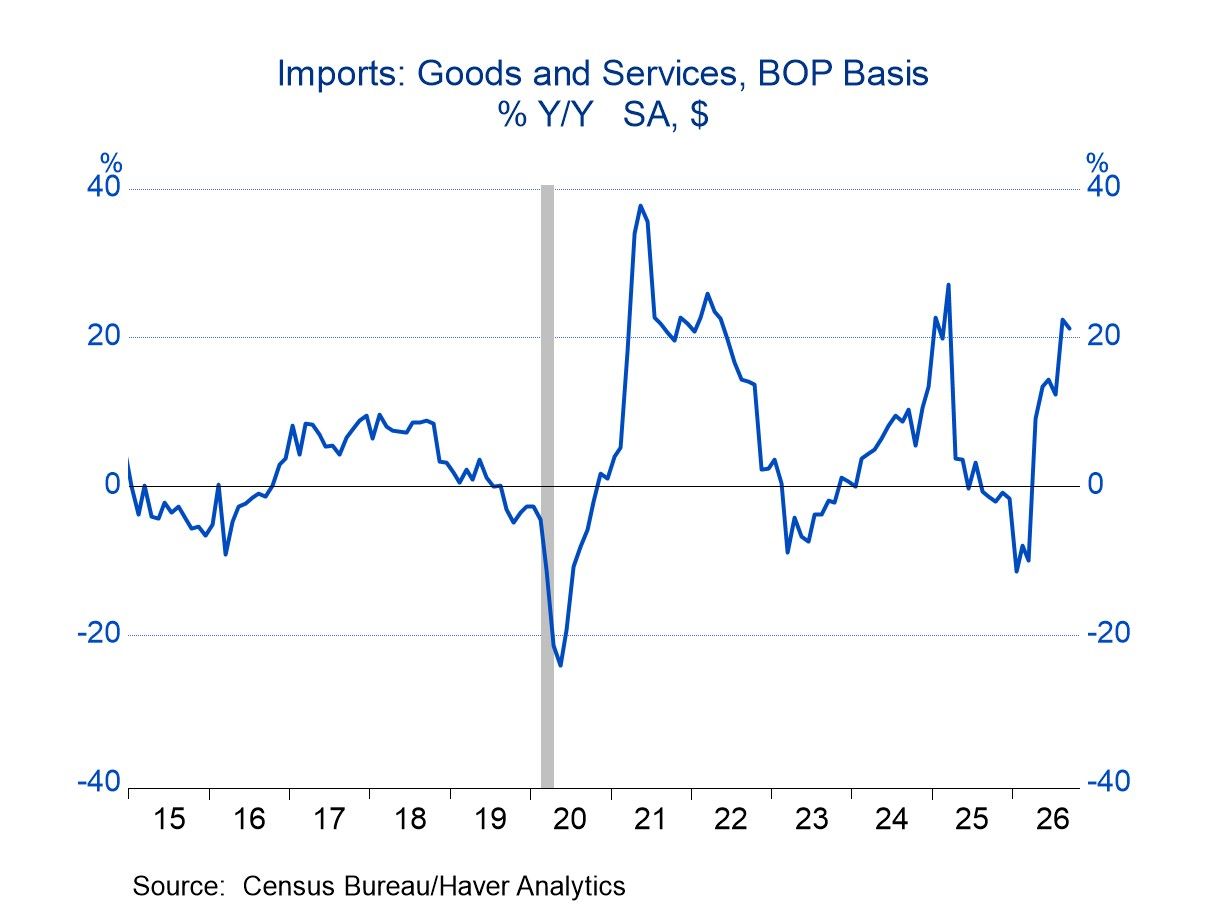
- Imports increased by 1.2% m/m, once again dominated by increased AI-related capital goods imports.
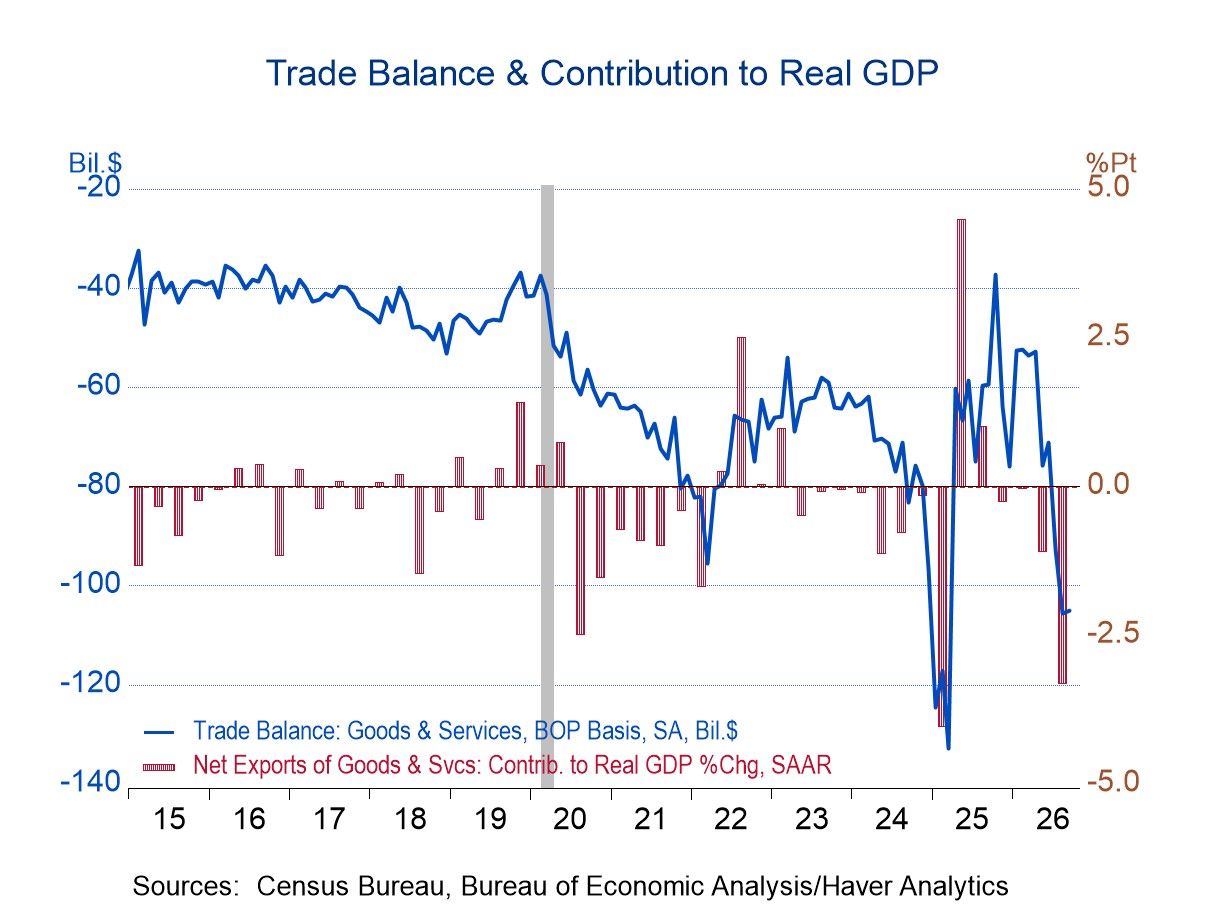
The U.S. trade deficit in goods and services (BOP basis) narrowed slightly to $105.0 billion in September from an upwardly revised $105.7 billion in August (previously -$105.6 billion), according to the U.S. Census Bureau. The Action Economics Forecast Survey looked for a deficit of $107.9 billion. The goods deficit narrowed to $135.9 billion in September from $136.6 billion in August while the services surplus was essentially unchanged at +$30.9 billion.
The real (inflation-adjusted) trade deficit in goods widened to $119.5 billion (2017$) in September from $116.0 billion in August. For all of Q3, the real deficit totaled $341.6 billion versus $277.8 billion in August. This marked widening in the real deficit was already noted in the release of the first estimate of real GDP for Q3 where it was reported that the widening of the trade deficit subtracted 3.3%-points from overall real GDP growth in Q3.
Exports of goods and services increased 1.9% m/m (+10.0% y/y) in September on top of a 1.6% monthly gain in August. These two consecutive months of increased exports followed three consecutive monthly declines. Goods exports (Census basis) rose 2.5% m/m (12.6% y/y) in September, the largest monthly gain since April. Increases were widely spread across major end-use categories. Exports of food and feeds jumped 13.3% m/m, the largest monthly increase since October 2021. Exports of capital goods excluding autos increased 5.5% m/m, the third consecutive monthly rise. Exports of consumer goods ex autos increased 3.7% m/m, the third increase in the past four months. By contrast, auto exports slumped 5.6% m/m, the third consecutive monthly decline and the fifth decline in the past six months. Services exports increased 0.7% m/m (+4.4% y/y) in September following a 0.3% monthly rise in August. Transport exports increased 0.8% m/m; travel was up 1.8% m/m; charges for the use of intellectual property rose 0.6% m/m, the fourth consecutive monthly gain.
Imports of goods and services increased 1.2% m/m (21.3% y/y) in September, a slowdown from a 4.4% monthly gain in August. Goods imports (Census basis) increased 2.4% m/m (28.2% y/y) in September but were generally weak apart from imports of capital goods with goods imports declining in four of the six major end-use categories. The importance of AI-related investment continued to dominate with imports of capital goods ex autos up 7.9% m/m (77.8% y/y). In the past three months, capital goods imports have risen 25.5%. Excluding capital goods imports, the remainder of imports fell 1.9% m/m, the third monthly decline in the past four months. Imports of consumer goods ex autos rose 4.1% m/m in September, more than offsetting a 0.8% monthly decline in August. Service imports increased 1.0% m/m (3.0% y/y) in September following a 0.5% m/m increase in August. The September increase was led by a 1.8% m/m gain in transport imports and a 3.4% m/m gain in travel imports.
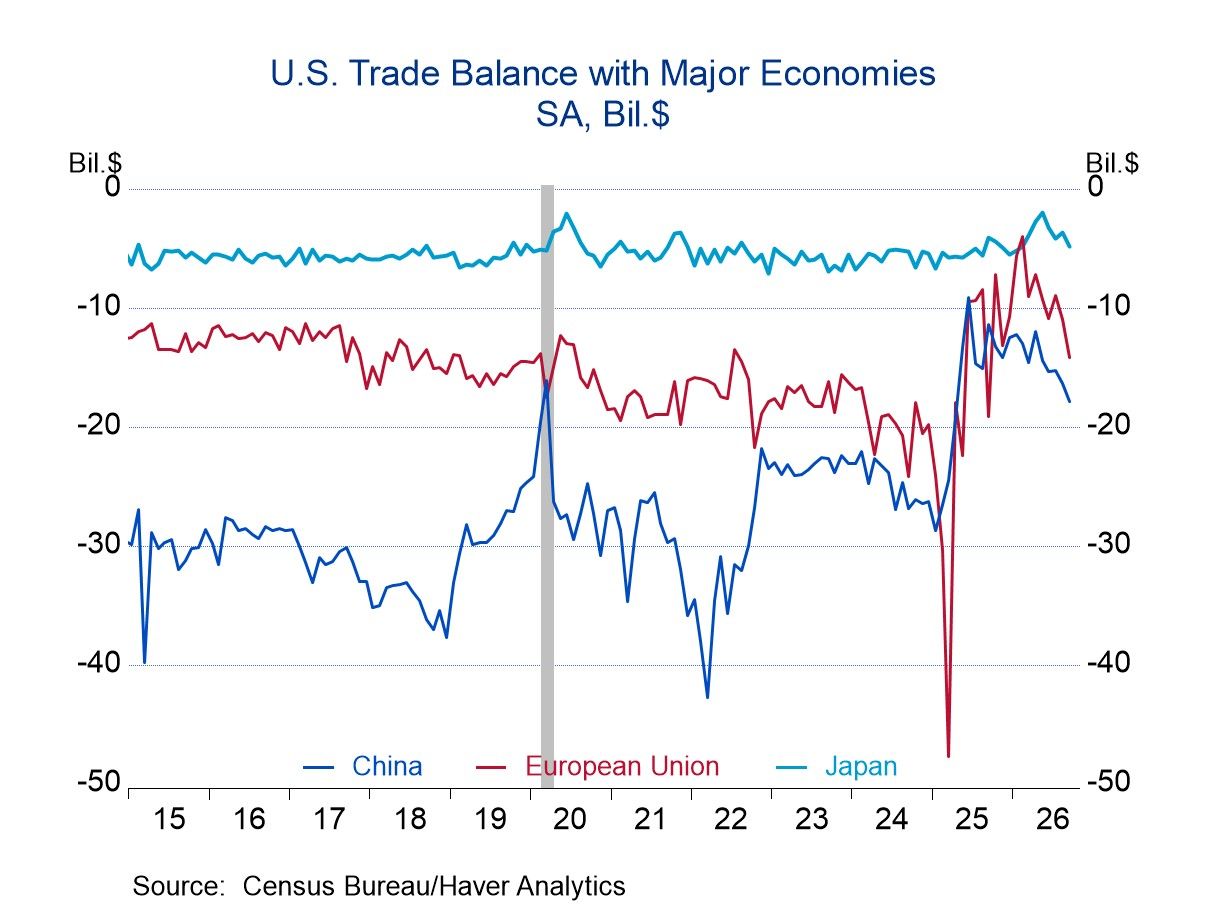
By country, the goods trade deficit with China widened to $17.9 billion in September from $16.4 billion in August. This was the widest deficit with China since April 2025. The trade deficit with the European Union widened to $14.2 billion in September from $11.0 billion in August. The trade deficit with Japan increased to $4.8 billion in September from $3.7 billion in August.
The international trade data can be found in Haver’s USECON database. Detailed figures on international trade are available in the USINT and USTRADE databases. The expectations figures are from the Action Economics Forecast Survey in AS1REPNA.
Sandy Batten
AuthorMore in Author Profile »Sandy Batten has more than 30 years of experience analyzing industrial economies and financial markets and a wide range of experience across the financial services sector, government, and academia. Before joining Haver Analytics, Sandy was a Vice President and Senior Economist at Citibank; Senior Credit Market Analyst at CDC Investment Management, Managing Director at Bear Stearns, and Executive Director at JPMorgan. In 2008, Sandy was named the most accurate US forecaster by the National Association for Business Economics. He is a member of the New York Forecasters Club, NABE, and the American Economic Association. Prior to his time in the financial services sector, Sandy was a Research Officer at the Federal Reserve Bank of St. Louis, Senior Staff Economist on the President’s Council of Economic Advisors, Deputy Assistant Secretary for Economic Policy at the US Treasury, and Economist at the International Monetary Fund. Sandy has taught economics at St. Louis University, Denison University, and Muskingun College. He has published numerous peer-reviewed articles in a wide range of academic publications. He has a B.A. in economics from the University of Richmond and a M.A. and Ph.D. in economics from The Ohio State University.
More Economy in Brief