

U.S. Factory Orders Up More Than Expected in September on Strong Nondefense Aircraft Orders
Summary
- Factory orders +1.8% (+10.5% y/y) in Sept., third straight m/m rise; 17.6% above the Jan. ’24 low.
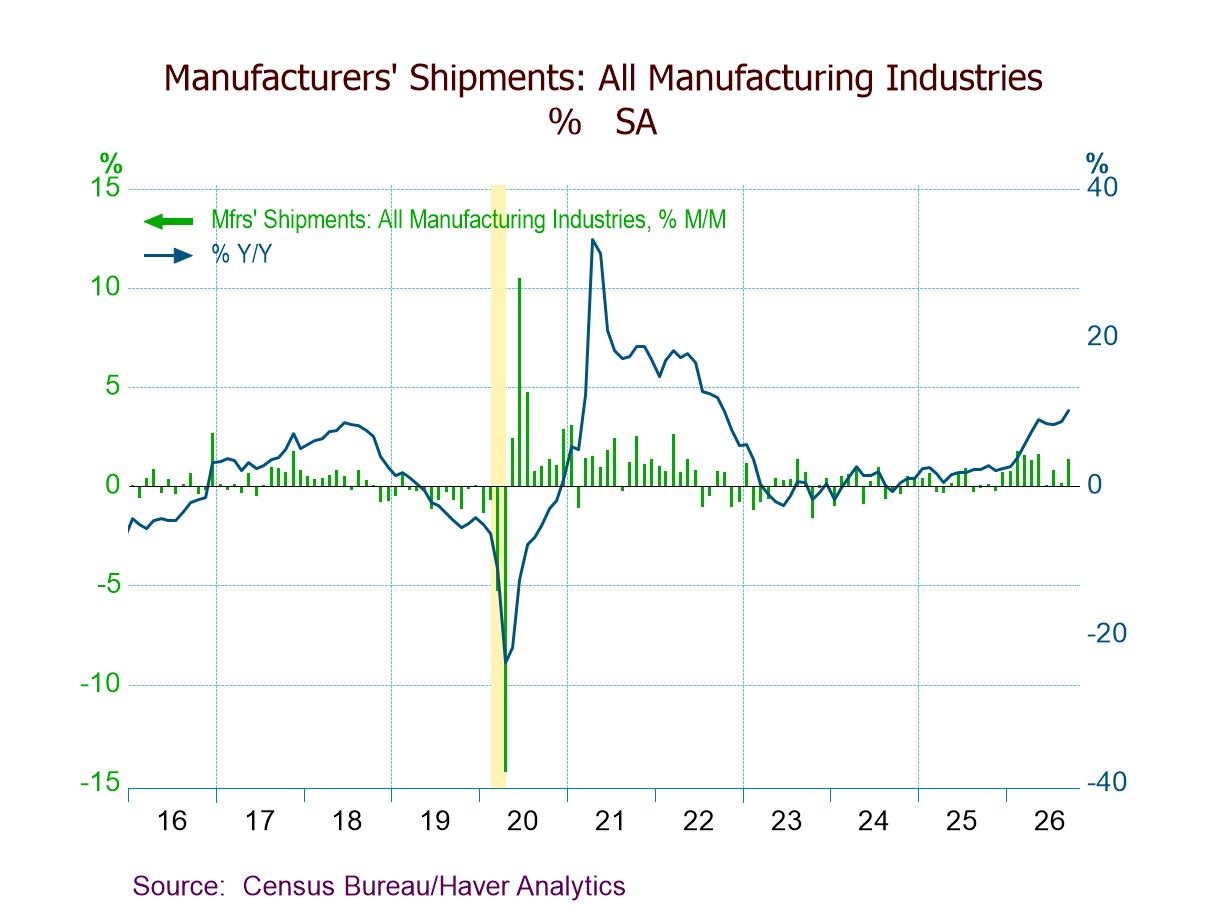
- Durable goods orders +1.9%, fourth consecutive m/m increase; nondurable goods orders +1.8% and shipments +1.3%, ninth m/m gains in 10 mths.
- Transportation orders +4.6%, led by a 28.3% jump in nondefense aircraft orders.
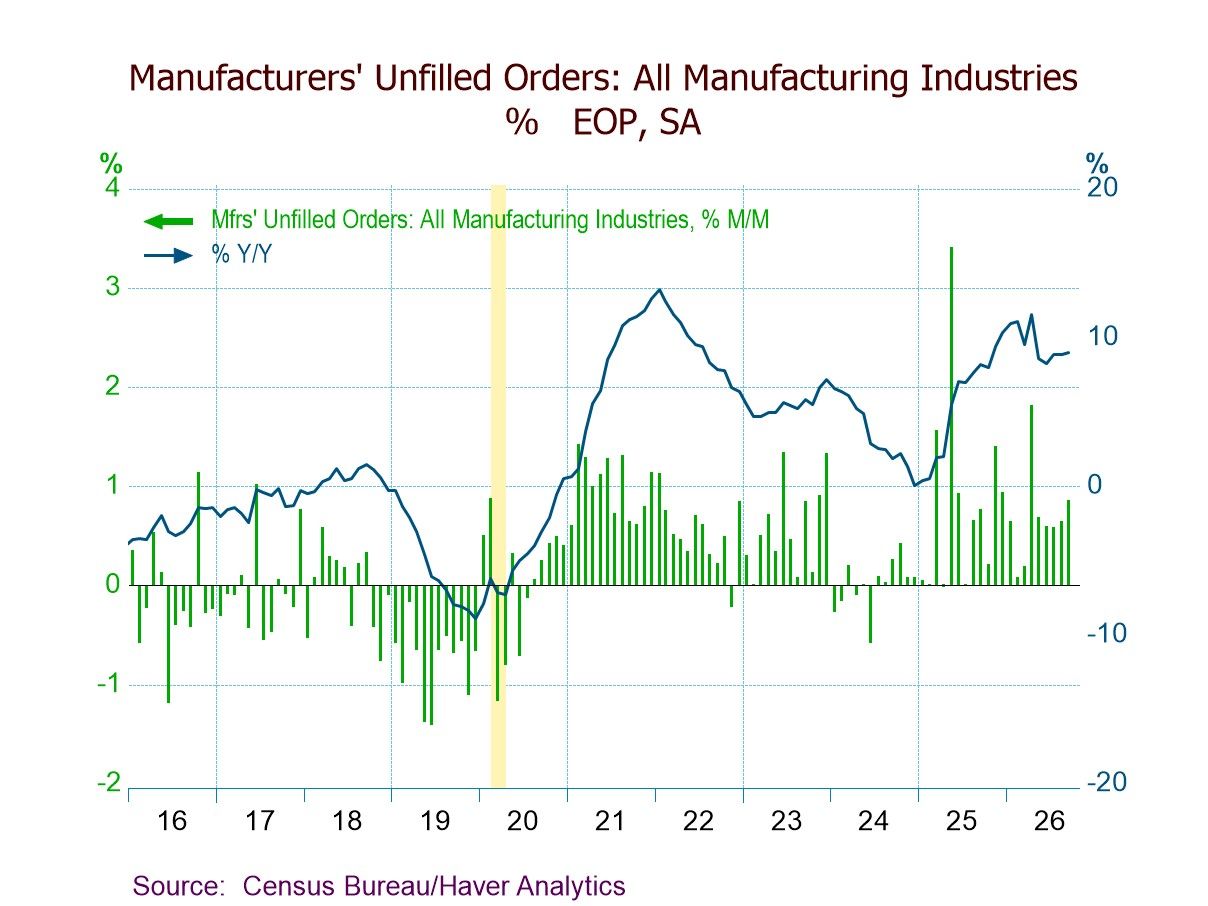
- Unfilled orders +0.9%, up for the 14th month running.
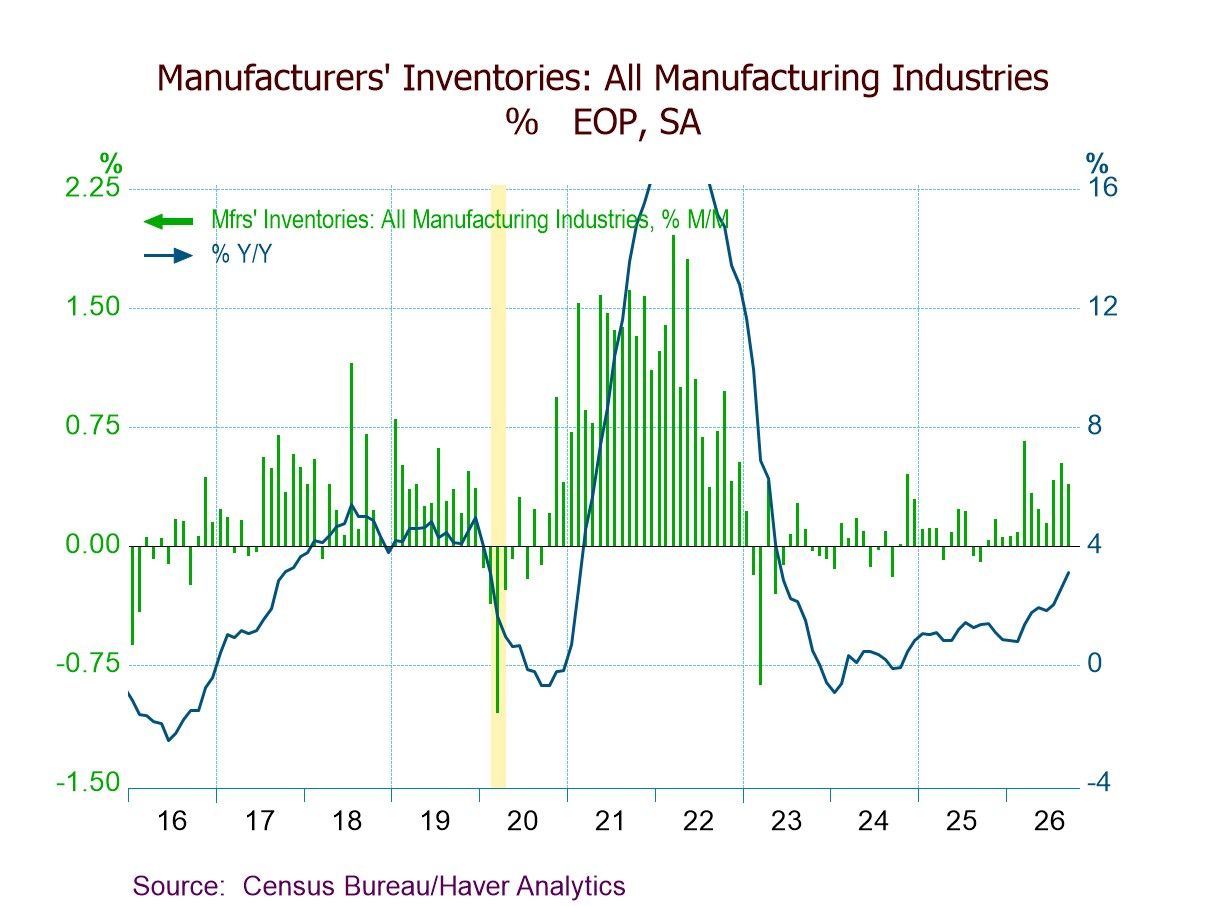
- Inventories +0.4%, 11th successive m/m increase.
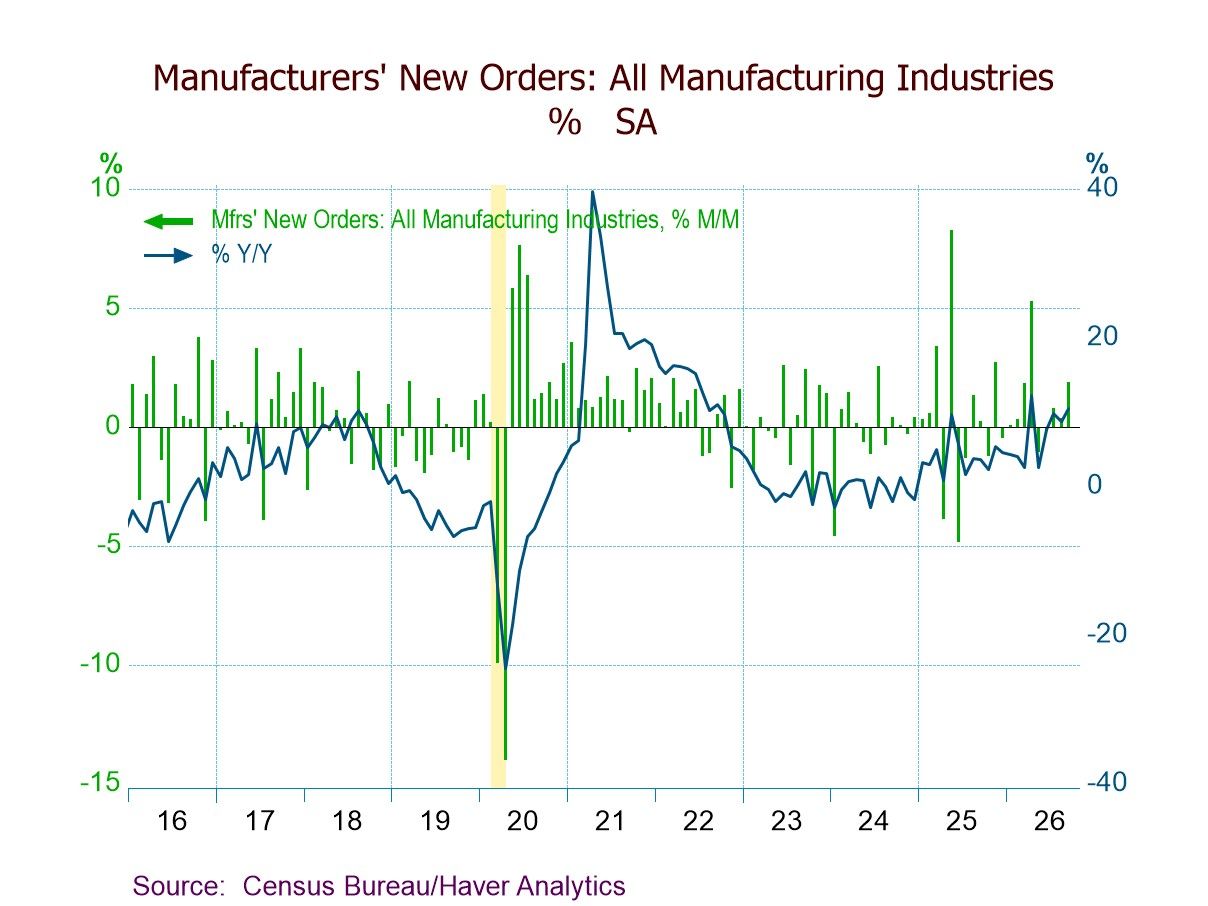
Total factory orders rose a more-than-expected 1.8% m/m in September, the third straight monthly rise, after a 0.3% increase in August, according to data from the U.S. Census Bureau. The Action Economics Forecast Survey had expected a 1.2% m/m September increase. The year-on-year growth rate accelerated to 10.5% in September, the highest since April, from 8.8% in August (+3.6% in September 2025), while remaining far below the April 2021 peak of 39.6%. Factory orders excluding defense grew 2.0% (10.8% y/y) in September following a 0.4% gain in August, and factory orders excluding the transportation sector climbed 1.3% (11.1% y/y) after a 0.4% rise; both posted the third consecutive m/m increase.
Notably, orders for nondefense aircraft & parts surged 28.3% in September after rises of 0.3% in August and 12.0% in July. Orders for defense aircraft & parts rose 5.8% (-30.7% y/y) following a 2.3% August increase and a 13.0% July drop, while orders for ships & boats fell 9.9% after a 0.7% August decline and a 6.4% July gain.
Durable goods orders advanced 1.9% (10.0% y/y) in September after a 0.1% uptick in August (in line with +1.8% m/m in the advance report on October 27), marking the fourth successive m/m increase and the sixth in seven months. The September m/m gain was led by a 4.6% rebound (8.0% y/y) in transportation equipment, followed by increases of 1.5% (16.3% y/y) in machinery, 0.8% (16.7% y/y) in computers & electronic products, 0.5% (8.6% y/y) in fabricated metal products, and 0.4% (20.3% y/y) in primary metals. In contrast, durable goods orders for electrical equipment, appliances & components (-0.3%; +4.8% y/y) and furniture & related products (-0.3%; +1.3% y/y) declined m/m in September.
Nondurable goods orders, which equal nondurable goods shipments, rose 1.8% (11.0% y/y) in September, the third straight m/m gain and the ninth in 10 months, after a 0.5% rise in August. The September m/m increase was driven by a 5.2% jump (39.7% y/y) in petroleum & coal products, followed by gains of 2.0% (10.4% y/y) in chemical products, 1.3% (2.4% y/y) in beverage & tobacco products, and 0.2% (1.5% y/y) in food products. To the downside, nondurable goods shipments for apparel (-1.9%; +6.9% y/y), leather & allied products (-1.2%; +7.0% y/y), textile mills (-0.9%; -2.8% y/y), paper products (-0.2%; +2.7% y/y), and plastics & rubber products (-0.2%; +3.3% y/y) fell m/m in September. Meanwhile, nondurable goods shipments for printing (+0.3% y/y) and textile products (-0.1% y/y) were virtually unchanged m/m following August’s declines.
Total shipments strengthened 1.3% (10.2% y/y) in September, the third consecutive m/m rise and the ninth in 10 months, after a 0.1% uptick in August. Excluding transportation, shipments grew 1.3% (10.3% y/y), the 10th m/m gain in 11 months, on top of a 0.5% August increase. Shipments of durable goods industries rebounded 0.9% (9.4% y/y), up for the ninth time in 10 months, reversing a 0.2% August decline. This reflected m/m gains in almost all durable goods shipments categories, led by a 1.6% advance (13.6% y/y) in machinery, followed by increases of 1.5% (9.8% y/y) in transportation equipment, 1.4% (9.7% y/y) in computers & electronic products, 0.6% (7.9% y/y) in miscellaneous durable goods, 0.4% (17.8% y/y) in primary metals, 0.3% (7.5% y/y) in fabricated metal products, and 0.1% (2.2% y/y) in wood products. In contrast, durable goods shipments for nonmetallic mineral products (-0.5%; +1.8% y/y) and furniture & related products (-0.4%; +1.1% y/y) fell m/m in September, while those for electrical equipment, appliances & components were essentially unchanged m/m (+5.9% y/y) following seven successive m/m rises.
Unfilled orders rose 0.9% (9.0% y/y) in September, up for the 14th month running, after rising 0.6% in August, July, and June. Excluding transportation, unfilled orders climbed 0.8% (7.8% y/y), also up for the 14th straight month, on top of a 0.9% August rise. Backlogs of durable goods grew 0.9% (9.0% y/y) in September, with m/m gains across categories, led by increases of 2.0% (11.3% y/y) in primary metals, 1.0% (8.3% y/y) in computers & electronic products, and 0.9% (9.7% y/y) in transportation equipment.
Inventories were up 0.4% (3.1% y/y) in September, the 11th consecutive m/m gain, after a 0.5% rise in August. Excluding transportation, inventories rose 0.4% (2.9% y/y), up for the eighth successive month, following a 0.5% August increase. Durable goods inventories grew 0.3% (3.5% y/y) in September, the 12th straight m/m gain, after climbing 0.5% in August, while nondurable goods inventories rose 0.5% (2.5% y/y), the seventh m/m increase in eight months, after rising at the same pace in August.
The factory sector data are available in Haver’s USECON database. The Action Economics Forecast Survey is in the AS1REPNA database.

Winnie Tapasanun
AuthorMore in Author Profile »Winnie Tapasanun has been working for Haver Analytics since 2013. She has 20+ years of working in the financial services industry. As Vice President and Economic Analyst at Globicus International, Inc., a New York-based company specializing in macroeconomics and financial markets, Winnie oversaw the company’s business operations, managed financial and economic data, and wrote daily reports on macroeconomics and financial markets. Prior to working at Globicus, she was Investment Promotion Officer at the New York Office of the Thailand Board of Investment (BOI) where she wrote monthly reports on the U.S. economic outlook, wrote reports on the outlook of key U.S. industries, and assisted investors on doing business and investment in Thailand. Prior to joining the BOI, she was Adjunct Professor teaching International Political Economy/International Relations at the City College of New York. Prior to her teaching experience at the CCNY, Winnie successfully completed internships at the United Nations. Winnie holds an MA Degree from Long Island University, New York. She also did graduate studies at Columbia University in the City of New York and doctoral requirements at the Graduate Center of the City University of New York. Her areas of specialization are international political economy, macroeconomics, financial markets, political economy, international relations, and business development/business strategy. Her regional specialization includes, but not limited to, Southeast Asia and East Asia. Winnie is bilingual in English and Thai with competency in French. She loves to travel (~30 countries) to better understand each country’s unique economy, fascinating culture and people as well as the global economy as a whole.
More Economy in Brief
 Global