U.S. Empire State Manufacturing Index Cools Sharply in September
Summary
- General Business Conditions Index down 13.0 pts. to 7.6 in Sept.; sixth straight expansion.
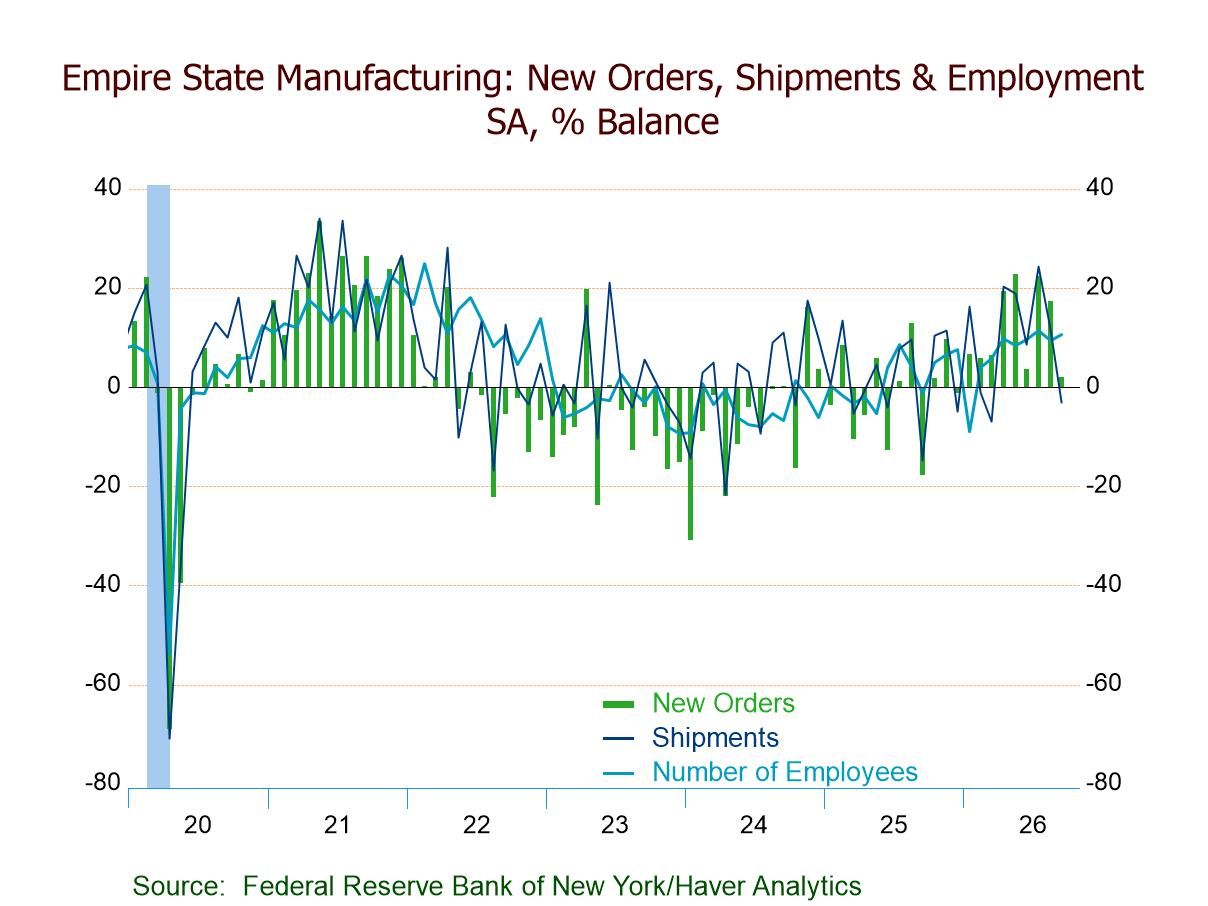
- New orders (2.0), down 15.3 pts.; weakest level since Dec. ’25, still indicating expansion.
- Shipments (-3.2), down 14.9 pts.; first negative reading since March.
- Unfilled orders (5.9), down 9.6 pts. but staying positive; inventories (8.9), highest since May.
- Employment (10.6), up 1.3 pts.; eighth consecutive expansion.
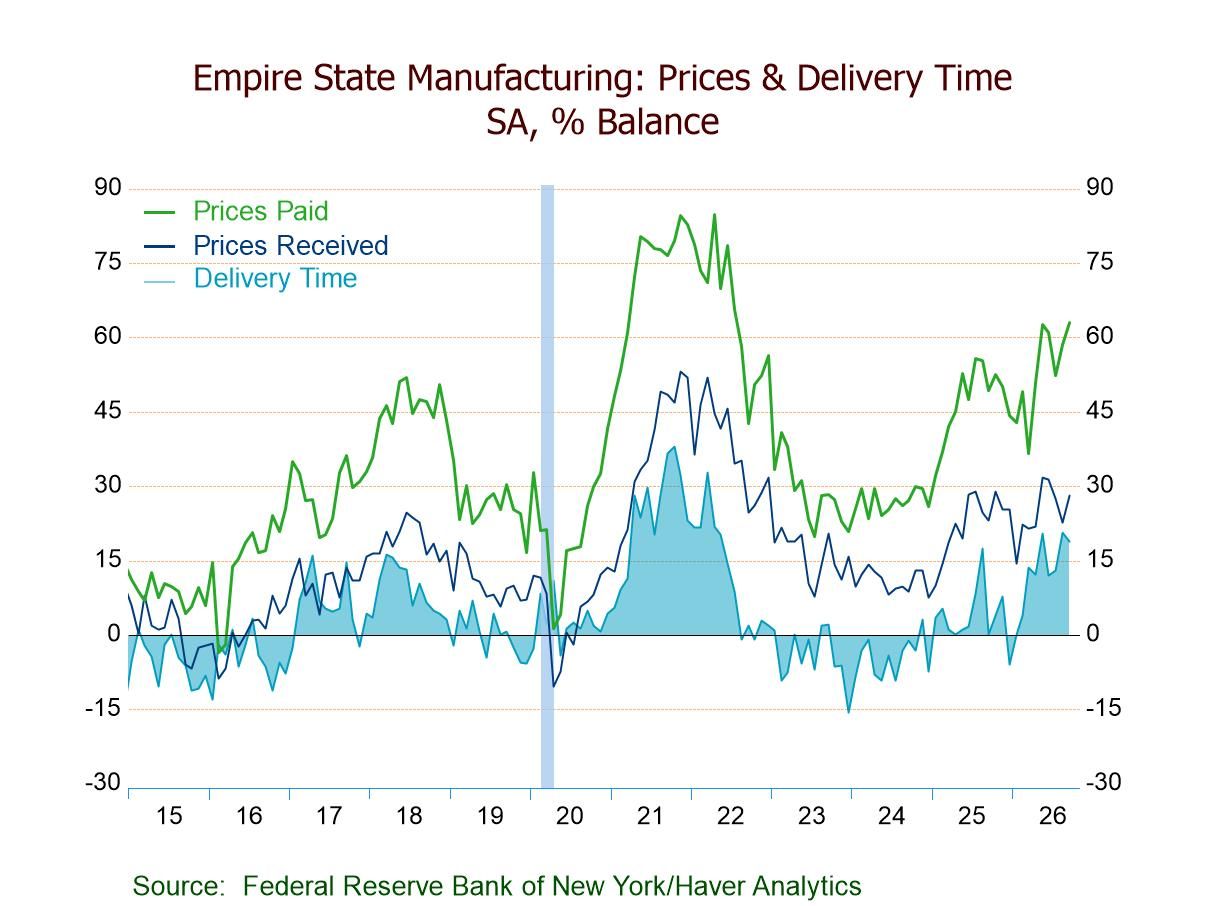
- Prices paid (63.1), highest since July '22; prices received (28.1), a three-month high.
- Firms still optimistic: Future Business Conditions Index down to a still-expansionary 29.0; future prices paid rising to 67.3, highest since June ’22.
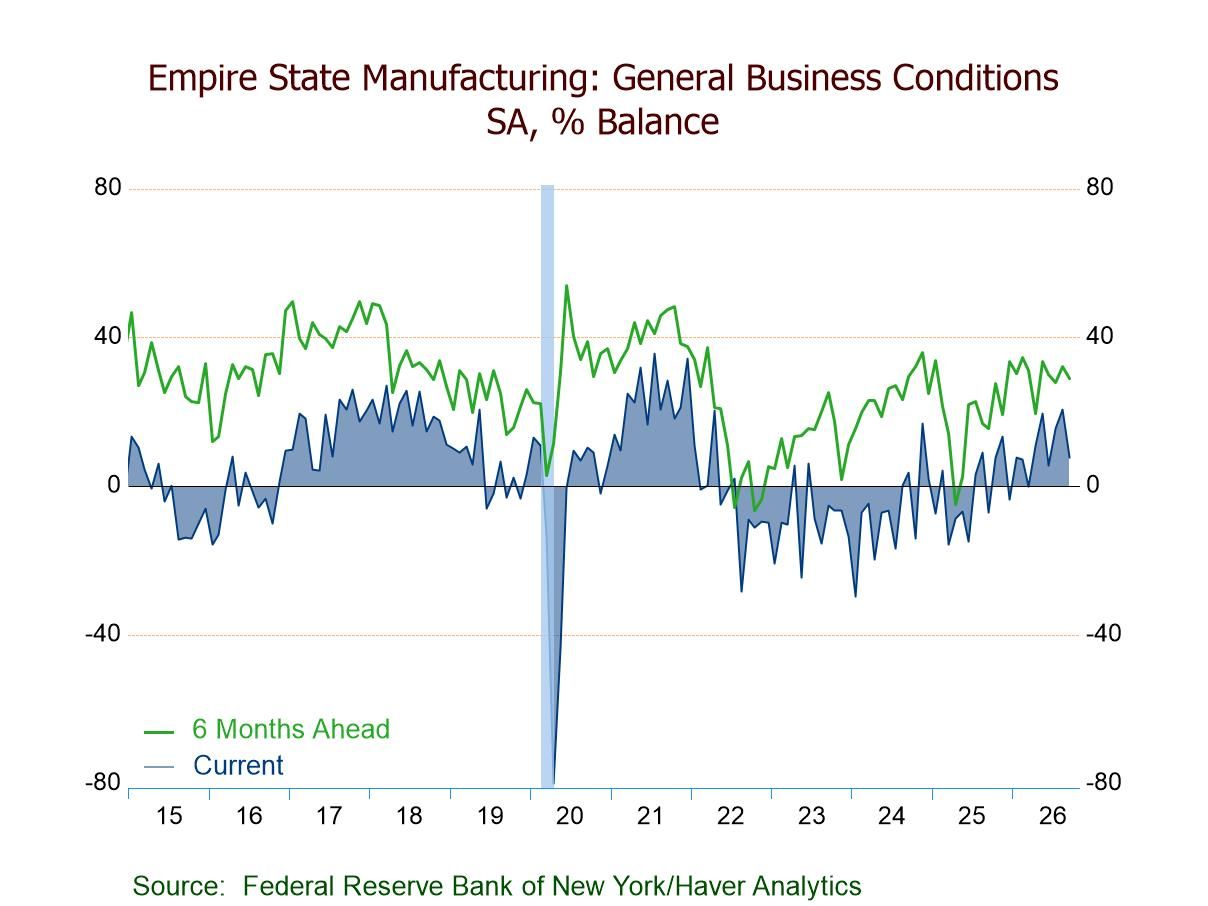
The Empire State Manufacturing Index of General Business Conditions fell sharply to a lower-than-expected 7.6 in September following a 5.0-point increase to 20.6 in August, according to the Empire State Manufacturing Survey released by the Federal Reserve Bank of New York. A reading of 14.1 for September had been expected in the Action Economics Forecast Survey. The positive September figure indicated that business activity in New York State expanded for the sixth straight month but at the slowest pace since June and well below August’s level (the highest since December 2021). Nevertheless, it was a sharp improvement from -7.0 in September 2025 and a low of -29.7 in January 2024. The percentage of respondents reporting an increase in general business conditions was 33.9% in September, down from 43.8% in August; the percentage reporting a decrease was 26.3%, up from August’s 23.1%. The latest survey was conducted between September 2 and September 10.
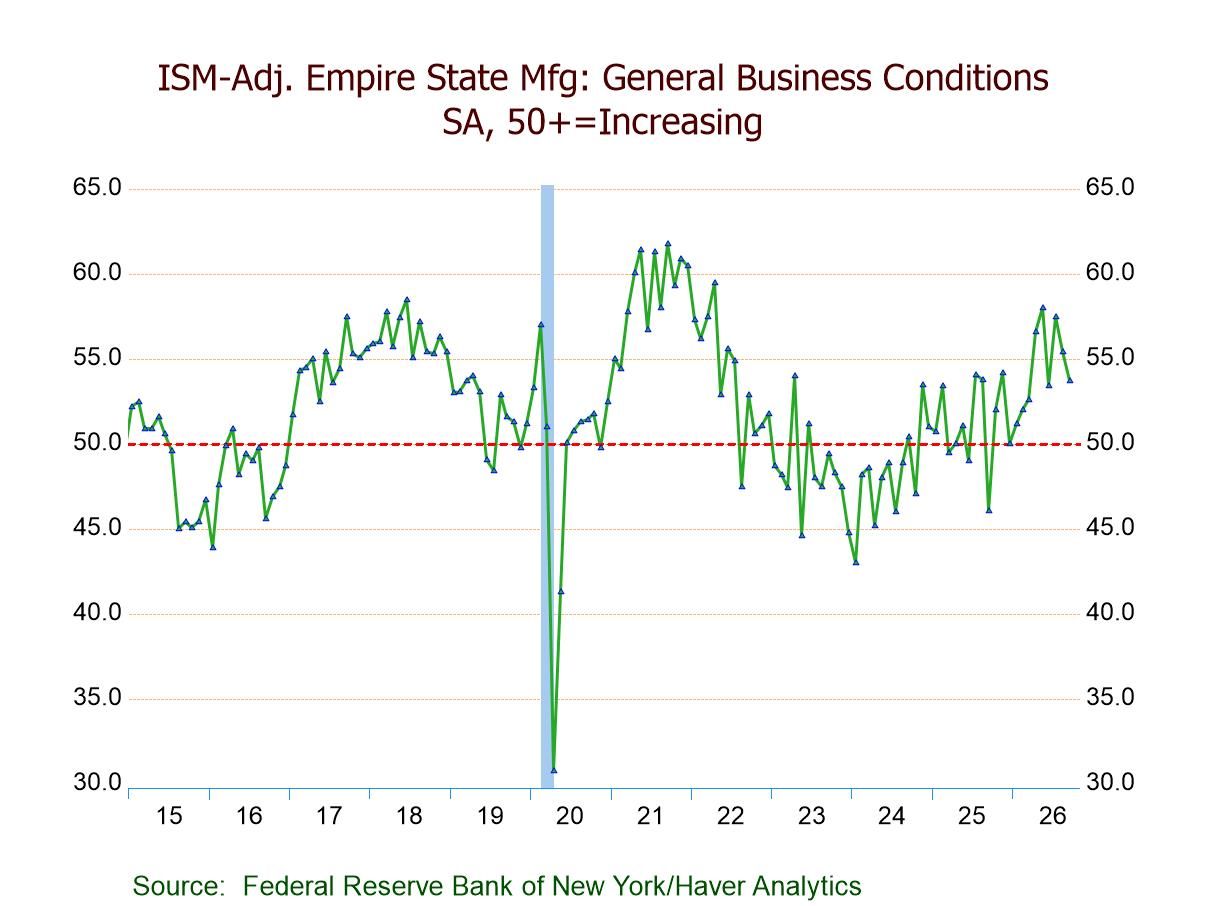
The headline index reflects the answer to a single question concerning the state of economic activity and is not calculated from the components. Haver Analytics calculates a composite index from the five major components, which is comparable to the ISM manufacturing index. This calculated index eased to 53.7 in September following a 2.1-point decline to 55.4 in August, representing the ninth consecutive expansion but at the slowest pace in three months; it was up from 46.1 in September 2025 and well above a low of 43.0 in January 2024. The index is the average of five diffusion indexes: new orders, shipments, employment, supplier deliveries and inventories, with equal weights (20% each).
In the latest survey, the new orders index fell to 2.0 in September after a 4.9-point decrease to 17.3 in August, marking the weakest of nine successive months of expansion; it was a sharp improvement from a low of -30.7 in January 2024 but a drop from a high of 19.6 in April 2023. The shipments index plunged to -3.2 in September following a 12.7-point fall to 11.7 in August, representing the first negative shipments reading since March; it was well above a low of -21.7 in April 2024 but below a high of 21.0 in June 2023. The unfilled orders index fell to 5.9 in September after a 10.5-point jump to 15.5 in August, indicating unfilled orders expanded for the eighth straight month but at a slower pace; the index reached a low of -24.2 in January 2024. The inventories index rebounded to 8.9 in September following a 9.2-point slide to -5.2 in August, signaling inventory growth at the strongest rate since May. Meanwhile, the delivery times index slipped to 18.8 in September from 20.6 in August (the highest reading since April 2022), with 25.7% of respondents reporting longer delivery times and 6.9% reporting shorter times, indicating that delivery times continued to lengthen.
On the labor front, the number of employees index rose to 10.6 in September after a 2.1-point decline to 9.3 in August, indicating employment expanded for the eighth straight month. The index remained well above a low of -9.3 in December 2023 but below a peak of 24.9 in February 2022. In September, 19.0% of respondents reported an increase in employment while 8.4% reported a decline. The average workweek index jumped to 17.0 in September from 6.9 in August, remaining positive for the eighth month running and at the strongest level since November 2021.
Inflation pressures remained elevated in September. The prices paid index advanced to 63.1 in September, the highest level since July 2022, after a 6.3-point rise to 58.6 in August. The index was above a low of 25.9 in December 2024 and a low of 19.9 in July 2023, albeit remaining well below a peak of 84.9 in April 2022. In September, 63.7% of respondents reported higher prices paid while only 0.6% reported lower prices paid. The prices received index increased to 28.1 in September, a three-month high, from 22.7 in August. The index was above a low of 7.5 in December 2024 and a low of 7.7 in July 2023 but far below a high of 51.9 in March 2022. In September, 30.6% of respondents reported higher prices received while 2.6% reported lower prices received.
Firms remained optimistic about the future business outlook in the latest survey. The index for future business conditions eased to 29.0 in September, the 17th straight month of positive readings, after a 4.2-point gain to 32.1 in August, with 50.5% of respondents expecting business conditions to improve over the next six months. Future new orders pulled back to 25.3 in September, the lowest level since April, from 37.1 in August; future shipments slid to 25.5, a five-month low, from 33.7. Growth in future employment decelerated to 20.0 in September from 28.2 in August (the strongest reading since March 2022). Capital spending plans remained positive for the 11th consecutive month in September, with the future capital expenditures index easing to 14.9, a three-month low, from August’s 16.5. Expected prices paid climbed to 67.3 in September, the highest level since June 2022, from 57.7 in August, while expected prices received declined to 42.3 from 48.7.
The indexes in this report are diffusion indexes and measure the percentage of respondents indicating an increase minus the percentage indicating a decrease with zero separating expansion from contraction.
The New York Fed survey data are contained in Haver’s SURVEYS database. The expectations series is in Haver’s AS1REPNA database.

Winnie Tapasanun
AuthorMore in Author Profile »Winnie Tapasanun has been working for Haver Analytics since 2013. She has 20+ years of working in the financial services industry. As Vice President and Economic Analyst at Globicus International, Inc., a New York-based company specializing in macroeconomics and financial markets, Winnie oversaw the company’s business operations, managed financial and economic data, and wrote daily reports on macroeconomics and financial markets. Prior to working at Globicus, she was Investment Promotion Officer at the New York Office of the Thailand Board of Investment (BOI) where she wrote monthly reports on the U.S. economic outlook, wrote reports on the outlook of key U.S. industries, and assisted investors on doing business and investment in Thailand. Prior to joining the BOI, she was Adjunct Professor teaching International Political Economy/International Relations at the City College of New York. Prior to her teaching experience at the CCNY, Winnie successfully completed internships at the United Nations. Winnie holds an MA Degree from Long Island University, New York. She also did graduate studies at Columbia University in the City of New York and doctoral requirements at the Graduate Center of the City University of New York. Her areas of specialization are international political economy, macroeconomics, financial markets, political economy, international relations, and business development/business strategy. Her regional specialization includes, but not limited to, Southeast Asia and East Asia. Winnie is bilingual in English and Thai with competency in French. She loves to travel (~30 countries) to better understand each country’s unique economy, fascinating culture and people as well as the global economy as a whole.
More Economy in Brief
 Global