U.S. Retail Sales Rise in September, Above Forecasts
Summary
- Total retail sales +0.8% (+6.3% y/y) in Sept.; seventh m/m increase in eight mths.
- Ex-auto sales +0.9% (+7.2% y/y), second straight m/m rise; auto sales +0.2% (+2.5% y/y), fourth gain in five mths.
- Ex-gas sales +0.2% (+4.5% y/y) and ex-auto & gas sales +0.2% (+5.0% y/y); both up m/m from Feb. through Sept. except July.
- Retail control group +0.1% (+4.7% y/y), seventh m/m rise in eight mths., capping a firm Q3 ’26 for underlying consumer demand.
- Gains m/m: gasoline stations (+6.4%), department stores (+1.6%), furniture stores (+1.3%), food svcs. (+1.1%).
- Declines m/m: misc. stores (-3.0%), building materials & garden equipt. (-0.6%), sporting goods (-0.5%), general merch. (-0.1%).
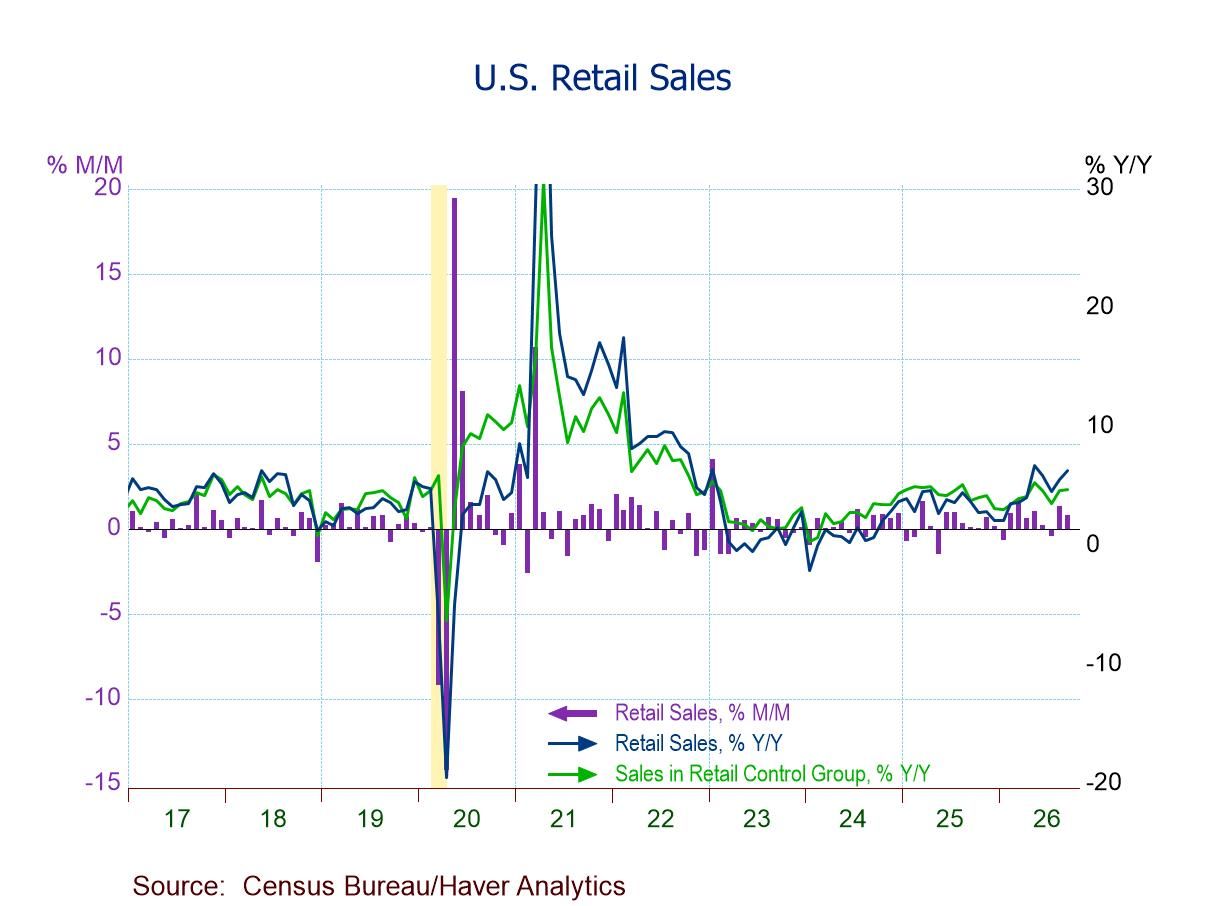
Total retail sales rose a larger-than-expected 0.8% m/m to $745.02 billion in September, the seventh m/m rise in eight months, following a 1.3% gain in August (+1.1% previously reported on Sept. 28 and +1.2% on Sept. 16) and a 0.4% decline in July (-0.5% previously), data from the U.S. Census Bureau showed, suggesting resilient consumer spending and continued domestic demand in Q3 2026. A 0.3% m/m September increase had been expected in the Action Economics Forecast Survey. The year-on-year growth rate accelerated to 6.3% in September, the highest since May, from 5.6% in August (3.7% in September 2025), while remaining well below a high of 17.5% in February 2022 and a record high of 51.5% in April 2021. On a quarterly basis, retail sales rose 1.2% q/q in Q3 ’26 (5.5% y/y), slowing from 2.8% q/q in Q2 ’26 (5.6% y/y), suggesting a cooler pace of nominal consumer spending growth in Q3 ’26. (Note: On September 28, the Census Bureau released annual Retail Trade revisions – no new observations were reported; revised data reflected the introduction of new seasonal factors and the results of the 2023 and 2024 Annual Integrated Economic Survey; data were revised back to 1992.)
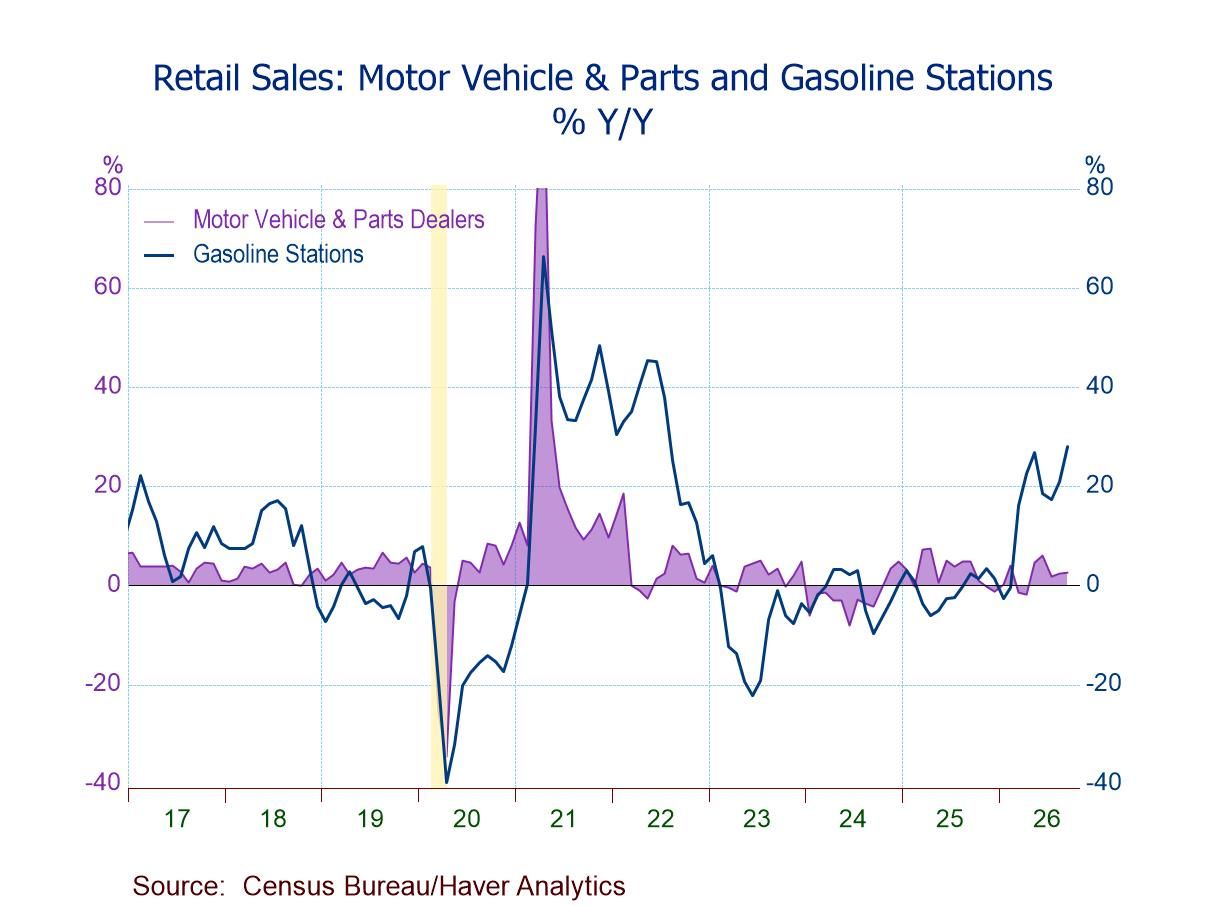
Excluding motor vehicles & parts, retail sales grew a greater-than-expected 0.9% (7.2% y/y) in September after a 1.4% gain in August (+1.3% previously reported on Sept. 28 and +1.4% on Sept. 16). A 0.5% m/m September rise had been expected. Sales of motor vehicles & parts edged up 0.2% (2.5% y/y), the fourth m/m increase in five months, after a 0.7% August rebound; this compared to a 3.8% drop (-3.5% y/y) in unit light vehicle sales following a 2.2% August gain.
Sales in the retail control group, which excludes autos, building materials, gasoline stations, and food services, ticked up 0.1% (4.7% y/y) in September, the seventh m/m rise in eight months, following a 1.2% rebound in August, capping a firm Q3 2026 for underlying consumer demand. These sales are used in the construction of personal consumption expenditures in NIPA accounts. Nonauto sales excluding gasoline & building materials rose 0.3% (5.1% y/y), up for the seventh time in eight months, after a 1.2% August increase.
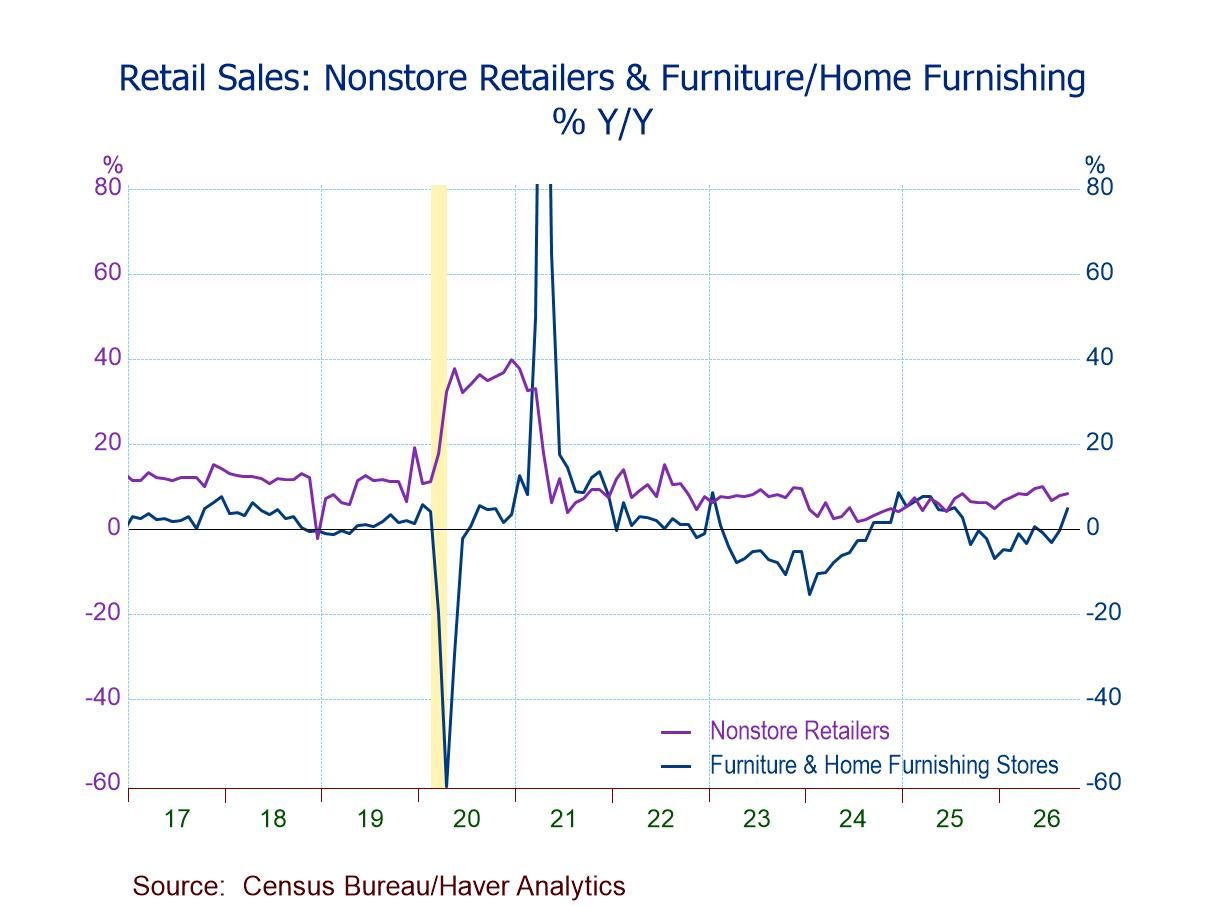
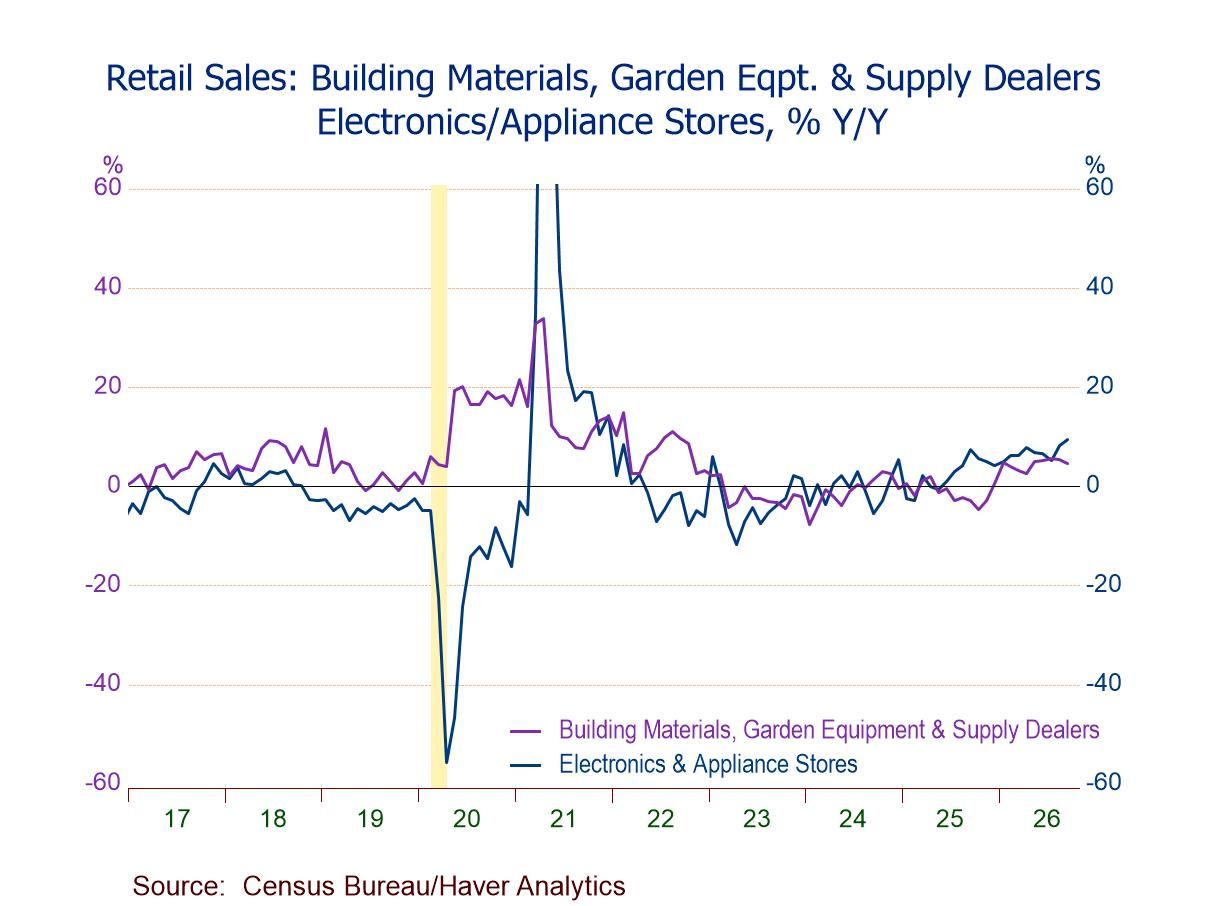
Sales by category were mixed in September. Posting the biggest m/m gain among major categories, gasoline station sales surged 6.4% (28.1% y/y) in September, the largest since March, after a 4.0% recovery in August, as the September CPI showed gasoline prices up 9.1% (34.2% y/y); gasoline stations accounted for 71.4% of the $5.7 billion increase in total retail sales. Furniture & home furnishing store sales advanced 1.3% (4.9% y/y) following a 0.2% August increase. Electronics & appliance store sales climbed 0.6% (9.4% y/y), the fourth straight m/m gain and the 11th in 12 months, on top of a 2.1% August rise. Nonstore retail sales grew 0.3% (8.2% y/y), up for the 11th time in 12 months, following a 2.0% August increase. In contrast, miscellaneous store sales dropped 3.0% (+10.9% y/y), the first m/m decline since April and the steepest since August 2025, after a 3.6% August jump. Building materials & garden equipment store sales fell 0.6% (+4.5% y/y) after a 0.2% August increase, and sporting goods, hobby, book & music store sales slid 0.5% (+9.6% y/y) after a 1.0% August rise; both decreased for the second time in three months. General merchandise store sales slipped 0.1% (+4.2% y/y) in September, the first m/m easing since April, after a 0.8% gain in August; within this category, department store sales recovered 1.6% (6.4% y/y), the largest m/m gain since March, following a 0.6% August decline. Meanwhile, clothing & accessory store sales were virtually unchanged m/m (+5.0% y/y) after rises of 0.6% in August and 1.3% in July.
In the nondiscretionary sales categories, health & personal care store sales rose 0.7% (-1.2% y/y) in September, the fourth m/m rise in five months, after a 1.2% increase in August. Food & beverage store sales climbed 0.4% (0.9% y/y) after a 0.2% August gain and declines of 0.2% in July and June.
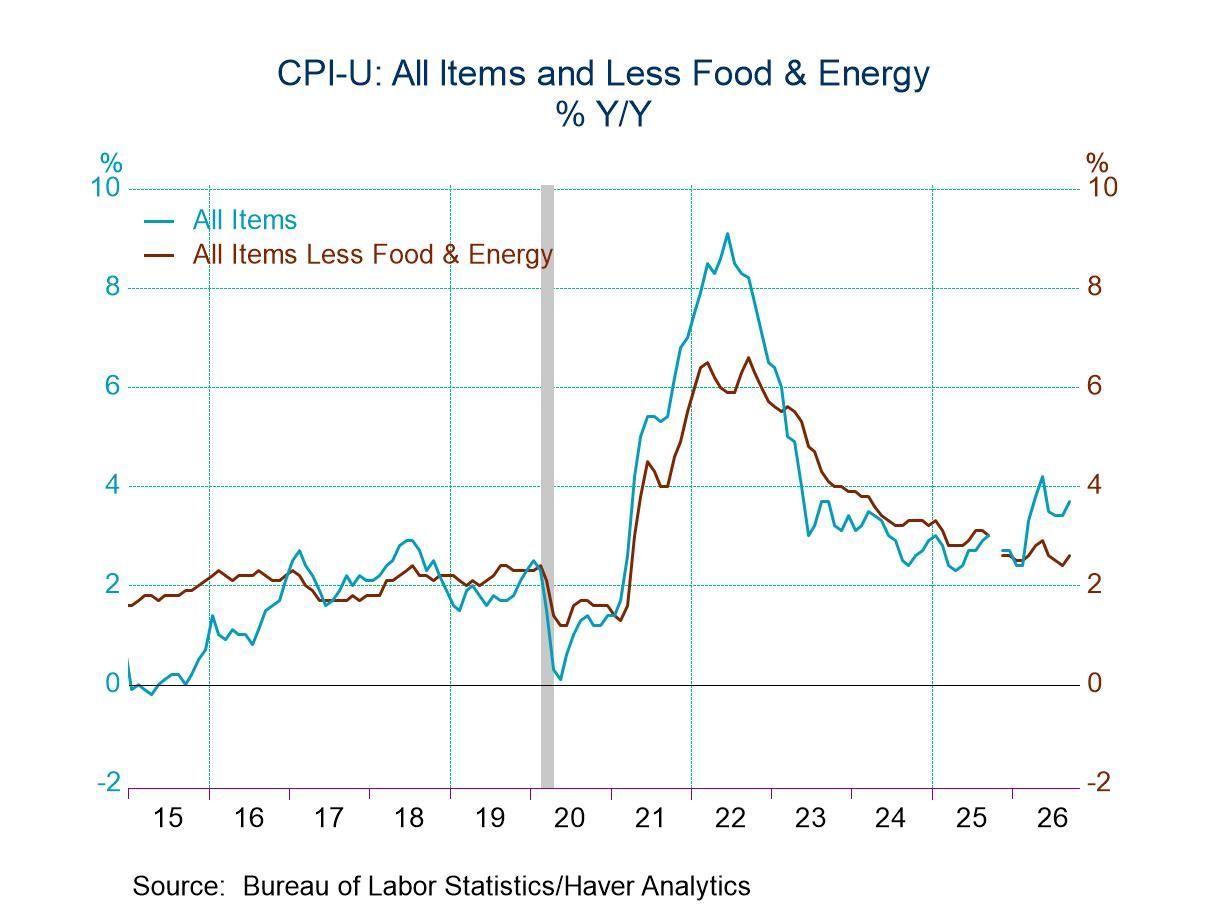
Consumers appeared to dine out more frequently in September despite still-elevated inflation (September CPI +0.6% m/m, +3.7% y/y; core CPI +0.3% m/m, +2.6% y/y). Restaurant & drinking place sales gained 1.1% (7.0% y/y) in September, the eighth straight m/m rise, after an upwardly revised 1.4% increase in August.
Retail Sales data can be found in Haver's USECON database. The expectations figures are from the Action Economics Forecast Survey in AS1REPNA.

Winnie Tapasanun
AuthorMore in Author Profile »Winnie Tapasanun has been working for Haver Analytics since 2013. She has 20+ years of working in the financial services industry. As Vice President and Economic Analyst at Globicus International, Inc., a New York-based company specializing in macroeconomics and financial markets, Winnie oversaw the company’s business operations, managed financial and economic data, and wrote daily reports on macroeconomics and financial markets. Prior to working at Globicus, she was Investment Promotion Officer at the New York Office of the Thailand Board of Investment (BOI) where she wrote monthly reports on the U.S. economic outlook, wrote reports on the outlook of key U.S. industries, and assisted investors on doing business and investment in Thailand. Prior to joining the BOI, she was Adjunct Professor teaching International Political Economy/International Relations at the City College of New York. Prior to her teaching experience at the CCNY, Winnie successfully completed internships at the United Nations. Winnie holds an MA Degree from Long Island University, New York. She also did graduate studies at Columbia University in the City of New York and doctoral requirements at the Graduate Center of the City University of New York. Her areas of specialization are international political economy, macroeconomics, financial markets, political economy, international relations, and business development/business strategy. Her regional specialization includes, but not limited to, Southeast Asia and East Asia. Winnie is bilingual in English and Thai with competency in French. She loves to travel (~30 countries) to better understand each country’s unique economy, fascinating culture and people as well as the global economy as a whole.
More Economy in Brief
 Global