U.S. Productivity Jumped in Q3 2026
by:Sandy Batten
|in:Economy in Brief
Summary
- Output per hour jumped a larger-than-expected and well above trend 3.6% q/q saar in Q3 with an upward revision to Q2.
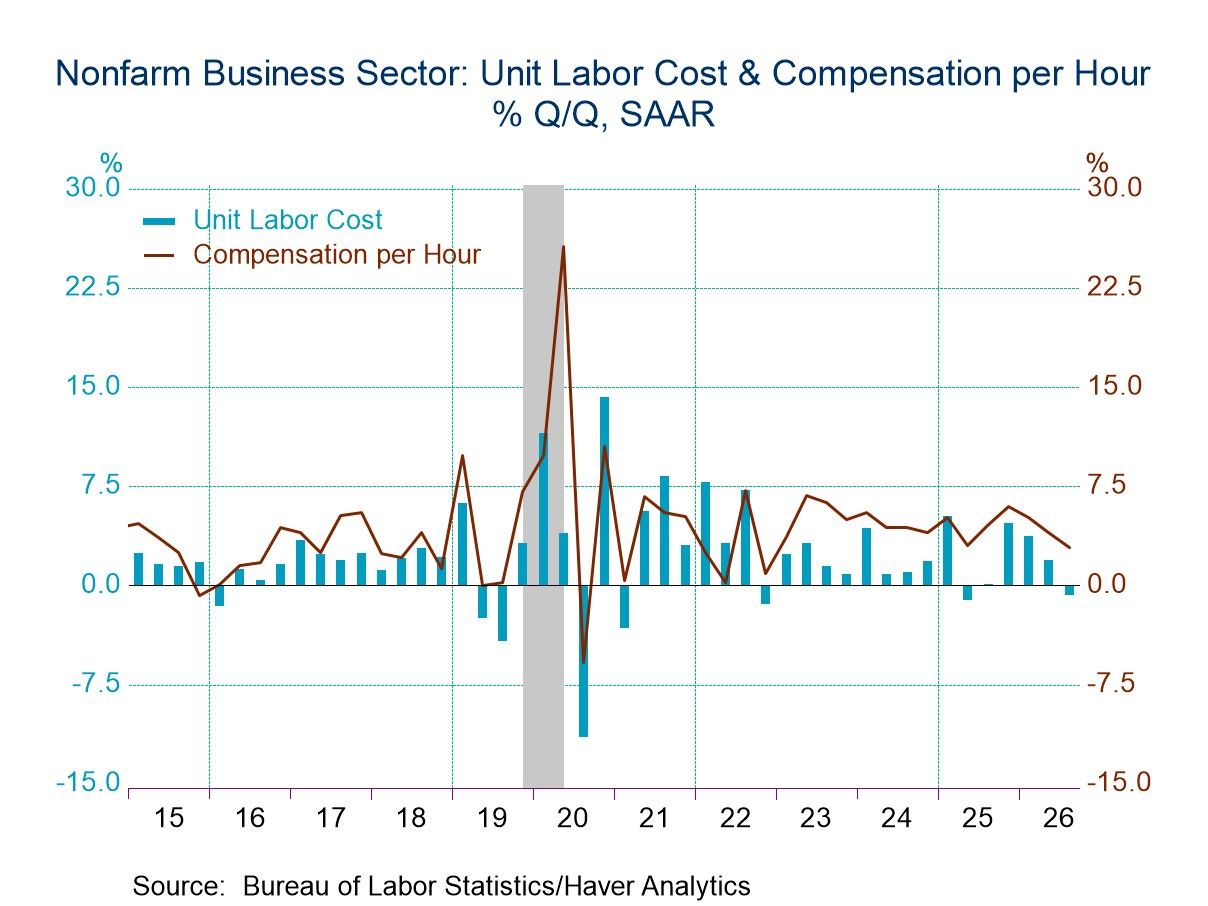
- Compensation growth slowed to 2.9% q/q resulting in a 0.7% quarterly decline in unit labor costs.
- Benchmark revisions back to the beginning of 2021 were modest but generally positive, pushing up productivity growth from Q4 2020 to 1.62% from 1.50%.
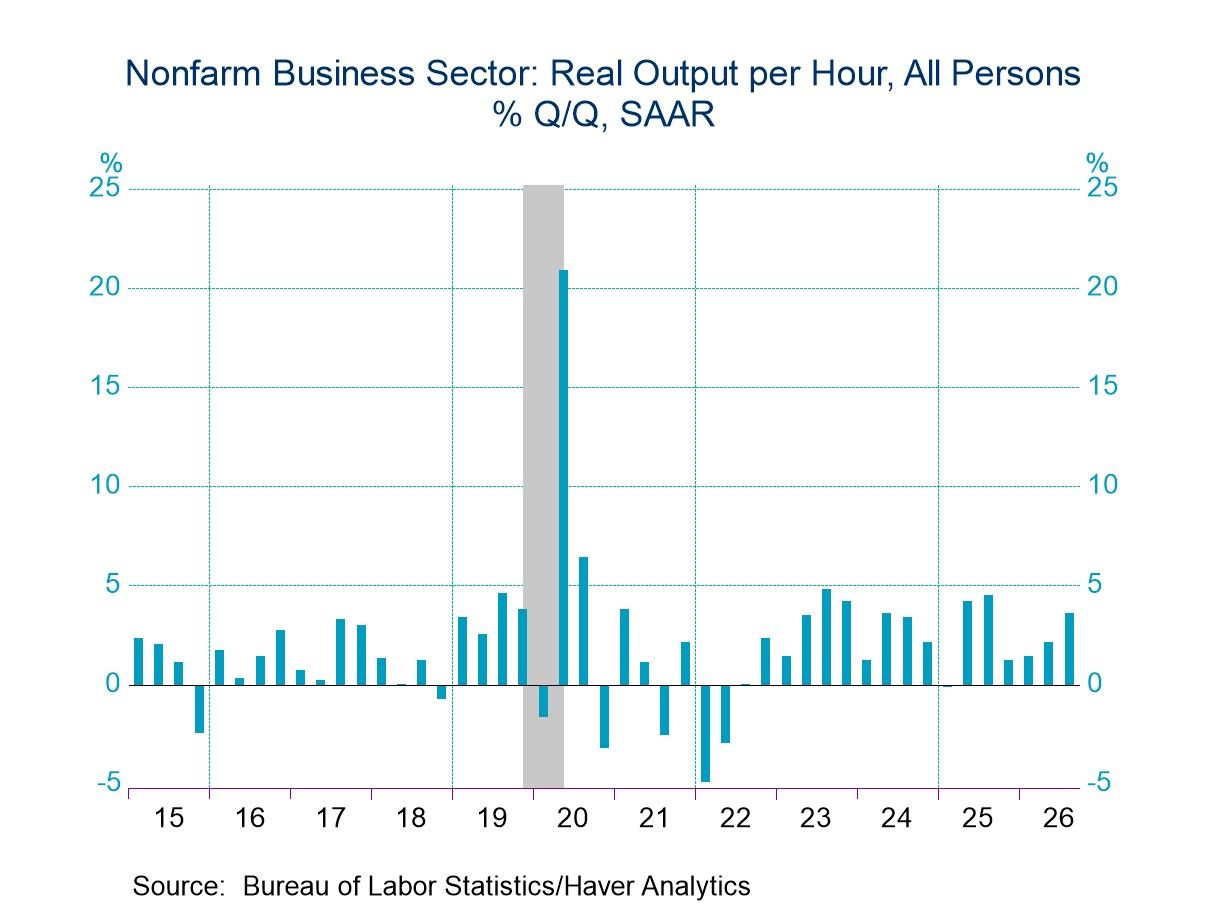
Nonfarm business productivity (output per hour) jumped 3.6% q/q saar in Q3 following an upwardly revised 2.1% quarterly gain in Q2 (previously 1.4%). The Action Economics Forecast Survey expected a 2.7% quarterly increase in productivity. Compared with a year, productivity was up 2.1%, slightly slower than 2.3% y/y in Q2. Since productivity growth began to accelerate at the beginning of 2023, it has grown at a well above trend 2.7% annual rate, likely a reflection of AI and other technology advances. Strong productivity is a key factor for boosting real incomes and restraining inflation pressures.
Nonfarm business output (a little different from real GDP) increased 3.7% q/q saar in Q3 versus an upwardly revised 2.4% in Q2 (previously 1.7%). By contrast, real GDP grew 3.4% q/q in Q3. Hours worked edged up 0.1% q/q in Q3 following an unrevised 0.3% quarterly increase in Q2. Compensation growth slowed to 2.9% in Q3 from an upwardly revised 4.0% increase in Q2 (previously 2.6%). Compared to a year ago, compensation growth slowed to 4.5% y/y from 4.9%. With quarterly productivity growth exceeding compensation growth in Q3, unit labor costs fell 0.7% q/q in Q3 after an upwardly revised 1.9% quarterly gain in Q2 (previously +1.2%). The Action Economics Forecast Survey looked for a 1.1% q/q increase in unit labor costs in Q3. The y/y rate of advance for unit labor costs slowed, to 2.4% y/y in Q3 from 2.6% in Q2.
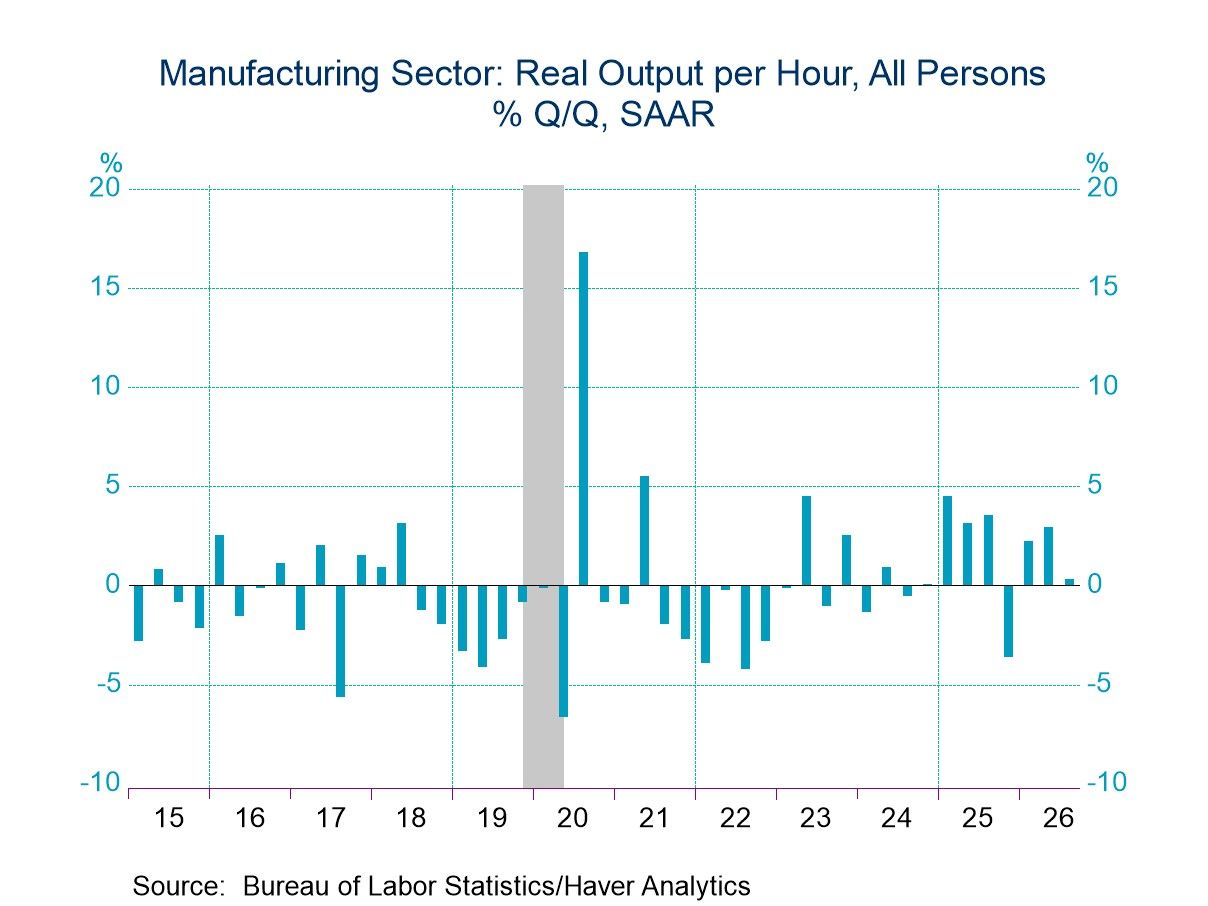
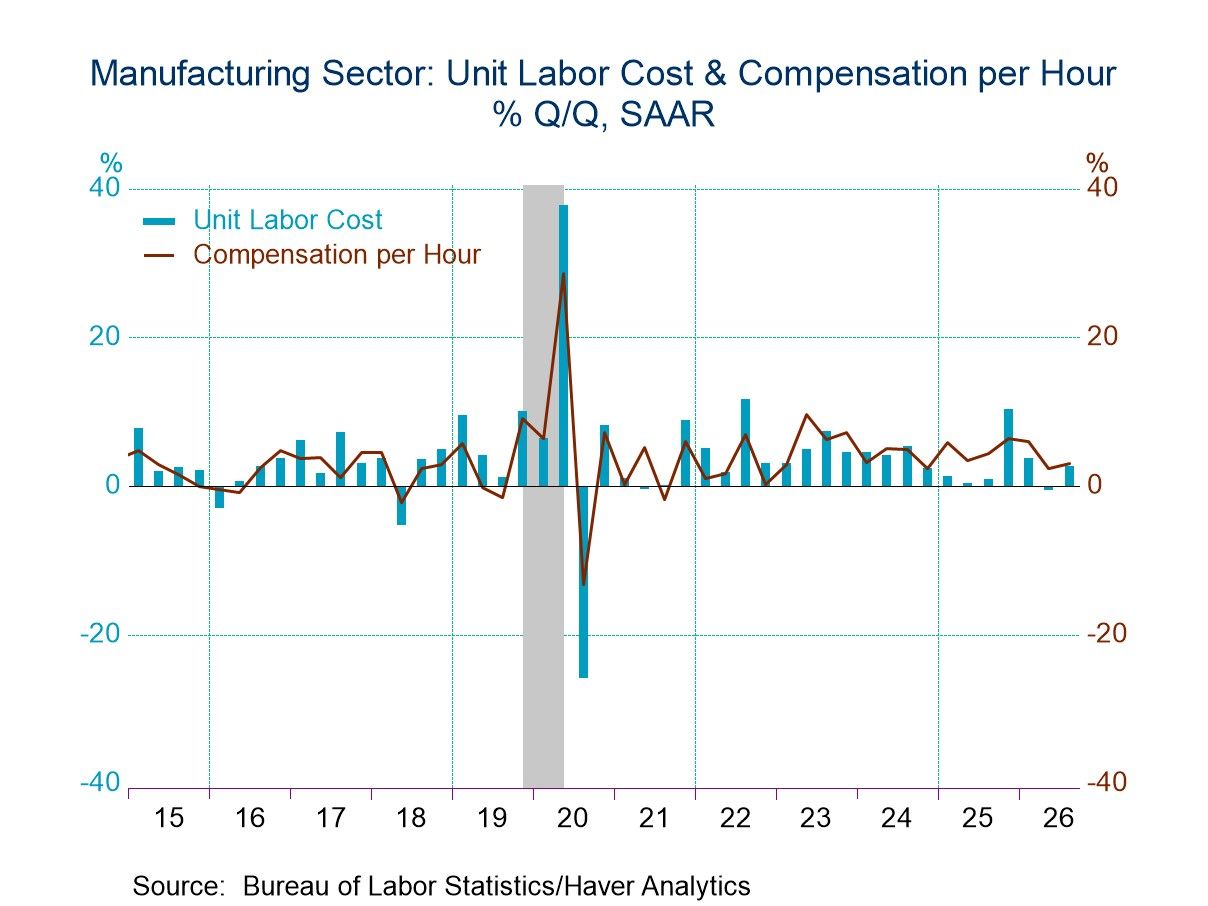
Manufacturing productivity growth slowed markedly in Q3, to 0.3% q/q saar from an upwardly revised 2.9% quarterly gain in Q2 (previously 2.4%). Factory output rose only 1.3% q/q in Q3 following an upwardly revised 5.8% q/q jump in Q2 (previously +5.4%). Hours worked increased 1.0% q/q, down from 2.9% (unrevised) in Q2. Compensation growth picked up to 3.0% from an upwardly revised 2.4% in Q2 (previously 2.1%). With the slowdown in productivity growth and the pickup in compensation growth, unit labor costs jumped 2.7% q/q in Q3 after a 0.4% quarterly decline in Q2 (previously -0.3%). Compared with a year ago, manufacturing unit labor costs were up 4.0% y/y, the highest yearly rate of advance since Q4 2024.
Today’s release also contained benchmark revisions from the beginning of 2021. They were modest but generally positive. Over the 22 quarters of revision, productivity grew at a revised 1.62% annual rate, compared to 1.50% prior to the revisions.
The productivity and labor cost data are available in Haver’s USECON database. The Action Economics expectations figures are in the AS1REPNA database.
Sandy Batten
AuthorMore in Author Profile »Sandy Batten has more than 30 years of experience analyzing industrial economies and financial markets and a wide range of experience across the financial services sector, government, and academia. Before joining Haver Analytics, Sandy was a Vice President and Senior Economist at Citibank; Senior Credit Market Analyst at CDC Investment Management, Managing Director at Bear Stearns, and Executive Director at JPMorgan. In 2008, Sandy was named the most accurate US forecaster by the National Association for Business Economics. He is a member of the New York Forecasters Club, NABE, and the American Economic Association. Prior to his time in the financial services sector, Sandy was a Research Officer at the Federal Reserve Bank of St. Louis, Senior Staff Economist on the President’s Council of Economic Advisors, Deputy Assistant Secretary for Economic Policy at the US Treasury, and Economist at the International Monetary Fund. Sandy has taught economics at St. Louis University, Denison University, and Muskingun College. He has published numerous peer-reviewed articles in a wide range of academic publications. He has a B.A. in economics from the University of Richmond and a M.A. and Ph.D. in economics from The Ohio State University.
More Economy in Brief
 Global