U.S. Industrial Production Tops Forecasts in September; Manufacturing IP Rebounds
Summary
- September IP +0.7% (+2.2% y/y), sixth consecutive m/m increase; on an upward trend.
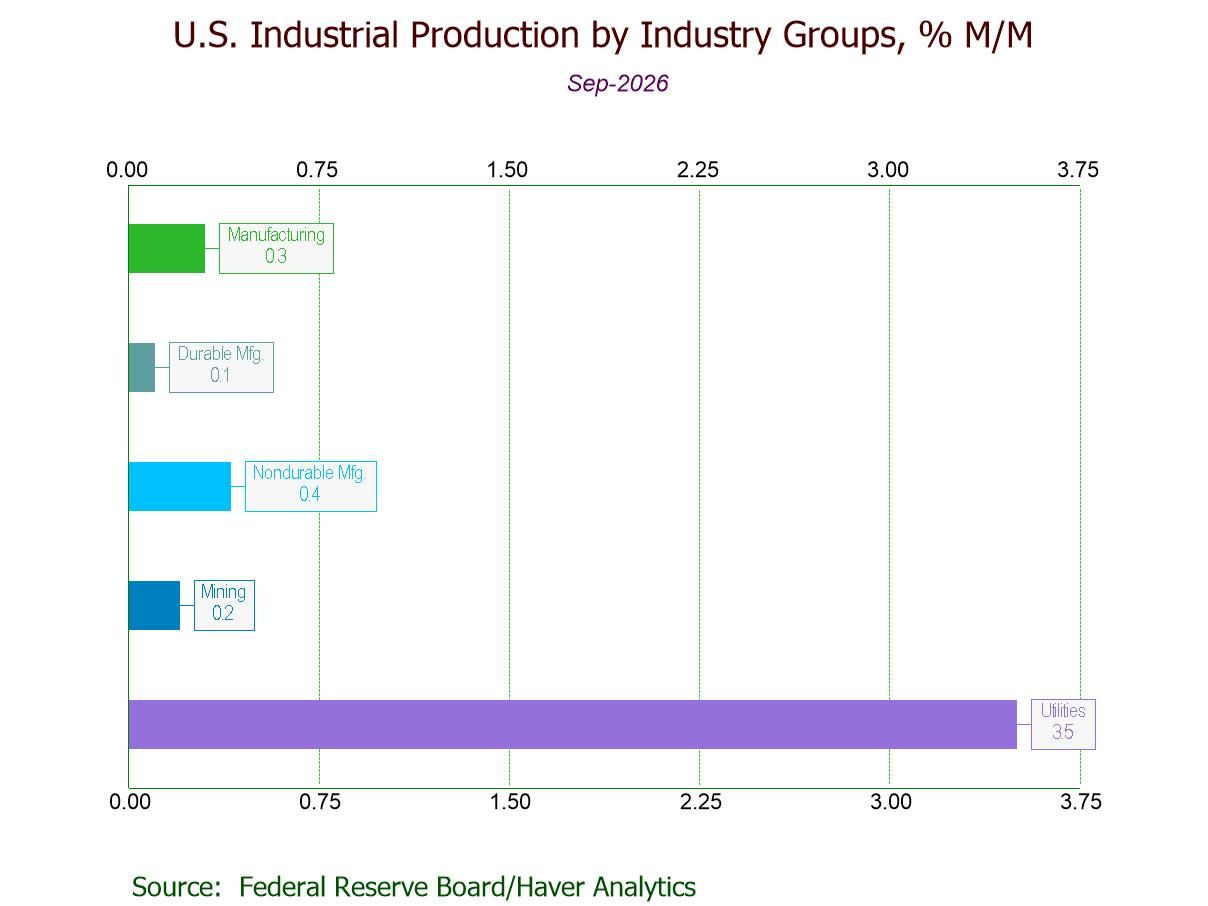
- Manufacturing +0.3% (+1.1% y/y), seventh rise in eight mths., w/ durables +0.1% and nondurables +0.4%.
- Selected high-tech +1.5%, sixth straight m/m gain; motor vehicles -3.0%, third successive m/m drop.
- Utilities +3.5% (+8.7% y/y), fifth rise in six mths., led by a 3.7% jump in electric utilities output.
- Mining +0.2% (+2.8% y/y), up for the sixth month running.
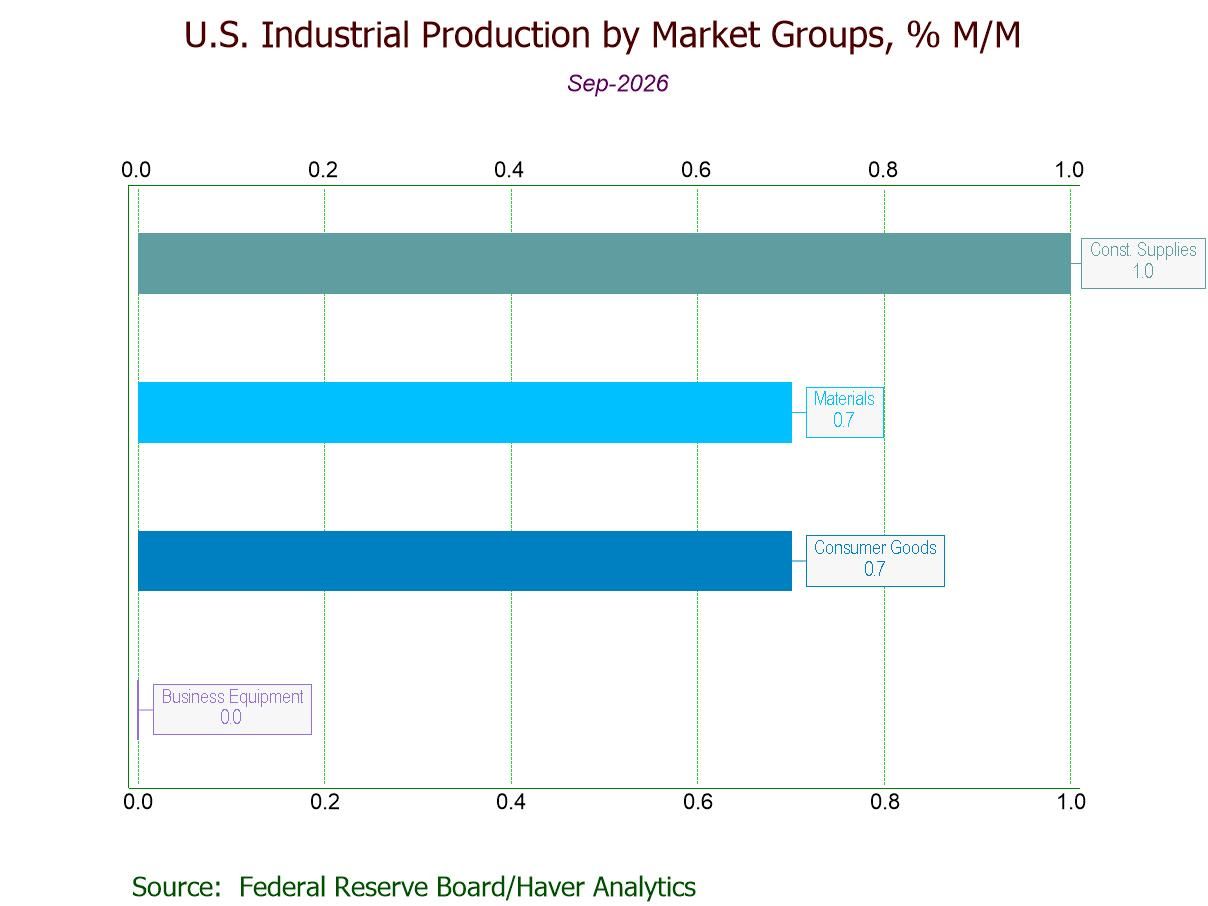
- All key categories in market groups gain m/m except business equipt. (0.0%).
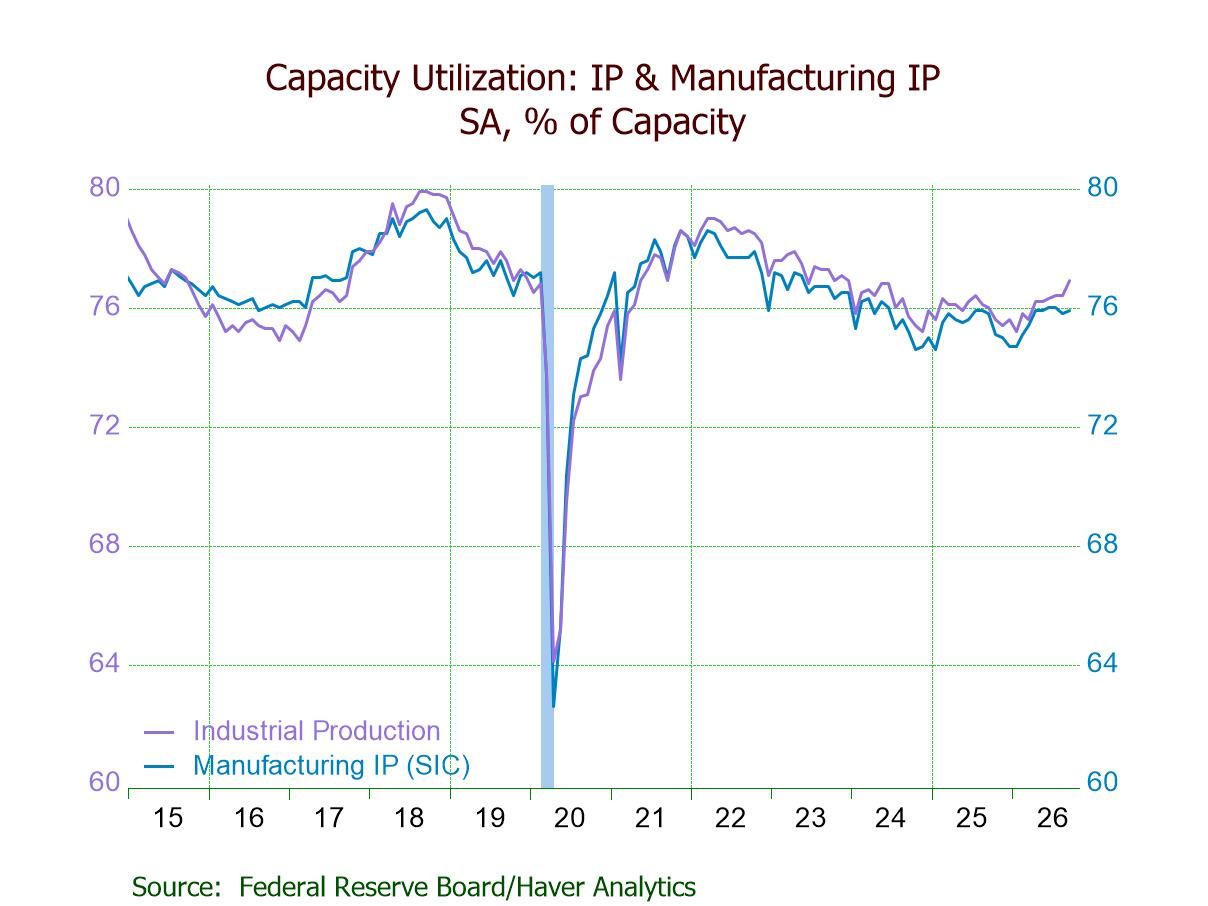
- Capacity utilization up to 76.9%, highest since Dec. ’23; mfg. capacity utilization up to 75.9%.
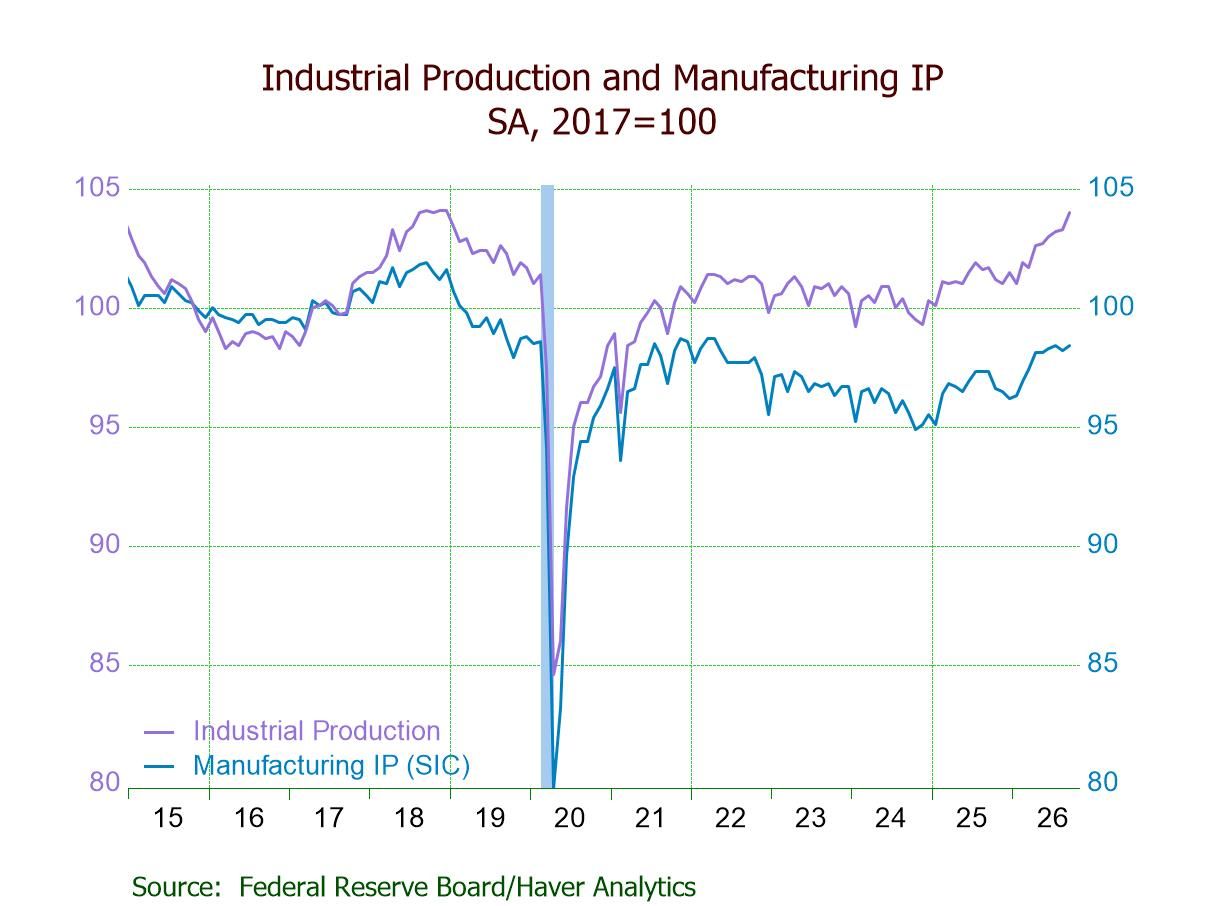
Industrial production (IP) rose a more-than-expected 0.7% m/m in September after increases of 0.1% in August (0.0% initially) and 0.2% in July (unrevised), data from the Federal Reserve Board showed, indicating industrial activity remained on an upward trend. A 0.4% m/m September increase had been expected in the Action Economics Forecast Survey. The latest reading marked the sixth straight m/m rise and the seventh in eight months. The year-on-year growth rate accelerated to 2.2% in September, the highest since January, from 1.4% in August (1.6% in September 2025). The September IP index at 104.0 was 4.7% above a low of 99.3 in November 2024 and 4.8% above a low of 99.2 in January 2024. On a quarterly basis, IP rose 0.7% q/q in Q3 ’26 (1.7% y/y), the sixth quarterly rise in seven quarters, after a 1.2% gain in Q2 ’26 (1.5% y/y), with the annualized growth rate moderating to 2.8% in Q3 from 4.8% in Q2.
By industry groups, manufacturing production grew 0.3% (1.1% y/y) in September, the seventh m/m increase in eight months, after a 0.2% decline in August (-0.3% initially) and a 0.1% uptick in July (+0.2% previously). Durable goods production edged up 0.1% (3.7% y/y) in September, the eighth m/m gain in nine months, following a 0.5% slide in August. Within durables, most categories rose m/m in September, led by a 1.6% rebound (1.3% y/y) in primary metals, followed by rises of 1.4% (6.9% y/y) in machinery, 1.3% (5.4% y/y) in electrical equipment, appliances & components, 0.9% (2.2% y/y) in nonmetallic mineral products, 0.6% (3.3% y/y) in fabricated metal products, 0.5% (4.4% y/y) in aerospace & miscellaneous transportation equipment, 0.1% (9.5% y/y) in computer & electronic products, and 0.1% (2.1% y/y) in miscellaneous durable goods. To the downside, durable goods categories for motor vehicles & parts (-3.0%; -0.8% y/y), furniture & related products (-1.2%; -4.1% y/y), and wood products (-0.1%; +1.5% y/y) posted m/m output decreases in September. Notably, aircraft & parts production fell 0.5% (+5.9% y/y) after a 1.3% August decline and six consecutive m/m increases.
Nondurable goods production rose 0.4% (-1.1% y/y) in September following no change in August and a 0.4% decline in July. The September output rise was led by a 1.9% recovery (-2.2% y/y) in printing & related support activities, followed by gains of 1.0% (-1.3% y/y) in chemicals, 0.7% (0.9% y/y) in petroleum & coal products, 0.4% (-1.5% y/y) in food, beverages & tobacco, and 0.1% (4.3% y/y) in apparel & leather goods. In contrast, nondurable goods categories for paper (-1.1%; -3.2% y/y), plastics & rubber products (-0.9%; +0.7% y/y), and textiles & product mills (-0.6%; 0.0% y/y) registered m/m output declines in September.
Utilities output advanced 3.5% (8.7% y/y) in September, the fifth m/m rise in six months, after a downwardly revised 1.5% increase in August (+1.8% initially), reflecting a 3.7% jump (9.6% y/y) in electric utilities output and a 2.1% rebound (3.1% y/y) in natural gas utilities output. Mining activity moved up 0.2% (2.8% y/y), the sixth straight m/m gain and the seventh in eight months, on top of an upwardly revised 0.5% August rise (+0.1% initially).
By market groups, construction supplies production rebounded 1.0% (1.6% y/y) in September, the fourth m/m rise in five months, following a 0.7% decrease in August. Materials production climbed 0.7% (2.6% y/y), the sixth successive m/m increase and the seventh in eight months, after a 0.3% August rise. Consumer goods output rose 0.7% (-0.1% y/y) after no change in August and July, reflecting a 1.5% decline (-2.8% y/y) in durable consumer goods and a 1.2% gain (0.7% y/y) in nondurable consumer goods. Meanwhile, business equipment output was virtually unchanged m/m (+6.7% y/y) after a 0.1% August easing and eight straight m/m increases.
In special classifications, factory output of selected high-tech industries advanced 1.5% (17.5% y/y) in September, the sixth consecutive m/m rise and the 11th in 12 months, adding to a 1.1% gain in August. Manufacturing production excluding selected high-tech industries rose 0.2% (0.7% y/y) following a 0.3% decline in August and no change in July. Manufacturing production excluding selected high-tech and motor vehicles & parts grew 0.5% (0.8% y/y), the third m/m increase in four months, reversing a 0.3% August decrease.
Capacity utilization rose to 76.9% in September, the highest since December 2023, from 76.4% in August (76.3% initially) and 76.4% in July (76.3% previously). The Action Economics Forecast Survey forecasted 76.5%. The September reading was 2.5 percentage points below its long-run (1972–2025) average. Manufacturing capacity utilization inched up to 75.9% in September from 75.8% in August (75.7% initially). The September rate was 2.3 percentage points below its long-run average.
Industrial production and capacity data are in Haver’s USECON database. Additional detail on production and capacity utilization can be found in the IP database. The expectations figures come from the AS1REPNA database.

Winnie Tapasanun
AuthorMore in Author Profile »Winnie Tapasanun has been working for Haver Analytics since 2013. She has 20+ years of working in the financial services industry. As Vice President and Economic Analyst at Globicus International, Inc., a New York-based company specializing in macroeconomics and financial markets, Winnie oversaw the company’s business operations, managed financial and economic data, and wrote daily reports on macroeconomics and financial markets. Prior to working at Globicus, she was Investment Promotion Officer at the New York Office of the Thailand Board of Investment (BOI) where she wrote monthly reports on the U.S. economic outlook, wrote reports on the outlook of key U.S. industries, and assisted investors on doing business and investment in Thailand. Prior to joining the BOI, she was Adjunct Professor teaching International Political Economy/International Relations at the City College of New York. Prior to her teaching experience at the CCNY, Winnie successfully completed internships at the United Nations. Winnie holds an MA Degree from Long Island University, New York. She also did graduate studies at Columbia University in the City of New York and doctoral requirements at the Graduate Center of the City University of New York. Her areas of specialization are international political economy, macroeconomics, financial markets, political economy, international relations, and business development/business strategy. Her regional specialization includes, but not limited to, Southeast Asia and East Asia. Winnie is bilingual in English and Thai with competency in French. She loves to travel (~30 countries) to better understand each country’s unique economy, fascinating culture and people as well as the global economy as a whole.
More Economy in Brief
 Global