U.S. Housing Market Index Drops in October to Lowest Level Since June 2012
Summary
- HMI weakens m/m for the fourth time in five mths. in Oct., indicating most builders remain pessimistic about the current and near-term housing outlook.
- All three HMI components down, w/ the steepest m/m drop in prospective buyer traffic (-21.7%).
- Mixed regional performance m/m: down in the West (-33.3%), Midwest (-12.5%) and South (-6.9%); up in the Northeast (+5.7%).
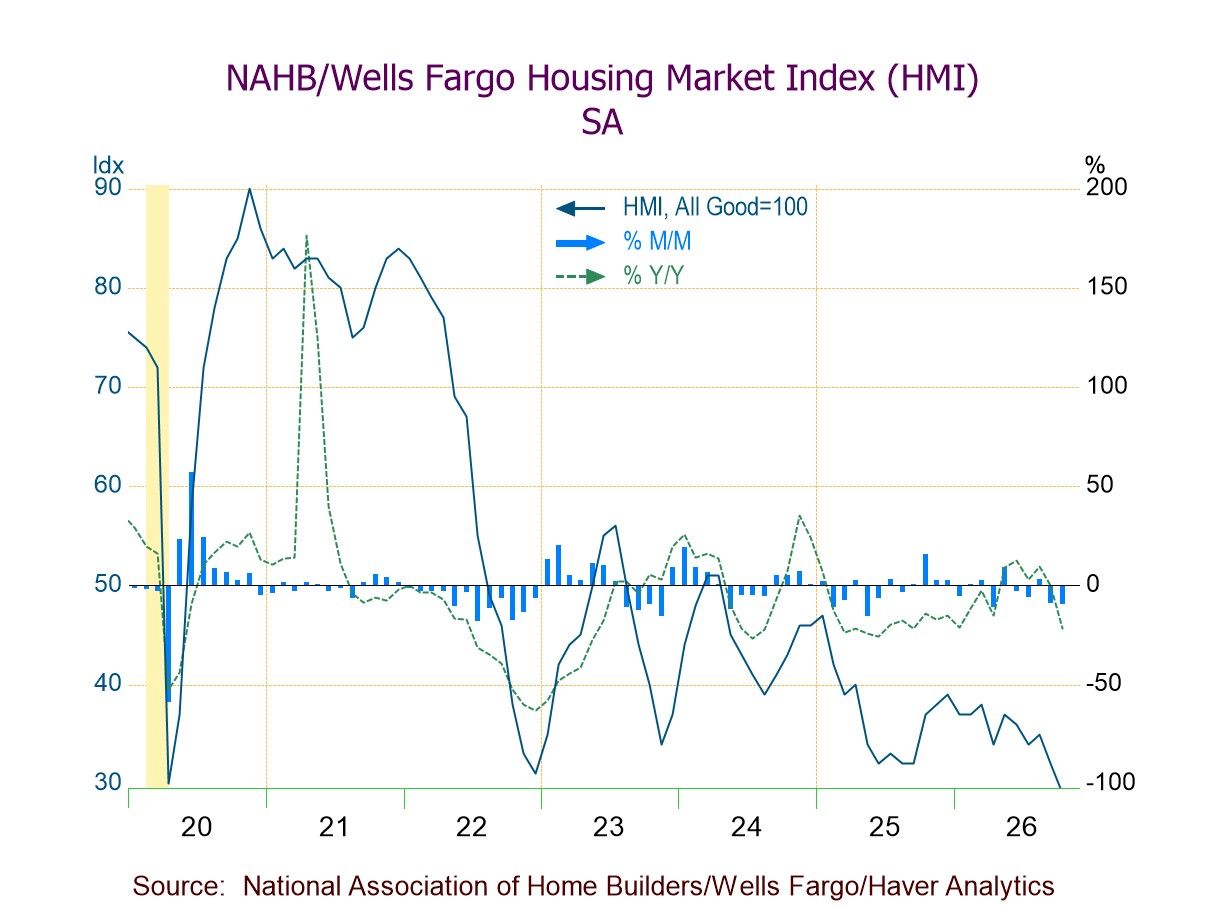
The Housing Market Index (HMI) from the National Association of Home Builders/Wells Fargo fell 9.4% m/m to 29 in October following an 8.6% decrease to 32 in September (unrevised) and a 2.9% increase to 35 in August (unrevised), indicating a further deterioration in homebuilder sentiment and overall housing-market conditions. October marked the fourth m/m fall in five months and the lowest level since June 2012. The year-on-year rate decelerated to -21.6% in October, the deepest y/y decline since September 2025, from 0.0% in September (-14.0% in October 2025). The HMI had remained below the breakeven 50 level since May 2024. The October index, lower than 37 in October 2025, was 48.2% below a high of 56 in July 2023 and 67.8% below a record-high 90 in November 2020.
Notably, the average 30-year fixed mortgage rate held at 7.40% in the weeks of October 15 and October 8, remaining the highest since the week of November 16, 2023, compared to 6.86% during all of September, according to Freddie Mac. The rate was above its recent low of 5.98% in the February 26 week but below a peak of 7.79% in the week of October 26, 2023.
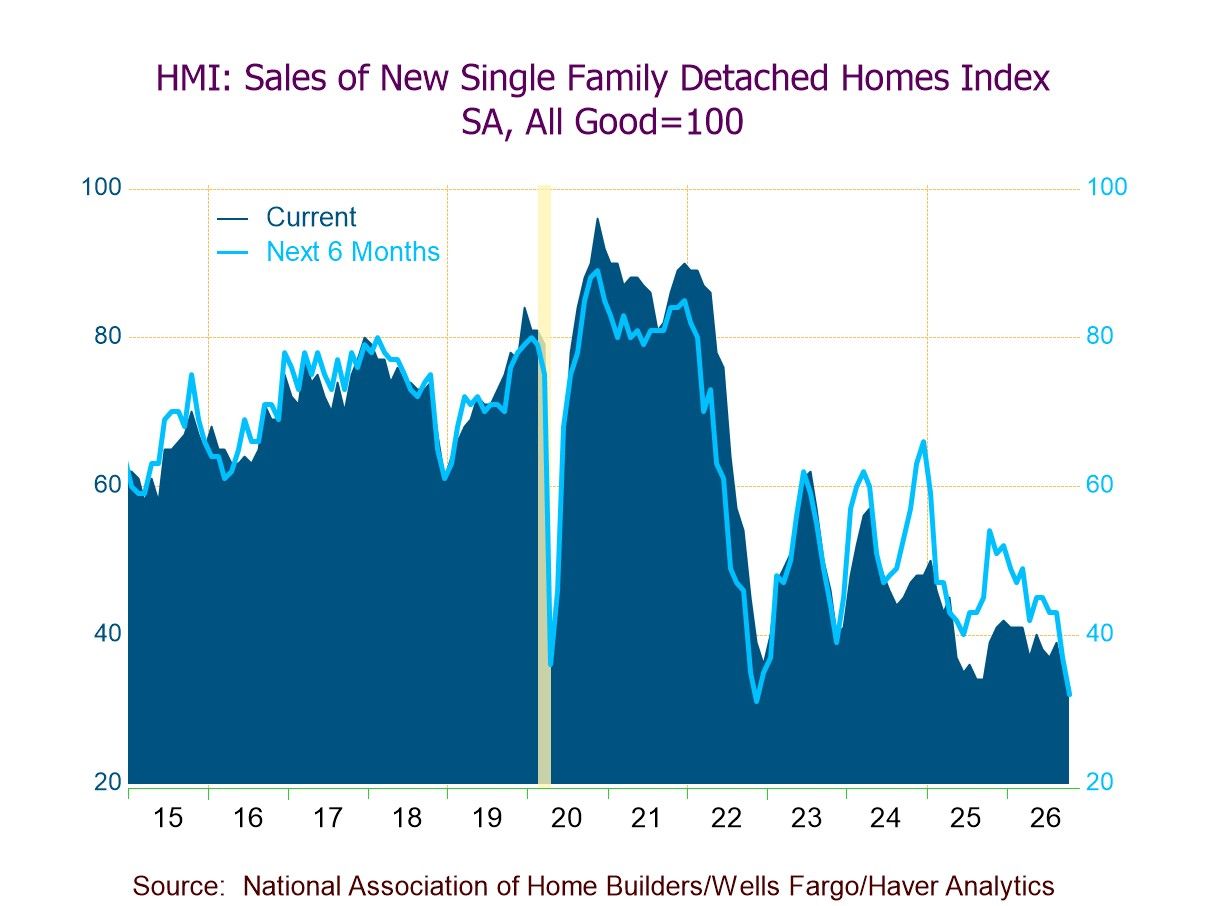
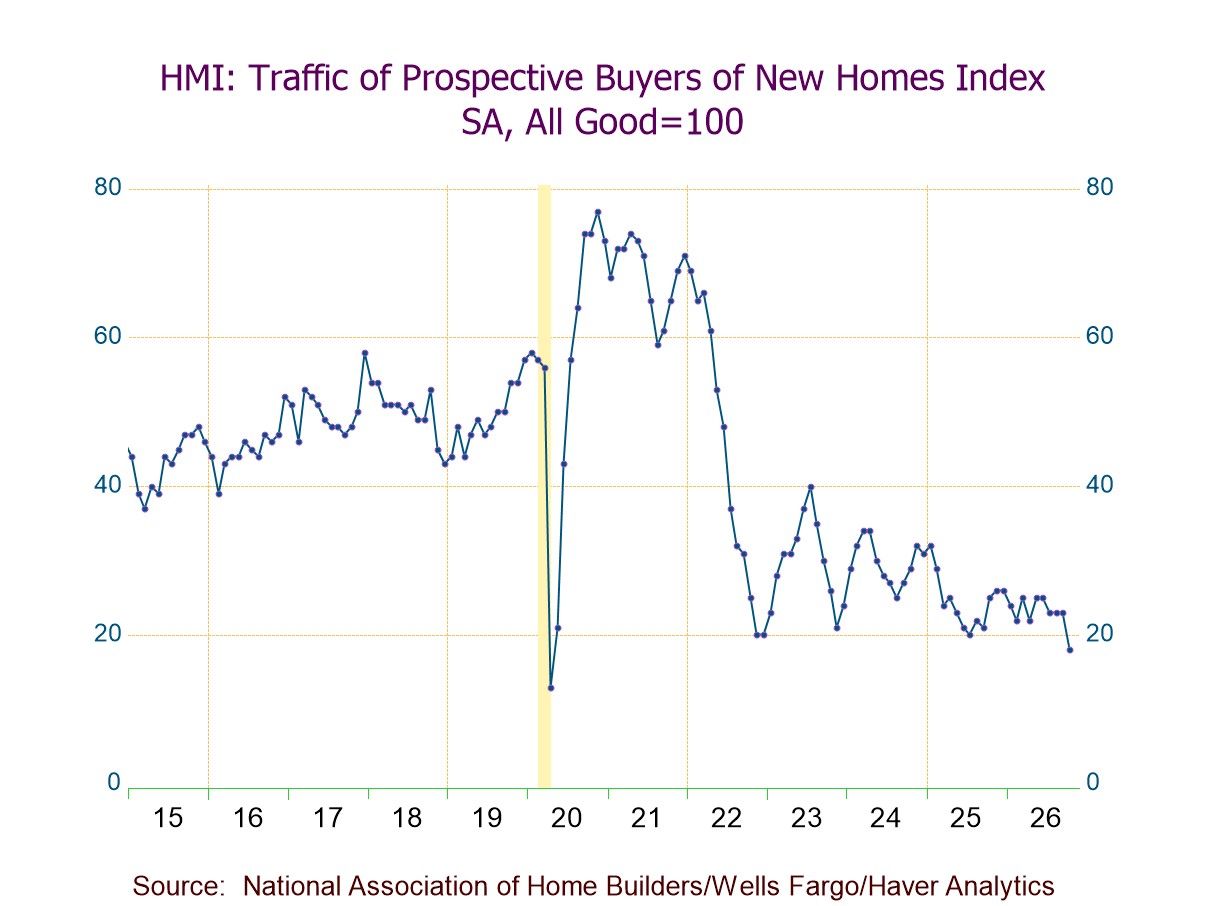
All three HMI components declined this month. The index of present single-family sales conditions slid 5.7% (-15.4% y/y) to 33 in October, the fourth m/m slide in five months and the lowest level since June 2012, after a 10.3% decrease to 35 in September. The index was 46.8% below a high of 62 in July 2023 and 65.6% below a record-high 96 in November 2020. The index of expected single-family sales for the next six months dropped 13.5% (-40.7% y/y) to 32, the third m/m fall in four months and the weakest level since November 2022, after a 14.0% September drop to 37. The index was 51.5% below a high of 66 in December 2024 and 64.0% below a record-high 89 in November 2020. The index measuring traffic of prospective buyers plunged 21.7% (-28.0% y/y) to 18, the lowest reading since April 2020, after holding at 23 in September, August and July. The index was 55.0% below a high of 40 in July 2023 and 76.6% below a record-high 77 in November 2020.
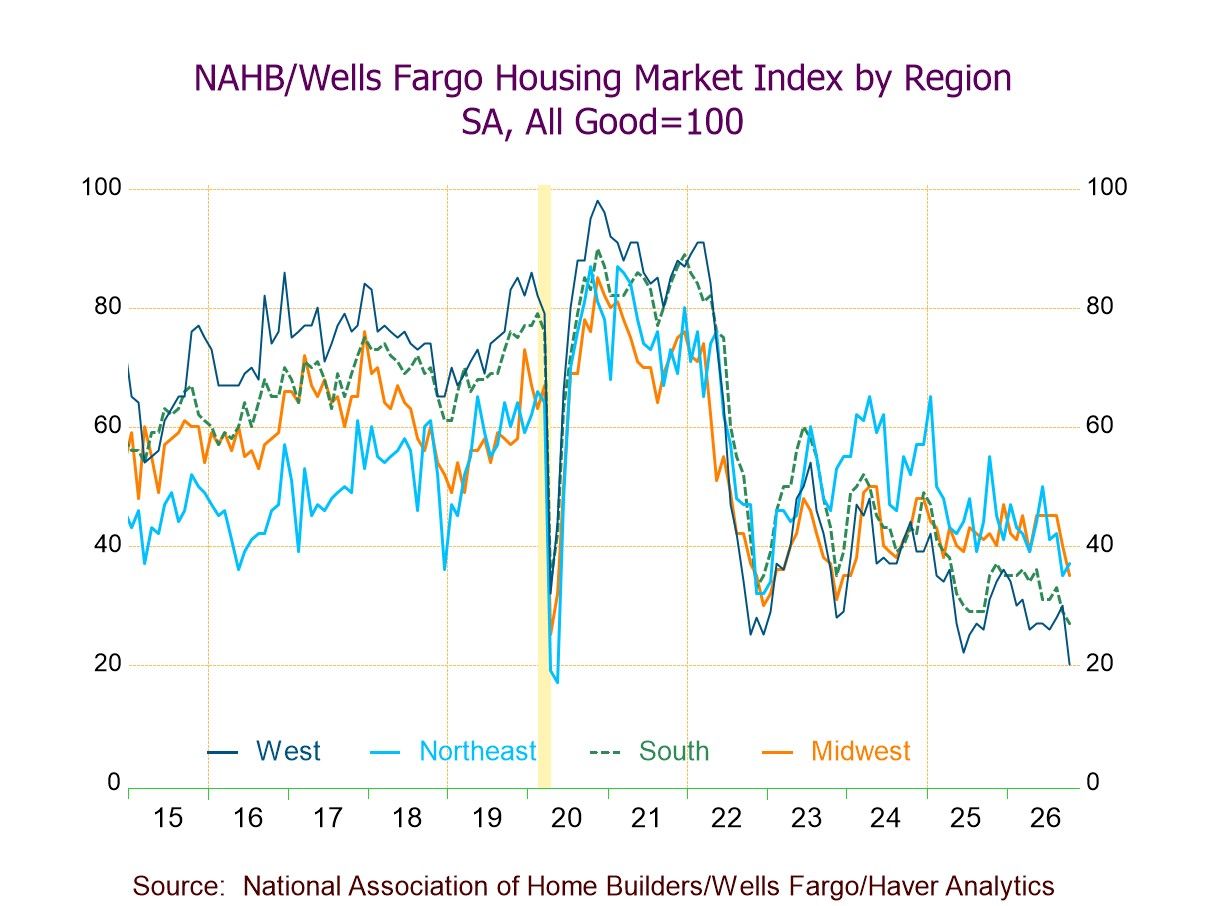
By region, the HMIs were down m/m in the West, Midwest and South this month, while up in the Northeast. The index for the West plummeted 33.3% (-35.5% y/y) to 20 in October, the first m/m decline since July and the lowest level since December 2011, reversing a 7.1% rise to 30 in September. The index for the Midwest tumbled 12.5% (-16.7% y/y) to 35, the lowest level since January 2024, after an 11.1% September fall to 40. The index for the South fell 6.9% (-22.9% y/y) to 27, matching its weakest level since June 2012, following a 12.1% September slide to 29. In contrast, the index for the Northeast rebounded 5.7% (-32.7% y/y) to 37 in October following a 16.7% drop to 35 in September.
The NAHB has compiled the Housing Market Index since 1985. It reflects survey questions which ask builders to rate sales and sales expectations as "good," "fair" or "poor" and traffic as "very high," "average" or "very low". The figures are diffusion indexes with values over 50 indicating a predominance of "good"/"very high" readings. In constructing the composite index, the weights assigned to the individual index components are: 0.5920 for single-family detached sales, present time, 0.1358 for single-family detached sales, next six months, and 0.2722 for traffic of prospective buyers. The regional indexes run back to December 2004.
These data are included in Haver's SURVEYS database. The Informa Global Markets survey is in Haver's MMSAMER database.

Winnie Tapasanun
AuthorMore in Author Profile »Winnie Tapasanun has been working for Haver Analytics since 2013. She has 20+ years of working in the financial services industry. As Vice President and Economic Analyst at Globicus International, Inc., a New York-based company specializing in macroeconomics and financial markets, Winnie oversaw the company’s business operations, managed financial and economic data, and wrote daily reports on macroeconomics and financial markets. Prior to working at Globicus, she was Investment Promotion Officer at the New York Office of the Thailand Board of Investment (BOI) where she wrote monthly reports on the U.S. economic outlook, wrote reports on the outlook of key U.S. industries, and assisted investors on doing business and investment in Thailand. Prior to joining the BOI, she was Adjunct Professor teaching International Political Economy/International Relations at the City College of New York. Prior to her teaching experience at the CCNY, Winnie successfully completed internships at the United Nations. Winnie holds an MA Degree from Long Island University, New York. She also did graduate studies at Columbia University in the City of New York and doctoral requirements at the Graduate Center of the City University of New York. Her areas of specialization are international political economy, macroeconomics, financial markets, political economy, international relations, and business development/business strategy. Her regional specialization includes, but not limited to, Southeast Asia and East Asia. Winnie is bilingual in English and Thai with competency in French. She loves to travel (~30 countries) to better understand each country’s unique economy, fascinating culture and people as well as the global economy as a whole.
More Economy in Brief
 Asia